)
o https:// significa que usted se conectó de forma segura a un sitio web .gov. Comparta información sensible sólo en sitios web oficiales y seguros.


- 21.4.4 Manual Refunds
- 21.4.4.1 Program Scope and Objectives
- 21.4.4.1.1 Background
- 21.4.4.1.2 Authority
- 21.4.4.1.3 Roles and Responsibilities
- 21.4.4.1.4 Program Management and Review
- 21.4.4.1.5 Program Controls
- 21.4.4.1.6 Terms and Acronyms
- 21.4.4.1.7 Related Resources
- 21.4.4.2 What Is a Manual Refund?
- 21.4.4.3 Why Would a Manual Refund Be Needed?
- 21.4.4.3.1 Requests for Refund Less Than $1.00
- 21.4.4.4 What Research Is Required?
- 21.4.4.4.1 Refund Statute Expiration Date
- 21.4.4.4.2 Outstanding Balances/Duplicate Refunds
- 21.4.4.4.3 Non-Master File Research
- 21.4.4.4.4 Bureau of the Fiscal Service (BFS) Non-Tax Debts
- 21.4.4.4.5 Approval from Other Functions
- 21.4.4.5 Preparation of Manual Refund Forms
- 21.4.4.5.1 Preparation of Form 5792, IDRS Generated Refund
- 21.4.4.5.1.1 IDRS Generated Refund CC "RFUND"
- 21.4.4.5.2 Preparation of the Form 3753, Manual Refund Posting Voucher
- 21.4.4.6 Other Manual Refund Requirements
- 21.4.4.6.1 Monitoring Manual Refunds
- 21.4.4.7 Other Manual Refund Programs
- 21.4.4.7.1 Photocopy Fee Refunds
- 21.4.4.7.2 Credit Card Chargebacks
- 21.4.4.7.2.1 How Is a Chargeback Initiated?
- 21.4.4.7.2.2 How Is a Chargeback Request Processed?
- Exhibit 21.4.4-1 Chargeback Request Form
- Exhibit 21.4.4-2 Notice Of Dispute Rebuttal Letter
- Exhibit 21.4.4-3 Manual Refund Checklists
- Exhibit 21.4.4-4 Accounting Function - Manual Refund Team Contact Information
- Exhibit 21.4.4-5 Manual Refund Reject Dispute Procedures
- Exhibit 21.4.4-6 Most common required fields on Form 5792, Request for IDRS Generated Refund (IGR), and Form 3753, Manual Refund Posting Voucher
Part 21. Customer Account Services
Chapter 4. Refund Inquiries
Section 4. Manual Refunds
21.4.4 Manual Refunds
Manual Transmittal
September 16, 2026
Purpose
(1) This transmits revised updates to IRM 21.4.4, Refund Inquiries, Manual Refunds.
Material Changes
(1) IRM 21.4.4.1 - For consistency updated section to denote the Audience, Policy Owner, Program Owner, Primary Stakeholder and Program Goals as those belonging to Accounts Management, Taxpayer Services. IPU 26U0211 issued 02-09-2026
(2) IRM 21.4.4.1 - For consistency with other IRMs updated Policy Owner, Program Owner, Primary Stakeholders and Program Goals, update made as result of clearance review.
(3) IRM 21.4.4.1.1 - For consistency updated section to include Taxpayer Services. IPU 26U0211 issued 02-09-2026
(4) IRM 21.4.4.1.1 - For consistency with other IRMs updated to include Live Chat, update made as result of clearance review.
(5) IRM 21.4.4.1.2 - For consistency updated the wording and included a link to Policy Statements for Customer Account Services Activities. IPU 26U0211 issued 02-09-2026
(6) IRM 21.4.4.1.2 - For consistency with other IRMs updated to include all relevant authorities, update made as result of clearance review.
(7) IRM 21.4.4.1.3(1) - For consistency updated section to state Taxpayer Services Chief oversees all policy related to this IRM. IPU 26U0211 issued 02-09-2026
(8) IRM 21.4.4.1.3(2) - For consistency added Director of Accounts Management oversees the instructions to the employees contained in the IRM content. IPU 26U0211 issued 02-09-2026
(9) IRM 21.4.4.1.3(3) - For consistency added Accounts Management Policy and Procedures IMF (PPI) Tax Analyst(s) oversees the content in this IRM and acts as a point of contact for all Accounts Management sites. IPU 26U0211 issued 02-09-2026
(10) IRM 21.4.4.1.3(5) - For clarity added information to denote that employees who prepare and input manual refunds requests following procedures in this IRM. IPU 26U0211 issued 02-09-2026
(11) IRM 21.4.4.1.3(6) - For clarity and consistency with SP accounting added information to advise when and how Form 14031 is to be sent to accounting. IPU 26U0211 issued 02-09-2026
(12) IRM 21.4.4.1.3 - For consistency with other IRMs updated to include Taxpayer Bill of Rights in this IRM section and made editorial updated throughout, update made as result of clearance review.
(13) IRM 21.4.4.1.4 - For consistency with other IRMs updated to move Program Reports and Annual Review to this section and expand Program Effectiveness, update made as result of clearance review.
(14) IRM 21.4.4.1.5 - For consistency with other IRMs updated to expand section to include all relevant controls, update made as result of clearance review.
(15) IRM 21.4.4.1.6 - Updated to include missing acronym for Taxpayer Advocate Service, update made as result of clearance review.
(16) IRM 21.4.1.1.7 - For consistency with other IRMs updated to expand section to include all relevant resources, update made as result of clearance review.
(17) IRM 21.4.4.3(3) - Updated to remove reference to completing Form 911, include that hardship time frame is ten calendar days, and to remove link to Form 8050 IRM in (f) as it is no longer valid, update made as result of clearance review.
(18) IRM 21.4.4.4.2(4) - For clarity added information about office identifiers for both IDTVA and Puerto Rico. SERP Feedback 36062. IPU 26U0211 issued 02-09-2026
(19) IRM 21.4.4.5(1) - For clarity and understanding added information about what TC 971 AC 664 identifies and procedures to follow if both TC 846 and TC 840 are discovered. IPU 26U0211 issued 02-09-2026
(20) IRM 21.4.4.5(1) - For ease of research added link to Erroneous Refunds IRM, update made as result of clearance review.
(21) IRM 21.4.4.5(2) - For clarity added information about not reinputting the manual refund on the same day as the TERUP is completed. IPU 26U0211 issued 02-09-2026
(22) IRM 21.4.4.5(3) - For consistency and clarity with SP Accounting added information about Form 14031 and the annual recertification process. IPU 26U0211 issued 02-09-2026
(23) IRM 21.4.4.5(3) - For ease of reading wording has been moved to a bullet listing, update made as result of clearance review
(24) IRM 21.4.4.5(4) (a) - For consistency with SP Accounting added additional reasons that a manual refund can be rejected, specifically corrections or alterations of the form after signature. IPU 26U0211 issued 02-09-2026
(25) IRM 21.4.4.5(4) (b) - For consistency with SP Accounting added additional reasons that a manual refund can be rejected, specifically not using the appropriate hold code. IPU 26U0211 issued 02-09-2026
(26) IRM 21.4.4.5(4) (e) - For consistency with SP Accounting added information about the SEID. IPU 26U0211 issued 02-09-2026
(27) IRM 21.4.4.5(7) (m) - For clarity added information about monitoring the input of manual refund to ensure acceptance and reinputting the manual refund if rejection is received. IPU 26U0211 issued 02-09-2026
(28) IRM 21.4.4.5(7) (m) - Updated to state that rejected manuals are to be reinput or rebutted with in five business days of Form 15276 receipt, update made as result of clearance review.
(29) IRM 21.4.4.5(10) - For consistency with other areas added note about the perfection of Form 1310 for missing tax year, update made as result of clearance review.
(30) IRM 21.4.4.5(11) - For consistency with SP Accounting added information requiring the RPD be notated in the remarks and a completed REQ54 screen print showing the RPD must be attached as back up documentation. SERP Feedback 34011. IPU 26U0211 issued 02-09-2026
(31) IRM 21.4.4.5(11) - For consistency with other IRMs added link to IRM 21.2.4.3.40.1 Computer Condition Code (CCC) 3 or U-Coded Returns. IPU 26U0384 issued 04-01-2026
(32) IRM 21.4.4.5(11) - For ease of reading wording has been revised, update made as result of clearance review
(33) IRM 21.4.4.5.1(1) - For awareness included a link to SERP where color copy of Form 5792 can be located which provides visual documentation of required fields. IPU 26U0514 issued 05-11-2026
(34) IRM 21.4.4.5.1(3) Section I - Account Information: Block 20- For consistency with SP Accounting added information requiring the RPD be notated in the remarks and a completed REQ54 screen print showing the RPD must be attached as back up documentation. IPU 26U0211 issued 02-09-2026
(35) IRM 21.4.4.5.1(3) Section I - Account Information: Block 20- For clarity added note to explain IAT tool down of characters on remarks line. SERP Feedback 37983. Added information for IDTVA to add to remarks to identify IDTVA refunds. SERP Feedback 37500. Added link to IRM 21.2.4.3.40.1 Computer Condition Code (CCC) 3 or U-Coded Returns. SERP Feedback 37583. IPU 26U0384 issued 04-01-2026
(36) IRM 21.4.4.5.1(3) - Section I - Account Information: Block 20- For clarity added example of remarks to include TC 971 AC 807 being input but no refund systemically released. SERP Feedback 40035. IPU 26U0608 issued 06-08-2026
(37) IRM 21.4.4.5.1(3) - Section I - Account Information: Block 20 - For ease of reading wording has been moved to a chart, update made as result of clearance review.
(38) IRM 21.4.4.5.1(4) - Section II - Manual Refund Authority: For consistency with SP Accounting and updated Forms 5792 updated boxes which are deemed mandatory when completing Form 5792. IPU 26U0211 issued 02-09-2026
(39) IRM 21.4.4.5.1(4) - Section II - Manual Refund Authority: Box 1c: for consistency updated corrected IRM reference for issuing the Injured Spouse Refund. Box 6: added to check box when all supporting documentation I attached and complete. Box 11: For clarity added directions to check DMER Print attached box when DMER form is attached and to enter initials of manager when form is created. SERP Feedback 37877 and 38159. IPU 26U0384 issued 04-01-2026
(40) IRM 21.4.4.5.1(5) - Section III - Interest Computation: For consistency with SP Accounting and updated Forms 5792 updated information which is deemed mandatory when completing Form 5792. IPU 26U0211 issued 02-09-2026
(41) IRM 21.4.4.5.1(5) - For clarity added when completing the COMPA section in the IAT Manual Refund Tool to the direction when using multiple COMPA definers. SERP Feedback 37263. IPU 26U0384 issued 04-01-2026
(42) IRM 21.4.4.5.1(5) - Section III - Interest Computation: To support updates on Form 5792, added the "From" box as a required field of completion. IPU 26U0608 issued 06-08-2026
(43) IRM 21.4.4.5.1(6) Section IV - Manual Refund Approval: Block 1 - For consistency with accounting updated to show any refund input between 6 p.m. and midnight local time is to notate “Y” in Section IV Box 1 of the Form 5792 along with the number of the employee inputting the CC RFUND. Update made as result of clearance review.
(44) IRM 21.4.4.5.1(6) Section IV - Manual Refund Approval: Block 2a - For clarity added information about the SEID. IPU 26U0211 issued 02-09-2026
(45) IRM 21.4.4.5.1(6) Section IV - Manual Refund Approval: Block 3 - For clarity added information about the specific phone number which must be included on Form 5792. IPU 26U0211 issued 02-09-2026
(46) IRM 21.4.4.5.1(6) Section IV - Manual Refund Approval: Block 3 - For clarity added information to include a managers phone number beginning with 833 including an extension number is acceptable. IPU 26U0384 issued 04-01-2026
(47) IRM 21.4.4.5.2(1) - For awareness included a link to SERP where color copy of Form 3753 can be located which provides a visual of documentation of required fields. IPU 26U0514 issued 05-11-2026
(48) IRM 21.4.4.5.2(1) - Moved the wording to a bulleted list to improve readability. Expanded the section to include guidance for international taxpayers and manual refunds exceeding $2 million for individuals or $5 million for C corporations. Updated based on clearance review.
(49) IRM 21.4.4.5.2(5) - For inclusion of missing procedures added instruction for international taxpayers that do not have a U.S. Bank Account and live in a country that does not accept U.S. Treasury Checks. Subsequent paragraphs are renumbered. IPU 26U0514 issued 05-11-2026
(50) IRM 21.4.4.5.2(5) Section I - Account Information: Block 11- removed information for including direct deposit information in Block 11 and added Block 11a, Routing number, Block 11b, Account number and Block 11c, Account type to the section to explain the entries for those lines. SERP Feedback 37345 and 37770. IPU 26U0384 issued 04-01-2026
(51) IRM 21.4.4.5.2(6) Section II - Manual Refund Authority: For consistency with SP Accounting and updated Forms 3753 updated boxes which are deemed mandatory when completing Form 3753. IPU 26U0211 issued 02-09-2026
(52) IRM 21.4.4.5.2(6) Section II - Manual Refund Authority: Box 13: For clarity added direction to check DMER Print attached box when DMER form is attached. SERP Feedback 37877. IPU 26U0384 issued 04-01-2026
(53) IRM 21.4.4.5.2(7) Section II - Manual Refund Authority: Box 11: To include procedures for External Leads and Chargebacks, which are not subject to offset, updated to have statement "Not subject to TOP offset" in the other remarks field when submitting the form. IPU 26U0514 issued 05-11-2026
(54) IRM 21.4.4.5.2(7) Section III - Interest Computation: For consistency with SP Accounting and updated Forms 3753 updated information which is deemed mandatory when completing Form 3753. IPU 26U0211 issued 02-09-2026
(55) IRM 21.4.4.5.2(8) Section IV - Other Remarks- For consistency with SP Accounting added information requiring the RPD be notated in the remarks and a completed REQ54 screen print showing the RPD must be attached as back up documentation. IPU 26U0211 issued 02-09-2026
(56) IRM 21.4.4.5.2(8) Section IV - Other Remarks- For consistency with other IRMs added link to IRM 21.2.4.3.40.1 Computer Condition Code (CCC) 3 or U-Coded Returns. IPU 26U0384 issued 04-01-2026
(57) IRM 21.4.4.5.2(9) Section IV - Manual Refund Approval: Block 4 - For clarity added information about the specific phone number which must be included on Form 5792. IPU 26U0211 issued 02-09-2026
(58) IRM 21.4.4.5.2(9) Section IV - Manual Refund Approval: For clarity added note for information about the SEID. IPU 26U0211 issued 02-09-2026
(59) IRM 21.4.4.5.2(9) Section IV - Manual Refund Approval: Block 4 - For clarity added information to include a managers phone number beginning with 833 including an extension number is acceptable. IPU 26U0384 issued 04-01-2026
(60) IRM 21.4.4.5.2(9) Section IV - Other Remarks: For ease of reading wording has been moved to a chart, update made as result of clearance review.
(61) IRM 21.4.4.6(8) - For consistency with other areas added note about the perfection of Form 1310 for missing tax year, update made as result of clearance review.
(62) IRM 21.4.4.6(10) - Updated to expand information related to refunds of over $2 million to an individual or $5 million to a C Corporation, update made as result of clearance review.
(63) IRM 21.4.4.6.1 - For consistency added information about monitoring the input of manual refund to ensure acceptance and reinputting the manual refund if rejection is received. IPU 26U0211 issued 02-09-2026
(64) IRM 21.4.4.7.2.2(8) - For clarity added note to advise the DLN that will be used on Form 2424 if a payment has been transferred off the account, then back. SERP Feedback 39534. IPU 26U0514 issued 05-11-2026
(65) IRM 21.4.4.7.2.2(11) - For consistency with SP Accounting added information and actions to take prior to issuing manual refunds regarding Credit Card Processor Chargebacks.
(66) Exhibit 21.4.4-3(1) - For consistency with SP Accounting added information and actions to take prior to issuing manual refunds. IPU 26U0211 issued 02-09-2026
(67) Exhibit 21.4.4-3(2) - For consistency with SP Accounting added information requiring the RPD be notated in the remarks and a completed REQ54 screen print showing the RPD must be attached as back up documentation. IPU 26U0211 issued 02-09-2026
(68) Exhibit 21.4.4-3(2) - For consistency with other IRMs added link to IRM 21.2.4.3.40.1 Computer Condition Code (CCC) 3 or U-Coded Returns. IPU 26U0384 issued 04-01-2026
(69) Exhibit 21.4.4-3(3) - To include missing information, included for Section I (Account information) of Form 5792: Box 11, ULC Code; Section II (Manual Refund Authority) of Form 5792: Box 10,11 & 13; Section III (Interest Computation) of Form 5792: Interest Computation Attached box; Section IV (Manual Refund Approval) of Form 5792: Box 3 as items to be verified on Form 5792 when creating or reviewing the form. IPU 26U0211 issued 02-09-2026
(70) Exhibit 21.4.4-3(3) - For consistency with other IRMs added link to IRM 21.2.4.3.40.1 Computer Condition Code (CCC) 3 or U-Coded Returns. For clarity added directions to check DMER Print attached box when DMER form is attached. SERP Feedback 37877. For clarity added information to include a managers phone number beginning with 833 including an extension number is acceptable. IPU 26U0384 issued 04-01-2026
(71) Exhibit 21.4.4-3(4) - To include missing information, included for Section I (Account information) of the Form 3753: Box 10b to verify the , refund amount with source document amount; Section II (Manual Refund Authority) of the Form 3753: Box 3, 4, 5, 6, 9, 11,13,& 17; Section III (Interest Computation) of the Form 3753: Interest Computation Attached box; Section V (Manual Refund Approval) of Form 5792: Box 2a & Box 4 as items to be verified on Form 3753 when creating or reviewing the form. IPU 26U0211 issued 02-09-2026
(72) Exhibit 21.4.4-3(4) - For consistency with other IRMs added Block 11a, Routing number, Block 11b, Account number and Block 11c, Account type to the section to explain the entries for those lines. SERP Feedback 37345 and 37770. For clarity added directions to check DMER Print attached box when DMER form is attached. SERP Feedback 37877. For clarity added information to include a managers phone number beginning with 833 including an extension number is acceptable. IPU 26U0384 issued 04-01-2026
(73) Exhibit 21.4.4-4 - For clarity added Puerto Rico under Ogden SP Accounting. IPU 26U0211 issued 02-09-2026
(74) Exhibit 21.4.4-4 - For clarity added daily cut off times for each processing site, update made as result of clearance review.
(75) Exhibit 21.4.4-5 - For clarity added new section about Manual Refund Reject Dispute Procedures to help limit the confusion, or potential argument, on the process to be followed when a dispute is raised about a manual refund rejection from SP accounting. IPU 26U0211 issued 02-09-2026
(76) Exhibit 21.4.4-5 - Updated to include information when sending rebuttal email to allow for easier tracking, update made as result of clearance review.
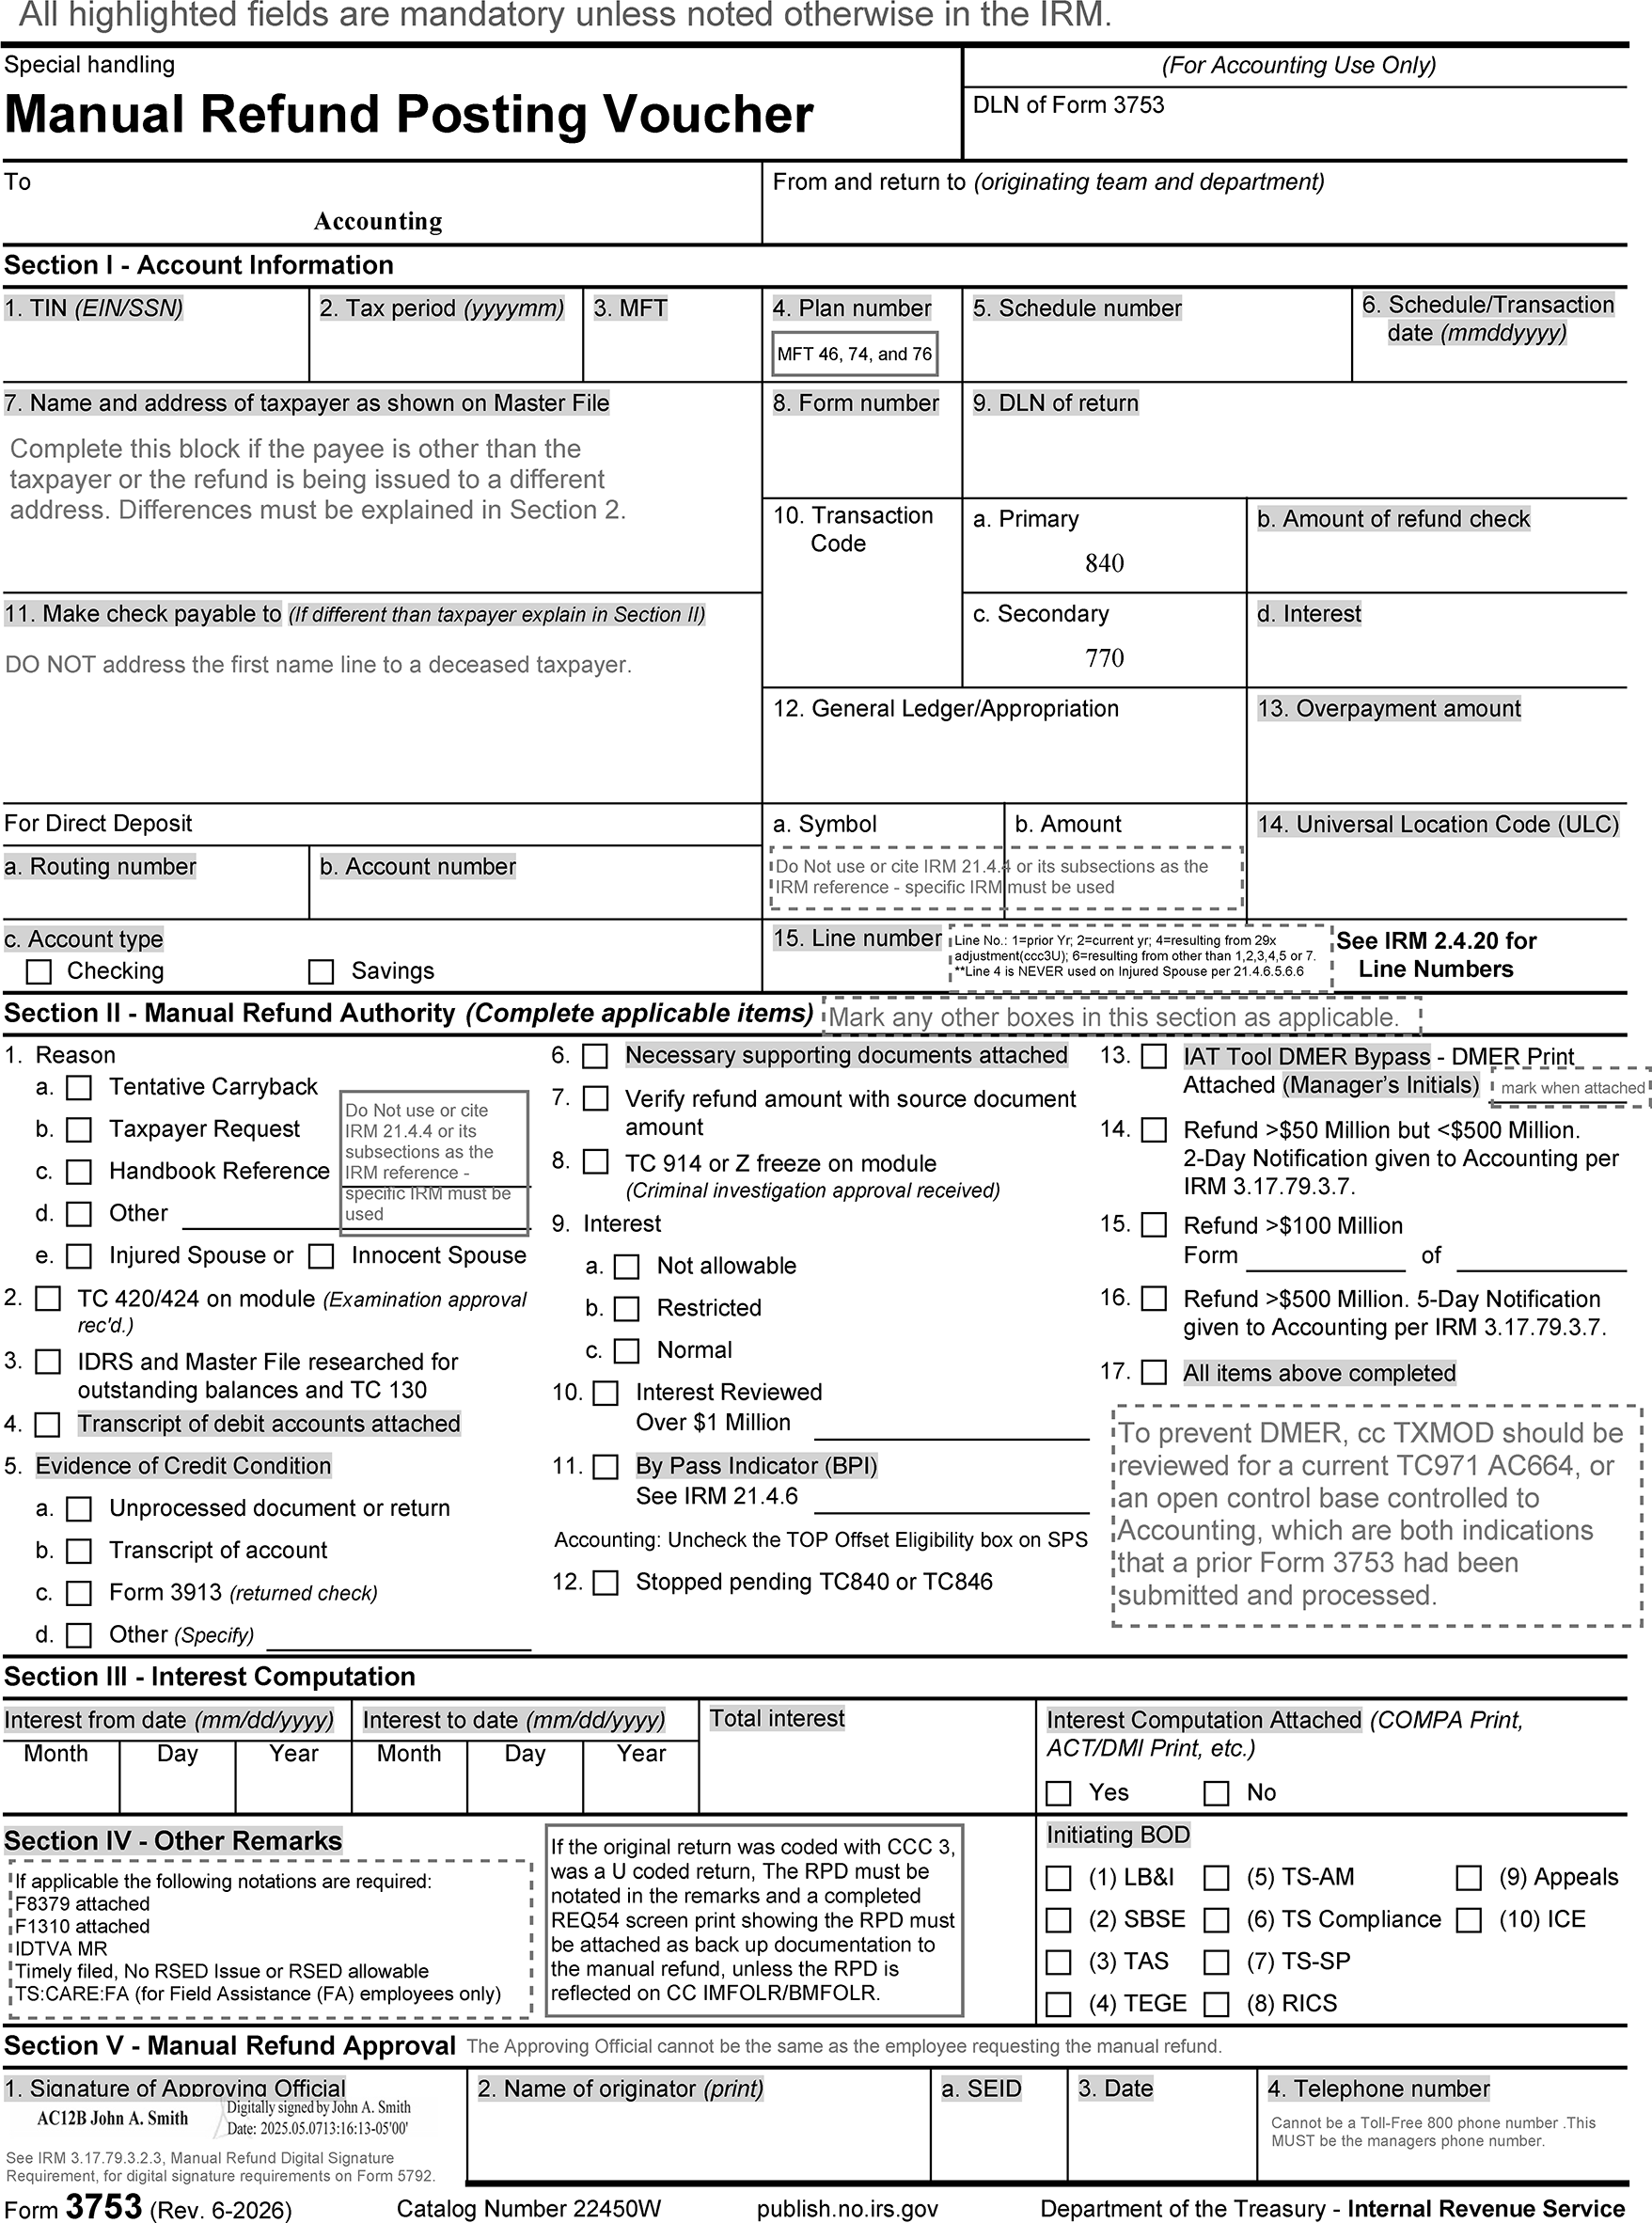
(77) Exhibit 21.4.4-6 - For visual aid of written instructions added exhibit of Form 5792 and Form 3753 with required fields highlighted and included a link to SERP where color copies of exhibits can be located. IPU 26U0514 issued 05-11-2026
(78) Exhibit 21.4.4-6 - To support updates on Form 5792 and Form 3753, updated job aids to reflect revised forms, also added reminder in Section II - Manual Refund Authority that handbook reference cannot be IRM 21.4.4 or its subsections; Section III - Interest Computation added from box as a required field; added reminder in Section IV - Manual Refund Approval that the IDRS number of the employee inputting the RFUND must match IDRS. Changed the text only link to replace the step list with a bullet list for better understanding. IPU 26U0608 issued 06-08-2026
(79) IRM 21.4.4 - Editorial changes have been made throughout the IRM for clarity and to include Live Chat as a form of communication to align with IMF International Live Chat Expansion. Reviewed and updated plain language, grammar, web addresses, IRM references, and legal references. IPU 26U0514 issued 05-11-2026
(80) IRM 21.4.4 - Artificial Intelligence (AI) tools were used to make editorial changes including plain language revisions, correcting punctuation and grammar, and adhering to IRM style format.
Effect on Other Documents
The IRM 21.4.4, Manual Refunds, dated August 27, 2025 (effective 10-01-2025) is superseded. This IRM incorporates Interim Procedural Updates (IPU) 26U0211 (effective 02-09-2026), 26U0384 (effective 04-01-2026), 26U0514 (effective 05-11-2026), 26U0608 (effective 06-08-2026).Audience
Employees located in all business operating divisions who have contact with taxpayers either by phone, correspondence, Live Chat , or personal contact.Effective Date
(10-01-2026)LuCinda Comegys
Director, Accounts Management
Taxpayer Services
Purpose: This IRM covers general information on preparing manual refunds. Any specific program instructions for issuing a manual refund are found in the issue specific IRM.
Audience: The primary users of the IRM are all the IRS employees in Business Operating Divisions (BODs) who are in contact with taxpayers by telephone, correspondence, Live Chat, or in person and prepare and input manual refunds.
Policy Owner: The policy owner of this IRM is the director of Accounts Management.
Program Owner: The program owner of this IRM is Accounts Management, Policy and Procedures IMF (PPI), Individual Adjustments.
Primary Stakeholders: The primary stakeholders are organizations that Accounts Management collaborates with including:
Taxpayer Services (TS) Service Centers
Submission Processing (SP)
Customer Assistance-Relationship and Education (CARE)
Small Business/ Self Employed (SB/SE) Service Centers
Compliance
Return Integrity and Verification Operations (RIVO)
Criminal Investigation (CI)
Program Goals: The program goals for this type of work are:
The Accounts Management Program Letter on the AM website has more information on these goals. A copy of the Accounts Management Program Letter can also be found in IRM 1.4.16 , Accounts Management Guide for Managers.Provide high-quality service to telephone and face-to-face customers
Achieve a high customer accuracy rate for phone calls and paper adjustments related to unpostable transactions
Resolve paper adjustment cases related to unpostable transactions efficiently using taxpayer-provided documentation in accordance with IRS policy and procedures
Continuously assess program vulnerabilities and identify opportunities for improvement
Communicate effectively with customers and stakeholders
Employees in the Accounts Management (AM), Taxpayer Services (TS) organization respond to taxpayer inquiries and Live Chat as well as process claims and other internal adjustment requests.
In the course of their duties, it is sometimes necessary for employees to bypass the normal Master File processes that result in a systemically generated refund and instead issue a manual refund. This IRM provides specific guidance for preparing and inputting manual refunds.
The authorities for this IRM are found in IRM 1.2.1.2, Policy Statements for Organization, Finance and Management Activities, and includes:
IRS Restructuring and Reform Act (RRA 98) Section 3705(a), enacted on July 22, 1998
The Protecting Americans from Tax Hikes (PATH) Act, enacted December 18, 2015
The Disaster Tax Relief and Airport and Airway Extension Act of 2017, enacted on September 29, 2017
Tax Cuts and Jobs Act (TCJA) (Public Law 115-97), enacted on December 22, 2017
The Bipartisan Budget Act of 2018, enacted on February 9, 2018
The Coronavirus Aid, Relief, and Economic Security (CARES) Act, enacted on March 27, 2020
The Consolidated Appropriations Act, 2021, enacted on December 27, 2020
The American Rescue Plan Act of 2021, enacted on March 11, 2021
The Inflation Reduction Act of 2022 and CHIPS Act, enacted on August 16, 2022
Working Families Tax Cuts (WFTC), enacted on July 4, 2025
IRC 6201, Assessment authority
IRC 6204, Supplemental assessments
IRC 6212, Notice of deficiency
IRC 6402, Authority to Make Credits or Refunds
IRC 6601, Interest on underpayment, nonpayment, or extensions of time for payment, of tax
IRC 7508A, Authority to postpone certain deadlines by reason of federally declared disaster, significant fire, or terroristic or military actions
IRC 7801, Authority of Department of the Treasury
IRC 7805, Rules and Regulations
Policy Statement 5-2, Collecting Principles
Policy Statement 10-2, Privacy First: Protecting Privacy and Safeguarding Confidential Tax Information
Policy Statement 21-1, Service Commitment to Taxpayers Service Program
Policy Statement 21-2, The public impact of clarity, consistency, and impartiality in dealing with tax problems must be given high priority
Policy Statement 21-3, Timeliness and Quality of Taxpayer Correspondence
Policy Statement 21-4, One-stop service defined
Policy Statement 21-5, Assistance furnished to taxpayers in the correction of accounts
Policy Statement 21-6, Monitoring Employee Contacts with Taxpayers
Murray v. U.S., 300 F.2d 804, 806 (1st Cir. 1962).
The Taxpayer Services Chief oversees all policies related to this IRM. This IRM is published annually.
The Accounts Management director oversees the IRM content that provides instructions to employees.
Accounts Management Policy and Procedures IMF (PPI) Individual Adjustments, oversee the content in this IRM and acts as the point of contact for all Accounts Management sites.
Manager’s and lead’s ensure compliance with the guidance and procedures in this IRM for Returned Refunds/Releases case resolution.
The Taxpayer Bill of Rights (TBOR) summarizes existing rights in the tax code, presents them in plain language, and groups them into 10 fundamental rights. Employees must be familiar with and act in accordance with taxpayer rights.
IRC 7803(a)(3), Execution of Duties in Accord with Taxpayer Rights
For more information about the TBOR, see Taxpayer Bill of Rights
Additional information is found in IRM 1.1.13.6.3, Accounts Management and IRM 21.1.1, Accounts Management and Compliance Services Overview.
Employees respond to taxpayer inquiries, and prepare and input manual refunds requests following procedures in this IRM. In addition, employees MUST complete these manual refund courses via the Integrated Talent Management (ITM) training system:
If the employee And Then the employee Initiates, reviews and/or signs manual refunds HAS NOT previously completed ITM Course 30914, Manual Refunds MUST complete ITM Course 30914, Manual Refunds Initiates, reviews and/or signs manual refunds HAS completed ITM Course 30914, Manual Refunds, previously MUST complete ITM Course 30914a, Manual Refunds Recertification, annually Annually, employees authorized to approve manual refunds with an effective date of January 01, are responsible to submit Form 14031, Manual Refund Signature Form to accounting, see IRM 21.4.4.5 , Preparation of Manual Refund Forms.
Program Reports: The program reports in this IRM help Accounts Management contact representatives (CRs) and tax examiners (TEs) identify applicable reports. For reports concerning quality, inventory, and aged listings, refer to IRM 1.4.16, Accounts Management Guide for Managers. Aged listings are also available through Control Data Analysis, Project PCD, on the Control-D/Web Access server which requires a login.
Program Effectiveness: The program effectiveness of this IRM are measured through the following:
National Quality Review System (NQRS)
Centralized Evaluative Review (CER)
Managerial reviews
Quarterly reviews conducted by Accounts Management Policy and Procedures IMF (PPI), Individual Adjustments
Reviews and analysis must evaluate whether employees use IRM guidance to perform required account actions and duties.Annual Review: The processes in this IRM are reviewed annually to ensure accuracy and promote consistency in tax administration.
The Federal Managers Financial Integrity Act (FMFIA) of 1982 requires federal agency executives to periodically review and annually report on internal control systems.
The Government Accountability Office (GAO) establishes standards for effective internal control in the federal government.
Program Controls: Quality data and guidelines for measurement are referenced in IRM 21.10.1, Embedded Quality (EQ) for Accounts Management, Campus Compliance, Tax Exempt Government Entities, Return Integrity and Compliance Services (RICS) and Electronic Products and Services Support. The Embedded Quality Review Program (EQRS) is the system used by Accounts Management to review employee work quality. The quality review process monitors, measures, and improves the quality of work. Quality review data provides statistics for the Service’s business results component of Balanced Measures and identifies trends, problem areas, training needs, and opportunities for improvement.
The Centralized Quality Review System (CQRS), operated by the Joint Operations Center (JOC), provides independent quality review services for multiple product lines.
Accounts Management Policy and Procedures IMF (PPI), Individual Adjustments, conducts operational quality reviews. Local quality reviews support employee development and on-the-job instruction. The Accounts Management function may also request local quality reviews for processes not subject to national quality review. Managerial reviews, prepared in EQRS, evaluate employee performance.
Quality Review data helps management measure and improve program effectiveness by identifying the following:
Defects resulting from site or systemic actions or inactions
Drivers of customer accuracy
Reasons for defect occurrence
Defect trends
Recommendations for corrective action
Training needs
For a comprehensive listing of any IRS acronyms, refer to the Acronym Database.
The following are the common acronyms found in this IRM:
Acronym Definition ACT Automated Computation Tool BFS Bureau of the Fiscal Service BOFD Bank of First Deposit BPI Bypass Indicator CII Correspondence Imaging Inventory DMI Decision Modeling Inc EMT Erroneous Manual Refund Tool GATT General Agreement on Tariffs and Trade HAL IRS Holds Automated Listing OBL Outstanding Obligation OBR Offset Bypass Refund RAC Refund Anticipation Check RAL Refund Anticipation Loan RFC Regional Finance Center RPD Return Processable Date TAS Taxpayer Advocate Service TOP Treasury Offset Program TS Taxpayer Services ULC Universal Location Code
Refer to IRM 1.4.2.1.8, Related Resources, for information on related resources that impact internal controls.
Below are additional websites, job aids, or electronic tools that are required to assist in completing work in Accounts Management (AM) (list is not all inclusive):
Account Management Services (AMS) is a web-based system that emphasizes the sharing of key business data and provides a consolidated and synchronized view of taxpayer data and contact information from various IRS systems
CCJA - IDRS Command Code Job Aid
Correspondence Imaging Inventory (CII) may be used for scanning all AM adjustment receipts and correspondence into digital images for case work resolution
Correspondex Letters
Document 6209 (IRS Processing Codes and Information)
Electronic Publishing website may be used to research forms, instructions, publications, and other Internal Revenue Manuals, revenue procedures and IRS announcements
Employee User Portal (EUP) is used to view corporate and individual electronic tax returns filed via MeF
Integrated Automation Technologies (IAT) Tool Instructions are tools used to simplify taxpayer account processing by assisting the user with IDRS research and input
Servicewide Electronic Research Program (SERP) is utilized to find SERP Alerts, IPUs, Correspondex Letters, IRM Supplements and other information
Technical Communication Documents (TCD)
Bureau of the Fiscal Service - Treasury Check Information System
The Taxpayer Advocate Service is an independent organization within the Internal Revenue Service (IRS), led by the National Taxpayer Advocate, that helps taxpayers and protects taxpayer rights. TAS offers free help to taxpayers when a tax problem is causing a financial difficulty, when they’ve tried and been unable to resolve their issue with the IRS, or when they believe an IRS system, process, or procedure just isn't working as it should. TAS strives to ensure that every taxpayer is treated fairly and knows and understands their rights under the Taxpayer Bill of Rights. TAS has at least one taxpayer advocate office located in every state, the District of Columbia, and Puerto Rico.
A manual refund, transaction code (TC) 840, is a refund that is not generated through normal Master File processing (TC 846). Manual refunds are requested on either Form 3753, Manual Refund Posting Voucher, or Form 5792, Request for IDRS Generated Refund.
Employees from all functions can initiate requests for manual refunds. The Form 3753 or Form 5792 manual refund requests are prepared by the initiator and are processed by the Accounting Function of the Submission Processing Campus who schedules and certifies manual refunds.
Note:
The open control BOD should be the one initiating the MR in general. TAS can initiate manual refunds only if they have the delegated authority to do so and the taxpayer is entitled to a refund. Otherwise, TAS employees can only initiate requests for manual refunds (MR) after the IRS has determined the taxpayer is entitled to a refund and the amount of such refund. TAS can initiate refunds without the IRS approval, such as OBRs, provided TAS has the delegated authority to do so (i.e., if there are no open controls to another function). If there is an open control, then TAS would have to get the BOD approval first if they won't initiate it.
This IRM provides information on the types of manual refunds and the actions needed to initiate a manual refund. Other IRM sections and subsections will give specific situations when a manual refund is required.
The most frequent causes of manual refunds are:
The refund will be going to someone other than the entity name on the Master File.
A hardship situation that requires a quicker refund than normal systemic processing can provide, a request is sent by the Taxpayer Advocate Service (TAS) using an Operations Assistance Request (OAR).
The refund is not for a Master File account (e.g., Photocopy Fees or Credit Card Chargebacks), or
Systemic limitations prevent a normal computer-generated refund.
Input of manual refunds without consideration of systemic account issues or Customer Account Data Engine (CADE) 2 processing (on Individual Master File (IMF) accounts) can result in erroneous refunds. In addition, improper IDRS controls and lack of required monitoring can result in erroneous refunds.
Caution:
A manual refund cannot be initiated if an IDRS generated refund will be issued within two cycles (10 business days). If a manual refund needs to be initiated, all efforts must be made to prevent a duplicate systemic refund from being issued.
Exception:
For taxpayers with a hardship, as defined in IRM 13.1.7.3.1, TAS Case Criteria 1 - 4, Economic Burden, or in some circumstances IRM 13.1.7.3.2, TAS Case Criteria 5 - 7, Systemic Burden, TAS will initiate a hardship manual refund when the situation necessitates that the refund be issued sooner than normal systemic processing will allow.
Caution:
Per the Protecting Americans from Tax Hikes Act of 2015 (the PATH Act), section 201(b) which is codified at IRC 6402(m), current calendar year refunds cannot be issued prior to February 15th if certain credits are claimed. A C- Freeze will be established on these accounts to hold the refunds and cannot be released by the posting of a TC 29X. Manual refunds cannot be issued on these accounts prior to February 15th. See IRM 21.5.6.4.5.1, C- Freeze Refund Holds, for further information. For fiscal year filers, a manual refund cannot be issued prior to the 15th day of the second month following the close of the taxable year.
The following are some circumstances that could warrant the issuance of a manual refund. This list is not all-inclusive:
Hardship - Those refunds needed are based on a hardship where the taxpayer needs the refund in less than ten calendar days.
When it is necessary to expedite a refund, employees can use Form 5792 to provide the customer with a refund within 7 to 10 days. TAS employees can initiate a hardship direct deposit, once all documentation has been received, by using Form 3753, to provide a refund to the customer within 2 to 3 business days. See IRM 3.17.79.6.4.2, Certifying Automated Clearing House (ACH)/Direct Deposit Hardship Refunds, for manual refund procedures to issue an Automated Clearing House (ACH)/direct deposit hardship manual refund.The completed Forms 3753 and/or Forms 5792 are processed by the Submission Processing Accounting Function. The manual refund is issued within a few business days of IDRS input. However, when issuing a refund utilizing Form 3753, it takes 4 - 6 weeks for the TC 840 to post to Master File. When completing the manual refund request, TAS must use the specific IRM reference as to why the manual refund is being issued for hardship.Caution:
Prior to issuing a manual refund on a taxpayer's hardship request, determine if the original return refund request is a direct deposit, Refund Anticipation Loan (RAL), or Refund Anticipated Check (RAC). Releasing an account refund hold to generate a refund to these accounts could result in a quicker refund to the taxpayer than issuing a paper (Form 5792) manual refund.
Note:
Taxpayers requesting manual refunds for hardship reasons will be referred to TAS for hardship determination unless the refund can be initiated within 24 hours. Areas referring these cases to TAS should follow procedures in IRM 21.1.3.18, Taxpayer Advocate Service (TAS) Guidelines. See IRM 13.1.7.5, Same Day Resolution by Operations, for situations that meet the “Same Day” definition. Do not refer same day cases to TAS unless the taxpayer asks to be transferred and the case meets TAS criteria. Refer to the TAS Criteria Tool for help in determining whether a taxpayer can be referred to TAS.
Note:
When TAS has made a hardship determination on an account with an open control in another area, they will send an OAR to that area requesting the refund be issued or that TAS be given written approval (via the OAR or e-mail) to input the manual refund. If the area is to release the refund, the refund should be released unless the OAR indicates a manual refund must be issued. Refer to IRM 3.17.79.3.3, Issuing Hardship Refunds, to determine back-up documentation requirements.
Dual Status Returns - See IRM 3.17.79.3.12, Non-Resident Alien and Dual Status Refunds (Austin Only District Office or DO 97 and 98).
Civil Cases
Form 4466, Corporation Application for Quick Refund of Overpayment of Estimated Taxes. See IRM 3.17.79.3.11, Form 4466, Corporation Application for a Quick Refund of Overpayment of Estimated Tax.
Form 8302, Electronic Deposit of Tax Refund of $1 Million or More. See IRM 3.17.79.3.10.1, Direct Deposits of Tax Refunds of $1 Million or More, or Due to Financial or International Hardships.
Form 8050, Direct Deposit of Corporate Tax Refund.
Large dollar refunds - Any refund of $100 million or more, must be issued as a manual refund on a Form 3753. Systemic refunds can be generated on IDRS (TC 846) for under these amounts, unless a manual refund is required for another reason.
Non-Master File Refunds
Congressional Inquiries
Interest Bearing Excise Fuel Claims - See IRM 4.24.22.4.5.3, Form 8849, Schedule 2, Sales by Registered Ultimate Vendors, IRM 4.24.22.4.5.4, Form 8849, Schedule 3, Certain Fuel Mixtures and the Alternative Fuel Credit, and IRM 4.24.22.4.5.7, Form 8849, Schedule 8, Registered Credit Card Issuers.
Offers in Compromise - See IRM 5.19.7.7.2, Disposition of OIC Deposits.
State Income Tax Levy Program - See IRM 5.19.9.3, State Income Tax Levy Program (SITLP) General.
Return of levied property to taxpayer - See IRM 5.19.4.4.12, Wrongful Levies, or IRM 5.11.2.3.2.2, Certain Wrongful Levy Situations.
Statute Imminent cases
Injured Spouse Claims - See IRM 21.4.6, Refund Offset.
Tentative Carryback Cases - See IRM 21.5.9.5.8, Carryback Manual Refund.
Deceased taxpayers - See IRM 21.6.6.2.21.2, Processing Decedent Account Refunds.
Reimbursement of return photocopy fees - See IRM 21.4.4.7.1, Photocopy Fee Refunds.
Chargeback for unauthorized credit card payments - See IRM 21.4.4.7.2, Credit Card Chargebacks.
Taxpayers in bankruptcy
Non-receipt of direct deposit refunds due to IRS error - See IRM 21.4.1.5.7.6, Non-Receipt of Direct Deposited Refunds - "Refund Inquiry Employees."
To release an X- freeze - See IRM 21.5.6.4.47, X- Freeze.
Refund consists of Chapter Three Withholding (CTW) and non-CTW.
Refunds issued after the RSED has expired (prevention of RSED-STAT Transcript generating to the Statute Team) - See IRM 21.5.3.4.3, Tax Decrease and Statute Consideration, and IRM 25.6.1.10.3.3.2, Limitations on the Amount of a Claim.
On IMF Modules, CC TXMOD should also be reviewed for a pending or posted Transaction Code (TC) 400 which identifies that the module has systemically overflowed from IMF to Non-Master File (NMF). Once the TC 400 is present on the IMF module, all subsequent transactions MUST be processed through NMF in Kansas City Accounting. Do not initiate a Manual Refund through normal processing but instead reach out to Cincinnati Accounts Management NMF for assistance.
Overpayments of less than $1 are systemically cleared from the module by the posting of a TC 386. If a taxpayer requests a refund of an overpayment of less than $1.00, use the following procedures to reverse the TC 386 and force the generation of a systemic refund:
Input a TC 971 action code (AC) 652 using CC REQ77. Refer to IRM 2.4.19, Command Codes REQ77, REM77, and FRM7A.
Enter the transaction date of the TC 386 on line 3, positions 56 - 63, <TRANS-DT>.
The above actions will post a TC 387, reversing the TC 386, and will generate a systemic refund (TC 846) via a paper check to the address of record.
If the module does not contain a posted TC 386 with a matching transaction date, the TC 971 AC 652 will unpost showing unpostable code (UPC) 438 RC 5.
Thorough IDRS research must be completed before submitting a manual refund request to the Accounting Function. IDRS research is not required if the refund is being prepared for the Bureau of Fiscal Service.
This subsection details the research needed for all other manual refunds.
Failure to perform the necessary IDRS research, or to provide back-up documentation when the manual refund is submitted to the Accounting Function, will result in the manual refund request being rejected back to the initiator.
Before initiating a manual refund, verify that the Refund Statute Expiration Date (RSED) has not expired.
The RSED for prepaid credit must be checked for limitations on the amount claimed. If the claim was filed within three years of the filing of the return, the amount to be credited or refunded is limited to the tax paid (which includes tax, penalties, and interest) during the three years immediately preceding the filing of the claim, plus the period of any extension of time to file. See IRM 25.6.1.10.3.3.2.1, Three-year Rule, for additional information.
If a return is not filed or the claim was not filed within three years of the return, the amount is limited to the portion of tax paid (the payment of tax could be for tax, penalty or interest) during the two years immediately preceding the filing of the claim. See IRM 25.6.1.10.3.3.2.2, Two-year Rule, for additional information.
Note:
If the RSED is expired, a notation must be included in the Remarks section of the manual refund Form 3753/Form 5792 to indicate there is no Refund Statute issue and the credit is available for refund. Notations must be clear and can include “Timely filed, No RSED Issue” or “RSED allowable”. Before initiating the manual refund, credit availability must be determined. See IRM 21.4.4.5.1 (3) Block 20 and IRM 21.4.4.5.2 (9) Section IV - Other Remarks.
Questionable RSED issues must be referred to the Statute Coordinator in your area.
Verify the taxpayer has no outstanding tax liabilities that must be satisfied. Refer to IRM 5.19.10.3.13(2), Research Prior to Transfer of Credits. Generally, all debit balances must be satisfied before issuing a manual refund if the assessed balance is ≡ ≡ ≡ ≡ ≡ or more and/or accruals are ≡ ≡ ≡ ≡ ≡ or more. When an outstanding tax debt is identified, a manual refund can only be issued for the amount of overpayment in excess of the balance due.
For procedures on transferring credit to balance due accounts refer to IRM 21.5.8, Credit Transfers. For procedures on processing an original return with an offset bypass refund, see IRM 21.4.6.5.7.1, Offset Bypass Refund (OBR).On an IMF account, if a credit transfer and a manual refund are required on the same module:
First, input the credit transfer using a TC 570 on the debit portion of the transfer to prevent a refund or offset of any remaining credit after the transfer. Refer to IRM 21.5.8.4.5(3), TC 570 and Bypass Indicator. Calculate the balance due to the date the credit became available and use that date as the credit transfer date.
Then, input the manual refund.
Caution:
If the credit transfer posts at the same time as the manual refund, without a TC 570 on the debit portion of the transfer, the credit transfer will release the hold on the account and will allow a systemic refund to issue before the manual refund posts. This will create an erroneous refund.
Initiators must review the account using IDRS research to ensure there are no prior, duplicate, manual (TC 840) or computer-generated (TC 846) refunds issued for the credit being refunded.
Caution:
A TC 971 AC 664 indicates a Form 3753, Manual Refund Posting Voucher, has been processed by the Accounting Function and a TC 840 will post to the account within 4 to 6 weeks. Do not input a second manual refund for the same overpayment. Refer to IRM 21.4.4.5.2, Preparation of Form 3753, Manual Refund Posting Voucher.
Research all related accounts, using appropriate command codes, the same day a manual refund is prepared to verify that a duplicate refund will not be issued.Verify that the claimed credits (payments) are available for refund and mark box 7 in section II of Form 5792, Request for IDRS Generated Refund, indicating the credit is available to be refunded. Research for any open control bases and coordinate, as necessary.
Note:
Before completing a manual refund, be sure to check the account for a TC 971 AC 665 (indicates a manual assessment has been made). This could reduce the amount of overpayment available for refund. For more information, see IRM 3.17.244, Manual Assessments.
The first two digits of the employee IDRS number (Office Identifiers) will identify the employee's location:Office Identifiers Campus 01 Brookhaven 02 Cincinnati 03 Memphis 04 Ogden 05 Philadelphia 06 Austin 07 Atlanta 08 Andover 09 Kansas City 10 Fresno 11 Identity Theft Victim Assistance (IDTVA) 35 Puerto Rico 63 Taxpayer Advocate Service All records of accounts must be researched including:
Individual Master File (IMF)
Business Master File (BMF)
Non-Master File (NMF)
Research is needed to identify any outstanding balances on Non-Master File. Refer to IRM 21.2.1.5, Non-Masterfile. Indicators of Non-Master File account activity include the presence of an M- Freeze on an account, or a TC 130 on CC ENMOD. Non-Master File accounts present on IDRS can be identified using CC TXMOD, CC ENMOD, and CC SUMRY with the definer "N" after the taxpayer identification number (TIN). When the indicator is present, the initiator of the manual refund must contact the Non-Master File Function to request a transcript of all open NMF accounts. NMF accounts are centralized in Kansas City Submission Processing.
Consider any outstanding balances or prior TC 840 when determining the amount of the manual refund which can be initiated. The refund amount could be reduced or not approved if there are NMF debts.
If research indicates the taxpayer is eligible for all or a portion of the refund, attach the NMF transcript to Form 3753, with an explanation of why the taxpayer qualifies for the full or reduced amount of the refund.
The Bureau of the Fiscal Service (BFS) (formerly Financial Management Service (FMS)) issues IRS refunds and maintains the Treasury Offset Program (TOP) for child support, non-tax federal agency debts, state income tax offsets and unemployment compensation debts. See IRM 21.4.6.4.2.2, IMF TOP Offset, and IRM 21.4.6.4.2.3, BMF and Civil Penalty TOP Offsets, for types of refunds eligible for offset.
If the manual refund is eligible for TOP offset, initiators of manual refunds must inform taxpayers they are still subject to TOP offsets by BFS (formerly FMS).
The Bypass indicator can be used with Form 5792 to prevent a TOP offset in limited circumstances. Refer to IRM 21.4.6, Refund Offset, for more information.
Only bypass indicators 0 or 3 can be used with Form 3753. See IRM 21.4.4.5.2, Preparation of Form 3753, Manual Refund Posting Voucher.
Certain conditions on a module require coordination with other areas before a manual refund can be requested. All information received from these areas must be a part of your manual refund case documentation.
Obtain approval from the Criminal Investigation Scheme Development Center when an account shows no filing requirements.
Approval must be requested from the Technical Unit on large corporation (LCI) accounts.
An M- freeze indicates a Non-Master File freeze. See IRM 21.4.4.4.3, Non-Master File Research.
-Z or Z- freeze must be coordinated with Criminal Investigation Scheme Development Center.
-U Freeze must be coordinated with the Erroneous Refund team in Accounting.
-V bankruptcy freeze. See IRM 21.5.6.4.44, -V Freeze.
-W litigation freeze. See IRM 21.5.6.4.46, -W Freeze, and IRM 25.3.8, TC 520 -W Freeze Servicewide Guide.
-R Refund Hold freeze. A Refund Hold -R freeze can be identified by TC 570 with 999 in the Julian Date field of the Document Locator Number (DLN) (digits 6, 7, and 8). Refund Hold coordinators can be found on the Servicewide Electronic Research Program (SERP) at REFUND HOLD COORDINATORS Delinquent.
Obtain a credit verification print from Rejects/Error Resolution for unprocessed returns.
Obtain approval from RICS if there are any of the following:
“WARNING - POTENTIAL FRAUDULENT PAYER TIN" or "WARNING - POTENTIAL FRAUDULENT SUBMISSION” on CC IRPTR from the income and withholding claimed on the return.
POTENTIAL FAB EIN is in the Sort Name Line for the business EIN from the income and withholding claim on the return.
TC 971 AC 524 with the literal EINFAB or EINFB2 on the EIN account from the income and withholding claim on the return.
Open IDRS control with activity: BKL, BKLD, BKLDCHK or BKLDACHREV, TC 841 is posted with a blocking series 77711/77712/77713/77714, or a reversal Office of Child Support (OCSE) TOP Offset (TC 898 showing Agency Code 01 or 02) with a TC 971 AC 134 literal “BKLD OFFSET”.
TC 971/199 indicating RICS involvement. Refer to IRM 25.25.5-2, Transaction Code (TC) 971 Action Code (AC) 199 Miscellaneous (MISC) Field Literals for RIVO.
Examination approval is required for the following account conditions:
Computer Condition Code (CCC) "X" for Form 1120, U.S. Corporation Income Tax Return, with a Tax Shelter Activity Code
Audit Information Management System (AIMS) indicator on the account with AIMS-CD "1" , "3" , or "5"
An AIMS SC is present on CC BMFOL
-E Freeze with TC 810 (with Code 1, 2, 3 or 4). See IRM 21.5.10.3.1, Integrated Data Retrieval System (IDRS) Research Exam Issues, and IRM 21.5.10.4.1.2, Compliance Refund Hold Projects
-L Freeze and the account has a history item or activity code of "MAAS (MMDDYYYY)" . This indicates a quick assessment has been requested and that a new liability is in the process of posting. If the assessment has not posted, contact Exam for the additional liability and satisfy the liability prior to issuing the manual refund
-L Freeze if AIMS Status Code is other than 00 through 06 or 08
Manual refund is exception processing and has a greater margin for error. When possible, allow the system to generate the TC 846 refund. Releasing a hold on the account could result in a quicker refund to the taxpayer than issuing a manual refund.
Do not issue a manual refund if:Caution:
Before issuing a manual refund on a decedent account with a -X freeze, see IRM 21.5.6.4.48, -X Freeze, for updated procedures that may include inputting a TC 971 AC 807 to release the freeze and generate a systemic refund.
A generated refund will be released within two (2) cycles, except under conditions outlined in IRM 21.4.4.3, Why Would a Manual Refund Be Needed?
There is a TC 971 AC 664 on the account, either AP, PN or posted. The presence of a TC 971 AC 664 indicates that a Form 3753 is in process. The processing of Form 3753 may take up to four (4) weeks for the TC 840 to post. However, the actual refund check is mailed within 2-3 days of initiating and certifying the manual refund.
Note:
If discovered that a TC 846 has posted prior to the TC 840, the discoverer must do one of the following:
a) Contact the Manual Refund function at the Submission Processing Center. Determine whether the manual refund can be stopped.
b) Input CC NOREF to stop the generated (TC 846) refund. Valid for BMF tax accounts only.
c) Contact the Notice Review function in the appropriate Submission Processing Center to stop the refund.The taxpayer indicated a direct deposit refund
In addition, extreme caution must be used when initiating manual refunds during a BMF accelerated cycle (generally occurs during the end of May, September and October).Caution:
Per the Protecting Americans from Tax Hikes Act of 2015 (the PATH Act), section 201(b) which is codified at IRC 6402(m), current calendar year refunds cannot be issued prior to February 15th if certain credits are claimed. A C- Freeze will be established on these accounts to hold the refunds and cannot be released by the posting of a TC 29X. Manual refunds cannot be issued on these accounts prior to February 15th. See IRM 21.5.6.4.5.1, C- Freeze Refund Holds, for further information. For fiscal year filers, a manual refund cannot be issued prior to the 15th day of the second month following the close of the taxable year.
If a TERUP is input on a manual refund, the reinput of the manual refund must be done after the DQ shows. DO NOT reinput the manual refund on the same day as the TERUP is input.
All offices requesting manual refunds must have Form 14031 , Manual Refund Signature Authorization, with authorized digital signatures on file with the Submission Processing (SP) Accounting Branch that processes the manual refund.
Annually, employees authorized to approve manual refunds, effective January 1, must submit Form 14031, Manual Refund Signature Form, to SP Accounting.
No later than November 30 of each year, the Submission Processing (SP) Accounting site sends an email to each Business Operating Division (BOD) Head of Office requesting resubmission of new Forms 14031 for all authorized manual refund signers.
After receiving the request, each BOD Head of Office must send one consolidated email to SP Accounting containing all Forms 14031 signed by that Head of Office no later than the second Friday in December. See Exhibit 21.4.4-4, Accounting Function - Manual Refund Team Contact Information, for the appropriate email addresses.
Procedures for completing Form 14031 are provided in IRM 3.17.79.3.5, Employees Authorized to Sign Requests for Refunds. Information about the annual Form 14031 resubmission process is provided in IRM 3.17.79.3.5.3, Annual Processing Requirements for Form 14031, Manual Refund Signature Form.
Form 3753 and Form 5792 are posting documents used by Accounting to schedule and certify refunds. Accounting will reject any request that:
Is not legible, contains a strikethrough, white out, or has corrections or alterations reflected on Form 3753/Form 5792 after it was digitally signed.
Does not have the appropriate hold codes or posting delay codes as applicable.
Is prepared on an obsolete form.
Does not have back-up documentation attached.
Has a missing, incorrect, or incomplete authorized digital approved signature (The “SEID” digital signature format is required on Form 3753 and Form 5792.) A SEID always ends with the letter “B” and does not contain any vowels.
Is missing required RSED statute notations for credit availability. See IRM 21.4.4.5.1 (3) Block 20 and IRM 21.4.4.5.2 (9) Section IV - Other Remarks.
Is not received in Accounting by the designated cut-off time.
When an adjustment is input and a manual refund is being issued, a hold code (HC) 1, 2, or 4 must be input with the adjustment. If HCs are not input by the initiator, the Accounting Function will reject the request back to the initiator. Do not use HC 0 or 3 when inputting a credit adjustment and issuing a manual refund. HC 0 and 3 will not hold the credit and will allow a systemic refund or offset to generate.
If a credit transfer to satisfy an outstanding balance (OBL) is also required, in addition to the instructions in (3) above, a TC 570 must be input on the debit side of the credit transfer (the side the money is being moved from, and from which the manual refund is being issued). If a TC 570 is not input with the credit transfer to establish a -R freeze, the credit transfer will release the -K freeze (established by using HC 1, 2 or 4 on the adjustment) and a systemic refund (TC 846) will be generated.
Processing Form 5792, Request for IDRS Generated Refund (IGR), requires the following actions:
Prepare the manual refund document using the Integrated Automation Technology (IAT) Manual Refund Tool. Refer to IRM 21.4.4.5.1, Preparation of Form 5792, IDRS Generated Refund. Use of the IAT Manual Refund Tool is mandatory per IRM 21.2.2-2, Accounts Management Mandated IAT Tools.
If a duplicate condition is found, the IAT Manual Refund Tool will not complete the form. You must resolve the duplicate condition before the tool will allow the completion of the form. Be sure to check CFOL command codes to ensure a refund has not generated. The Manager who conducted the review MUST complete the Prevention of Duplicate Manual Erroneous Refund (DMER) Manager Certification. This form MUST be completed anytime the manual refund originator bypasses the Possible Duplicate Refund Indicator box in the IAT Manual Refund Suite Tool. This MUST be attached to the back-up documentation of the email portion of the manual refund request. If it is not attached, the manual refund can be rejected.
Reminder:
Do not input the manual refund until the duplicate condition is resolved. Below is a chart with possible conditions. This list is not all inclusive.
Row If the following condition is found: Then try to prevent the duplicate refund by: 1 A TC 846 for the same overpayment (search IMFOLT or BMFOLT and TXMODA) Initiate CC NOREF
Initiate erroneous refund procedures
2 A pending TC 29X, TC 30X or TC 24X with either no hold code or a hold code 3 or 5 Initiate CC NOREF
Contact manual refund or adjustment initiator for possible CC TERUP/QR delete within required timeframe
3 A pending or posted credit transfer (Identified by a DLN with a Doc Code of 24, 34, or 48) without a TC 570 Initiate CC NOREF
Contact manual refund or adjustment initiator for possible CC TERUP/QR delete within required timeframe
4 A pending or posted credit transfer (Identified by a DLN with a Doc Code of 24, 34, or 48) with a TC 571 pending or posted after the TC 570 Initiate CC NOREF
Contact manual refund or adjustment initiator for possible CC TERUP/QR delete within required timeframe
5 A TC 150 that posts after the manual refund is initiated but before the TC 840 posts Initiate CC NOREF
Contact manual refund or adjustment initiator for possible CC TERUP/QR delete within required timeframe
6 An AP or PN TC 521 or TC 522 with no Closing Code Contact CIO for Clarification
Initiate CC NOREF
7 An AP or PN TC 521 or TC 522 with a Closing Code of 60, 61, 64, 65, 83, 84, 85, 86, or 89 with no other pending or posted unreversed TC 520 with a Closing Code of 62, 63, 66, 67, or 81. Contact CIO for Clarification
Initiate CC NOREF
8 An AP or PN TC 521 or TC 522 with a Closing Code 62, 63, 66, 67, or 81 with no other pending or posted unreversed TC 520 with closing code 62, 63, 66, 67 or 81 Contact CIO for Clarification
Initiate CC NOREF
9 A TC 972 AC 134 with a direct deposit indicator on the posted return Initiate CC NOREF if possible
Initiate erroneous refund procedures
10 A pending or posted TC 971 AC 850 with a direct deposit indicator (DD9) on the TC 846 Initiate CC NOREF if possible
Initiate erroneous refund procedures
11 A TC 150 or TC 29x with a DLN Blocking Series of 92XXX and a future date TC846 on I/BMFOLT Initiate erroneous refund procedures 12 A TC 290 with CRN 808, 809, 810, or 811 Contact TC 290 initiator for CC TERUP within required timeframe
Initiate CC NOREF
13 A pending TC 013 Name change in progress, contact manual refund initiator to clarify 14 A pending TC 014 Contact TC 014 initiator for CC TERUP within required timeframe
Initiate CC NOREF
15 A pending TC 018 Contact TC 018 initiator for CC TERUP within required timeframe
Initiate CC NOREF
16 A TC 131 Contact TC 131 initiator for CC TERUP within required timeframe
Initiate CC NOREF
Forward the manual refund form to the designated individual for first review, according to the routing instructions for your site (routing instructions will vary by site), and attach necessary documentation. Refer to (10) below for a list of necessary documentation and the checklist in Exhibit 21.4.4-3, Manual Refund Checklists. After review, the designated individual will forward to technical lead for second review according to the routing instructions for your site.
The technical lead must complete second review of the manual refund form, the attached documentation, and, using the IAT Manual Refund Suite Tool, review information on IDRS. The technical lead must confirm that a manual refund is required and verify the IRM reference requiring the manual refund.
The technical lead will send the manual refund documentation forward to the manager to be reviewed and digitally signed, according to the routing instructions for your site (routing instructions will vary by site).
The initiating employee or designated individual will input a CC NOREF with definer "P" on each IMF manual refund to prevent the issuance of a systemic refund. Refer to IRM 21.4.1.5.10, Refund Intercept CC NOREF with Definer "P" , for instructions to complete the CC NOREF with definer "P" .
Exception:
If the manual refund is being issued from a module currently indicating a -V or -W freeze or contains an open TC 520 (open bankruptcy case), CC NOREF with definer "P" is not required. When the IAT error message referenced in paragraph "h" below is displayed, select the "Retry" button to bypass the IAT error message.
Exception:
If the manual refund is being issued from a module currently in a balance due status (before the manual refund is input), CC NOREF with definer "P" is not required. When the IAT error message referenced in paragraph "h" below is displayed, select the "Retry" button to bypass the IAT error message.
Note:
There are some extremely limited circumstances when a manual refund and a systemic refund are required on a module, such as some Injured Spouse claims. If a manual refund and a systemic refund are required, do not input CC NOREF with definer "P" . Select the "Retry" button to bypass the IAT error message.
Refer to Exhibit 2.4.37-7, Input Format Command Code NOREFP for the line-by-line instructions for inputting CC NOREF with definer "P" .
Note:
Use the current cycle or, if a posting delay code is used on an adjustment, use the cycle the adjustment will post. An "F" must be entered after the cycle and either "MISC" or "RFDL" must be used as the category code.
Exception:
If a manual refund has been input using the IAT Manual Refund Suite tool, the CC NOREF should indicate category code MISC, and the control base may be closed immediately following CC NOREF input. Information for updating the control categories in the IAT Stop Refund (NOREF) tool can be found in section 4 of the IAT tool job aid, IAT Taxpayer Services: AM/CAS Tool Instructions
If CC NOREF is not detected by the IAT Manual Refund Tool an error message will appear in the IAT tool indicating "Input CC NOREFP, following your area guidelines for input, before initiating CC RFUNDR" .
The manual refund documentation will be returned to the initiating employee or designated individual, according to the routing instructions for your site (routing instructions will vary by site) for the input of CC RFUND through the IAT Manual Refund Tool. Refer to IRM 21.4.4.5.1.1, IDRS Generated Refund CC "RFUND" .
Note:
If inputting CC RFUND between the hours of 6:00 PM, at the Accounting site where your manual refunds are processed, and before 11:59 PM your local time, notate a "Y" in Section IV Box 1 of Form 5792 along with the number of the employee inputting the CC RFUND. This will alert Accounting that the CC RFUND will have a different date than CC REFAP, but the two command codes were input during the same 24-hour cycle.
Input of CC RFUND through the IAT Manual Refund Tool will update the open control on IDRS using Status Code A and "IDRSREFUND" as the activity code.
A copy of Form 5792or a CC RFUND completed screen or a screen capture of CC RFUND is to be attached/kept with the CII case. If the manual refund is rejected for any reason and Form 5792 is changed or CC RFUND is input for a second time, a new copy of Form 5792 or a CC RFUND completed screen or a screen capture of CC RFUND is to be attached/kept with the CII case.
All manual refund documents will be returned to the technical lead or designated individual after CC RFUND has been input, according to the routing instructions for your site (routing instructions will vary by site).
Initiating sites are responsible to ensure manual refunds submitted have been accepted by Accounting. Any manual refunds rejected are to be re-input or rebutted within five business days of Form 15276 being received. Effective June 20, 2023, initiating sites are no longer required to complete the monitoring of their manual refunds as Headquarters will be monitoring the cases daily.
Note:
To ensure manual refunds have been accepted by Accounting, load the previous days EMT exports from your C: drive into your EMT/Case Monitoring Tool. Then run the Monitor function on the EMT/Case Monitoring Tool and act on any cases that are archived as “DQ”. Any cases that are not archived as “DQ” can be deleted from the EMT tool. Cases that are archived as “DQ” are required to be reviewed, corrected and re-input within five business days.
After items (a) through (m) above have been addressed, forward the completed manual refunds with all back-up documents, according to the routing instructions for your site (routing instructions will vary by site) to the appropriate campus Accounting Function by their designated daily cutoff time.
When emailing manual refunds to the Accounting Function, the email will consist of two attachments. The first attachment will be the Form 5792 and the second attachment will be the back-up documentation. There can be no other documents attached to the Form 5792 attachment. The back-up documentation must all be merged into one PDF file per refund. Multiple manual refunds can be included in the same email. Each document must be saved using the required naming convention. The required naming convention and examples are shown in (9) below. When sending more than three manual refund requests in the same email, they must be in a Zip File. No email can contain more than 25 manual refund requests. Also, the manual refund form number must be the first item on the email subject line. This is so Form 3753 can be identified and given priority. The remaining subject line does not need to be structured. The email must be encrypted but not password protected.
Refer to Document 12990, Records Control Schedules (RCS) 29, Item 266(3) for the disposition authorization of Form 5792, Request for IDRS Generated Refund (IGR). Form 5792 is a record, and it must be handled according to the National Archives and Records Administration (NARA) authorized disposition. Records will only be destroyed in accordance with authorized instructions found in the IRS Records Control Schedules (RCS).
Processing Form 3753, Manual Refund Posting Voucher:
Prepare the manual refund document using the IAT Manual Refund Suite tool. Refer to IRM 21.4.4.5.2, Preparation of Form 3753, Manual Refund Posting Voucher. Use of the IAT CRS tool is mandatory per IRM 21.2.2-2, Accounts Management Mandated IAT Tools.
If a duplicate condition is found, the IAT Manual Refund tool will not complete the form. You must resolve the duplicate condition before the tool will allow the completion of the form. The manager who conducted the review MUST complete the form Prevention of Duplicate Manual Erroneous Refund (DMER) Manager Certification. This form MUST be completed anytime the manual refund originator bypasses the Possible Duplicate Refund Indicator box in the IAT Manual Refund Suite Tool. This MUST be attached to the back-up documentation of the email portion of the manual refund request. If it is not attached, the manual refund can be rejected.
Reminder:
Do not input the manual refund until the duplicate condition is resolved. Below is a chart with possible conditions. This list is not all inclusive.
Row If the following condition is found: Then try to prevent the duplicate refund by: 1 A TC 846 for the same overpayment (search IMFOLT or BMFOLT and TXMODA) Initiate CC NOREF
Initiate erroneous refund procedures
2 A pending TC 29X, TC 30X or TC 24X with either no hold code or a hold code 3 or 5 Initiate CC NOREF
Contact manual refund or adjustment initiator for possible CC TERUP/QR delete within required timeframe
3 A pending or posted credit transfer (Identified by a DLN with a Doc Code of 24, 34, or 48) without a TC 570 Initiate CC NOREF
Contact manual refund or adjustment initiator for possible CC TERUP/QR delete within required timeframe
4 A pending or posted credit transfer (Identified by a DLN with a Doc Code of 24, 34, or 48) with a TC 571 pending or posted after the TC 570 Initiate CC NOREF
Contact manual refund or adjustment initiator for possible CC TERUP/QR delete within required timeframe
5 A TC 150 that posts after the manual refund is initiated but before the TC 840 posts Initiate CC NOREF
Contact manual refund or adjustment initiator for possible CC TERUP/QR delete within required timeframe
6 An AP or PN TC 521 or TC 522 with no Closing Code or an AP or PN TC 521 or TC 522 with no Closing Code Contact CIO for Clarification
Initiate CC NOREF
7 An AP or PN TC 521 or TC 522 with a Closing Code of 60,61, 64, 65, 83, 84, 85, 86, or 89 with no other pending or posted unreversed TC 520 with a Closing Code of 62, 63, 66, 67, or 81. Contact CIO for Clarification
Initiate CC NOREF
8 An AP or PN TC 521 or TC 522 with a Closing Code 62, 63, 66, 67, or 81 with no other pending or posted unreversed TC 520 with closing code 62, 63, 66, 67 or 81 Contact CIO for Clarification
Initiate CC NOREF
9 A TC 972 AC 134 with a direct deposit indicator on the posted return Initiate CC NOREF if possible
Initiate erroneous refund procedures
10 A pending or posted TC 971 AC 850 with a direct deposit indicator (DD9) on the TC 846 Initiate CC NOREF if possible
Initiate erroneous refund procedures
11 A TC 150 or TC 29x with a DLN Blocking Series of 92XXX and a future date TC846 on I/BMFOLT Initiate erroneous refund procedures 12 A TC 290 with CRN 808, 809, 810, or 811 Contact TC 290 initiator for CC TERUP within required timeframe
Initiate CC NOREF
13 A pending TC 013 Name change in progress, contact manual refund initiator to clarify 14 A pending TC 014 Contact TC 014 initiator for CC TERUP within required timeframe
Initiate CC NOREF
15 A pending TC 018 Contact TC 018 initiator for CC TERUP within required timeframe
Initiate CC NOREF
16 A TC 131 Contact TC 131 initiator for CC TERUP within required timeframe
Initiate CC NOREF
Forward the manual refund form to the designated individual for the first review, according to the routing instructions for your site (routing instructions will vary by site), and attach necessary documentation. Refer to (10) below for a list of necessary documentation and the checklist in Exhibit 21.4.4-3, Manual Refund Checklists. After review, the designated individual will forward to technical lead according to the routing instructions for your site.
The technical lead must complete second review the manual refund form, the attached documentation, and, using the IAT Manual Refund Suite Tool, review information on IDRS. The technical lead must confirm that a manual refund is required and verify the IRM reference requiring the manual refund.
The technical lead will then send the manual refund documentation forward to the manager to be reviewed and digitally signed.
When the Accounting Function processes Form 3753, Manual Refund Posting Voucher, they input a history item, a control base, and TC 971 AC 664 on the account.
When emailing manual refunds to the Accounting Function, the email will consist of two attachments. The first attachment will be the Form 3753 and the second attachment will be the back-up documentation. There can be no other documents attached to the Form 3753 attachment. The back-up documentation must all be merged into one PDF file per refund. Multiple manual refund requests can be included in the same email. Each document must be saved with the required naming convention. The required naming convention and examples are in (9) below. When sending more than three manual refund requests in the same email, they must be in a Zip File. No email can contain more than 25 manual refund requests. Also, the manual refund form number must be the first item on the email subject line. This is so Form 3753 can be identified and given priority. The remaining subject line does not need to be structured. The email must be encrypted but not password protected.
Note:
When emailing the manual refund request to Accounting, only send to the Accounting mailbox. To eliminate the possibility of a duplicate refund, do not cc anyone else in Accounting.
Refer to Document 12990, Records Control Schedules (RCS) 29, Item 168(4) for the disposition authorization of Form 3753, Manual Refund Posting Voucher. Form 3753 is a record and it must be handled according to the National Archives and Records Administration (NARA) authorized disposition. Records will only be destroyed in accordance with authorized instructions found in the IRS Records Control Schedules (RCS).
Form 5792 or Form 3753 attachment must be named using the following naming convention: Name Control, Last 4 digits of the TIN, Tax Period 5792/3753 (depending on the form attached). The attachment with the back-up documentation must be named using the Name Control, Last 4 digits of TIN, Tax Period and the literal Doc at the end (this would be all the back-up documentation attachment). Examples are:
Type of Attachment Naming Convention Form 5792 MOUS 1234 201712 5792.pdf Form 3753 MOUS 1234 201712 3753.pdf Back-Up Documentation MOUS 1234 201712 Doc.pdf If Multiple Manual Refunds for the Same TIN and Tax Period Naming Convention Form 5792 MOUS 1234 201812 5792.pdf
MOUS 1234 201812 5792_1.pdf
MOUS 1234 201812 5792_2.pdf
Form 3753 MOUS 1234 201812 3753.pdf
MOUS 1234 201812 3753_1.pdf
MOUS 1234 201812 3753_2.pdfBack-Up Documentation MOUS 1234 201712 Doc.pdf
MOUS 1234 201812 5792 Doc_1.pdf
MOUS 1234 201812 5792 Doc_2.pdfThe following information must be attached to the manual refund form:
Sufficient documentation to justify issuing the manual refund (for example: taxpayer correspondence, internal transcript, copy of Form 1040X, Form 1045, Form 4442, Form 8379, the injured spouse worksheet if applicable, Form 1310 (unless a Surviving spouse), Form 843, the taxpayer's hardship documentation or a signed statement from the Local Taxpayer Advocate (LTA) approving the taxpayer's hardship refund request, etc.)
Note:
The documentation attached to the manual refund should not be original documents. Original documents are to be maintained with the original case file.
Note:
A missing, incomplete or incorrect tax year at the top of the Form 1310 may be perfected, if all other elements are completed and the form has a valid signature. Forms 1310 located in MeF or EUP are tax-year specific and may only be used for the tax year shown on the form. A Form 1310 found for a different tax year may not be used to support the current case unless it was submitted as a reply to IRS correspondence for the tax year being worked.
CC COMPA or Automated Computation Tool (ACT)/Decision Modeling Inc. (DMI) Report 490 (if interest was calculated). The COMPA printout must include COMPA at the top and not be handwritten in.
CC ENMOD (only if a pending name or address change is indicated)
Generally, unless required by the IRM of the specific type of manual refund being input, no other IDRS prints are needed to be attached as the Accounting Functions have access to IDRS and can verify the information.
If the original return was coded with CCC 3, was a U coded return (Form 1040), or Computer Condition Code X (Form 1120) is present on IDRS, indicating the original return was unprocessable due to the taxpayer not responding to Error Resolution correspondence, the RPD must be entered in the remarks, and a completed REQ54 screen print showing the RPD must be attached as backup documentation to the manual refund.
If a previous adjustment was input to the module with an RPD, a copy of the REQ54 screen is not required because the RPD appears on CC IMFOLR/BMFOLR. For more information see IRM 21.2.4.3.40.1, Computer Condition Code (CCC) 3 or U-Coded Returns.
Form 5792 is used with CC RFUND to request an IDRS refund. This form cannot be used to issue refunds of $100 Million or more. Use the latest revision of Form 5792. Digital signatures are required on Form 5792. When a Form 5792 is submitted to the Accounting Function, only one copy of Form 5792 is required. The case file must be submitted to the Accounting Function the same processing day CC RFUND is input.
It is imperative that the following entries on Form 5792, Section 1 are legible to validate CC RFUND with CC REFAP to post the TC 840:
See IRM 3.17.79.4.2, RFUND/REFAP Mismatch.Box 6: TC 840 Amount
Box 14: First Name Line
Box 18: Street Address or PO Number
Box 19: City
The following are line by line instructions for completing Form 5792 Section I - Account Information (All fields are mandatory unless noted otherwise):
Block 1, TIN and File Source - Input the TIN and File Source of the account from which the refund will be issued
Block 2, MFT Code - Input the Master File Tax (MFT) Code
Block 3, Tax Period - Input the tax period as YYYYMM
Block 4, Plan Number - Input the plan/report number, applicable for MFT 46, 74, and 76
Block 5, Name Control - Input the four-character name control
Block 6, TC 840 Amount - Input the TC 840 amount (overpayment, plus allowable interest)
Block 7, TC 770 Amount - Input the TC 770 amount (allowable interest). If no interest is being computed, enter "0" or ".00"
Block 8, Overpayment Amount - Input the overpayment amount: The amount being refunded not including any available credit interest
Note:
Consider previously assessed failure to file and failure to pay penalties, and debit interest that will be affected by the adjustment action. Any decrease in penalties or interest already paid must be included in the overpayment amount. In addition, unassessed accruals of penalty and/or interest could reduce the overpayment amount.
Block 9, Line No - Input the appropriate line number. See Exhibit 2.4.20-12, Description of Line Item Numbers
Block 10, Interest Indicator - Input the appropriate interest indicator code:
"0" (zero) for no interest
"N" for normal interest when interest is payable
"R" for restricted interestBlock 11, ULC Code - Input the Universal Location Code (ULC) (formerly the District Office code). (This block will generate when CC RFUND is input to IDRS) See Document 6209, Section 8C. 10, for listing of ULCs
Block 12, Sequence Number - Will be input by the employee inputting CC RFUND to IDRS. If issuing multiple manual refunds, use sequential numbers for each manual refund. Each manual refund must have its own sequence number.
Block 13, Block Series Number - Optional. Input if applicable. The block series may be 3, 4, 5, 6 or 9 and identifies why the refund is being issued. A 9 entered in this block must be accompanied by a bypass indicator (BPI) code of 1, 2, 5, 6, 8, or 9
Block 14–19, Entity and Address Information - Input the name and address of the payee. Use CC ENMOD or CC INOLES information unless there is a name change, different address, or the refund is being issued to an injured spouse or third party
Note:
If the address on anyForm 5792 does not match the address on Master File, an explanation must be provided in the Remarks section of the form.
Reminder:
If there are circumstances or discrepancies with the name or address on Form 5792, include a brief explanation in the Remarks section to support the name line or address used on the form (for example, a name line typo on back-up documentation or an address discrepancy)
Caution:
Valid characters for the first name line are A-Z, 0-9, -, &, and blank. Valid characters for the second name line are A-Z, 0-9, -, &, %, and blank. The valid characters for the address are A-Z, 0-9, -, /, and blank. For a further explanation of the valid characters accepted for CC RFUND and for an example of how to input a foreign address into CC RFUND, refer to IRM 2.4.20-4, Input Format, CC RFUND.
Deceased Taxpayer Manual Refunds: For decedent accounts, DO NOT address the first name line to a deceased taxpayer. Use the name of the person claiming the refund as the payee for refunds issued on decedent accounts. Refer to IRM 21.6.6.2.21.2, Processing Decedent Account Refunds, to determine the proper documentation for claiming a refund on a decedent account. The deceased taxpayer's name is shown on the second name line. The "DECD" in the second name line will be entered after the given name of the deceased taxpayer on a joint account or after the surname of the taxpayer on an individual account.Caution:
Before issuing a manual refund on a decedent account with a -X freeze, see IRM 21.5.6.4.48(1)(c), -X Freeze, for updated procedures that may include inputting a TC 971 AC 807 to release the freeze and generate a systemic refund.
Example:
Person claiming the refund is: 1st name line 2nd name line Surviving spouse Mary Beagle John DECD and Mary Beagle An Individual Court Appointed or Personal Representative James White (A TITLE IS NOT REQUIRED. IF A TITLE IS USED IT MUST MATCH THE COURT DOCUMENTATION) Elizabeth White DECD A Business Entity Acting as Court Appointed or Personal Representative Gopher National Bank (A TITLE IS NOT REQUIRED. IF A TITLE IS USED IT MUST MATCH THE COURT DOCUMENTATION) Elizabeth White DECD Claimant Linda Rose Jack Boxer DECD Block 20, Remarks - Annotate reason for the refund in the remarks field. Be specific. Include all pertinent information. This would be anything you would want Accounting to know about the circumstance of the manual refund. Use the table below to determine the required remarks for each situation (this list is not all-inclusive).
Note:
This block allows up to 320 characters on the form however CC RFUND will only populate the first 80 characters. The CII ID does not need to be included in the first 80 characters of the remarks. The IAT MR tool attempts to avoid splitting a word in half. If the 40th character falls in the middle of a word, the tool adjusts the break point, so the word shifts to the second line instead. In effect: Line 1 contains up to 40 characters, ending at a natural word break when possible. Line 2 contains the remaining text, up to 40 characters. Any text beyond 80 total characters is not transmitted to RFUNDR. The tool formats the remarks to fit within IDRS constraints while preserving readability.
Situation Required Remarks If a form is attached as supporting documentation for the manual refund Identify the supporting form in the remarks field Carryback manual refund F1045 attached or F1139 attached Injured Spouse "F8379 attached" Deceased TP refund based on the filing of a Form 1310 "F1310 attached" A previous TC 971 AC 807 was input but did not release the refund "TC 971 AC 807 was input and the refund was not released systemically" A refund generated by IDTVA employees "IDTVA MR" in the last line of the remarks field If the original return was coded with CCC 3, was a U coded return (Form 1040), or Computer Condition Code X (Form 1120) is present on IDRS, indicating the original return was unprocessable due to the taxpayer not responding to Error Resolution correspondence The RPD must be entered in the remarks, and a completed REQ54 screen print showing the RPD must be attached as backup documentation to the manual refund
If a previous adjustment was input to the module with an RPD, a copy of the REQ54 screen is not required because the RPD appears on CC IMFOLR/BMFOLR
For more information see IRM 21.2.4.3.40.1, Computer Condition Code (CCC) 3 or U-Coded ReturnsExpired RSED Include a statement in the Remarks field that the statute issue was reviewed and the credit is available for refund. Use a clear statement, such as Timely filed, No RSED Issue or RSED allowable Refund generated by IDTVA IDTVA MR in the last line of the remarks field Field Assistance (FA) employees "TS:CARE:FA" Block 21, Initiating BOD - Check the box of the initiating Business Operating Division (BOD).
Block 22, Document Locator Number (DLN) - Input the controlling document locator number (DLN) on the module. If no return posted or not needed, write in “return not posted”
Block 23, Bankruptcy Code Case - Check the box if the account has a bankruptcy indicator.
Block 24, TC 130 - Check the box if the account contains a TC 130
The following are line by line instructions for completing Form 5792, Section II - Manual Refund Authority - The items listed below are mandatory:
Box 1c, Handbook Reference - Use the actual IRM reference for the type of case you are working; never cite IRM 21.4.4 or its subsections as the reason you are issuing a manual refund.
Box 3, IDRS and Master File Researched for Outstanding Balances and TC 130
Box 4, Check if a Debit Account Transcript is Attached(Mark ONLY if applicable)
Box 6, Necessary Back-Up Documents Attached -Once you have verified all supporting documentation is attached and complete. For example, taxpayer correspondence, internal transcript, copy of Form 1040X, Form 1045, Form 4442, Form 8379, Injured Spouse worksheet if applicable, Form 1310 (if applicable), Form 843, etc. (this list is not all-inclusive)
Box 7, Verify Refund Amount with Source Document Amount
Box 10, Bypass Indicator - Confirm the BPI has been input on the adjustment if applicable
Box 11, IAT Tool DMER Bypass - DMER Print Attached - Mark when a duplicate condition is found, and DMER form is attached. The initials of the manager who signed the DMER Bypass document must be entered when Form 5792 is created.
Box 13, All items Above completed - Verify that all applicable items in Section I - Account Information, are completed
Mark any other boxes in this section as applicable
The following are the instructions for completing Form 5792, Section III - Interest Computation Accounting will need to verify the interest dates are correct and the credit is available for refund.
The preparer must compute all interest for the TC 770 amount. For information on computing credit interest, see IRM 20.2.4.8.2, Manual Refunds.
Input the interest "From" and "To" dates and the total interest amount. The IAT Manual Refund Tool will automatically complete this section. See IRM 21.4.4.6, Other Manual Refund Requirements, for instructions about determining "To" and "From" dates and determining the date of the overpayment.
If different CC COMPA definers are being used to calculate the total interest, use only the first "From" date and the last "To" date when completing the COMPA section in the IAT Manual Refund Tool and add remarks per third note below. See IRM 2.3.29.3, Command Code COMPA, for definer definitions and when to use them.
If reissuing a returned refund, input "Original Interest" in Section I Box 20 - Remarks, if an original amount of interest will be issued.
Check the Interest Computation Attached box "Yes" and attach a copy of the CC COMPA print or ACT/DMI Report 490 indicating the applicable interest computation. If not required to calculate interest, then check the Interest Computation Attached box "No" .
Note:
A CC COMPA print is not needed when reissuing a returned refund check that was correct when originally issued.
The following are line by line Instructions for completing Form 5792, Section IV - Manual Refund Approval - The items listed below are mandatory:
Block 1, No. of Employee Inputting RFUND via IDRS - Enter the IDRS number of the employee inputting CC RFUND
Reminder:
If inputting CC RFUND between 6:00 p.m. and midnight local time notate a "Y" in Section IV Box 1 of the Form 5792 along with the number of the employee inputting the CC RFUND (Example: 1234567890 Y). This will alert Accounting that the CC RFUND will have a different date than CC REFAP, but the two command codes were input during the same 24 hour cycle.
Block 2, Request Prepared By - Enter the name of the initiator of the request
Block 2a, SEID of the Preparer - Enter the Standard Employee Identifier (SEID) of the initiator of the request
Block 3, Phone Number - Enter the manager’s phone number of the request originator. (The telephone number must either be an internal telephone number or begin with 833 followed by an extension number, not an 800 toll-free number, for the accounting function to contact the generating area if necessary).
Block 4, Approving Official - The Approving Official who digitally signs the refund must be on the Authorized Signature List maintained by the Manual Refund Unit in the Campus Accounting Function.
Note:
Digital signatures are required on Form 3753 and Form 5792. The format is SEID followed by the name of the signer. See IRM 3.17.79.3.2.3, Manual Refund Digital Signature Requirement, for digital signature requirements on Form 5792.
CC "RFUND" is used to generate the IDRS manual refund. This CC is valid for IMF, BMF, NMF, and Individual Retirement Account File (IRAF) accounts. It is limited to refunds from tax accounts and cannot be used for special Accounting Functions such as Excess Collections.
Note:
Those campus locations that no longer have an Accounting Function will input CC RFUND using CC CMODE to the campus indicated in Exhibit 21.4.4-4, Accounting Function - Manual Refund Team Contact Information. Refer to IRM 21.3.4.7.8.8.1(2), IDRS Command Codes Used for Cash Payments, for an explanation of CC CMODE. When the RFUND is complete, remember to return to your home campus.
The IDRS action is input from the information on Form 5792. The Universal Location Code (ULC) (formerly District Office Code) is displayed as "-" on the RFUND screen. In most cases the RFUND command will generate the appropriate code. Do not overlay the "-" unless prompted to do so.
CC "RFUND" allows input of refunds for International Accounts by all users. For ULC "66" , "97" or "98" , the IDRS user will be prompted to overlay with the "dump DO" code for their campus accounting site. The "dump DO" codes are Atlanta - 59, Andover - 06, Austin - 74, Brookhaven - 22, Cincinnati - 31, Fresno - 94, Kansas City - 36, Memphis - 62, Ogden - 91 and Philadelphia - 52.
The information from Form 5792, Section IV, Block 2a, must be entered in the RFUND field containing five "Rs" . This is the SEID of the originator of Form 5792.
The SEID of the Approving Official must be entered in the RFUND field containing five "Characters" .
CC "RFUND" will open an IDRS control base if the literal "C" is overlaid with an "A" , "B" or "M" . If a control base other than your own already exists in a status other than B, you will receive an error message.
The RFUND display will show pending address changes unless the address is a foreign address. In that case, the display will indicate a pending foreign address change, and you must research CC ENMOD for the correct address.
For detailed information on input of CC "RFUND" , see IRM 2.4.20, Command Codes RFUND and REFAP.
Form 3753 is designed for non-IDRS input. CC RFUND is not used for Form 3753 refunds. Use the latest revision of Form 3753.
Systemic refunds can be generated on IDRS (TC 846) for refunds under $100 million, unless a manual refund is required. Use Form 3753 to issue a manual refund when:Issuing a manual refund of $100 million or more.
A direct deposit manual refund is required. This requirement includes international taxpayers who may or may not have a U.S. bank account (see paragraph (5) for instructions on submitting the form when the refund will be deposited to a non-U.S. bank account).
Issuing a manual refund from an account that is not on IDRS.
Note:
By statute, refunds of over $2 million to an individual or $5 million to a C Corporation must undergo review by the Joint Committee on Taxation. IRC 6405(a). See IRM 4.36.4.1.1.1, Background of Joint Committee Review program and IRM 4.10.11.6.2, Joint Committee Refunds.
Due to BFS (formerly FMS) limitations, a manual refund more than $99,999,999.99 requires two or more Forms 3753.
Digital signatures are required on Form 3753. When a Form 3753 is submitted to the Accounting Function, only one copy of Form 3753, along with one copy of the back-up documentation is required. Accounting will reject Form 3753 if the document contains any alterations such as white out, strikethrough or correction tape. See IRM 3.17.79.4.1, Case Review and Command Code REFAP (Refund Approval), for additional reject reasons.
For TAS cases issuing a manual refund due to a hardship, refer to IRM 3.17.79.3.3, Issuing Hardship Refunds. Other requirements may be applicable.
For International taxpayers who do not have a U.S. bank account, and live in a country that does not accept U.S. Treasury Checks, the refund must be submitted on a Form 3753 for processing through the International Treasury Services (ITS) at the Ogden Accounting Site. Refer to IRM 3.17.79.3.10.1.2, International Payments via International Treasury Services (ITS), for more information. Additional requirements may apply.
The following are line by line instructions for completing Form 3753, Section I - Account Information (All fields are mandatory unless noted otherwise):
The DLN block is completed by the Accounting Function
Complete the "From and Return to" box with the initiator's information
Block 1, TIN - Enter TIN of the account from which the refund will be issued
Block 2, Tax Period - Enter the tax period in YYYYMM format
Block 3, MFT Code - Enter the Master File Tax (MFT) code
Block 4, Plan Number - Enter the plan/report number, applicable for MFT 46, 74 and 76
Blocks 5 and 6, Schedule Number and Transaction Date - Will be completed by the Manual Refund Unit
Block 7, Name and Address, enter name and address of taxpayer as shown on Master File
Note:
For decedent accounts, enter the deceased taxpayer's name and address as shown on master file. The information of the person claiming the refund will be entered in block 11.
Block 8, Form Number - Enter the return form number
Block 9, DLN of Return - Enter the controlling DLN on the module. If no return posted or not needed, write in “return not posted”
Block 10b, Amount of Refund Check - Enter amount of check (TC 770 plus amount of overpayment)
Block 10d, Interest - Enter TC 770 with amount of allowable interest
Block 11, Make Check Payable To - Complete this block if the payee is other than the taxpayer or the refund is being issued to a different address. Differences must be explained in Section 2. If the address is the same, put in the remarks “same address”. This will be sufficient for not completing the entire block.
Note:
For decedent accounts, do not address the first name line on the check to a deceased taxpayer. Use the name of the person claiming the refund as the payee for refunds issued on decedent accounts. Refer to IRM 21.6.6.2.21.2, Processing Decedent Account Refunds, to determine the proper documentation for claiming a refund on a decedent account. The deceased taxpayer's name will be entered as the second name line. The "DECD" in the second name line will be entered after the given name of the deceased taxpayer on a joint account or after the surname of the taxpayer on an individual account.
Example:
Person claiming the refund is: 1st name line 2nd name line Surviving spouse Mary Beagle John DECD and Mary Beagle An individual Court Appointed or Personal Representative James White (A TITLE IS NOT REQUIRED. IF A TITLE IS USED, IT MUST MATCH THE COURT DOCUMENTATION) Elizabeth White, DECD A Business Entity Acting as a Court Appointed or Personal Representative Gopher National Bank (A TITLE IS NOT REQUIRED. IF A TITLE IS USED, IT MUST MATCH THE COURT DOCUMENTATION) Elizabeth White, DECD Claimant Linda Rose Jack Boxer, DECD Block 11a, Routing number enter the routing number for the bank where the taxpayer wants the direct deposit applied
Block 11b, Account number enter the account number in which the taxpayer wants the direct deposit applied
Block 11c, Account type check the box for Checking or Savings as appropriate
Block 12a, Symbol and 12b, Amount - Used only when completing Form 3753 for Credit Card Chargeback, by the Manual Refund Unit or by other IRS Offices/Agencies that require funds to be withdrawn from specific Treasury Accounts
Block 13, Overpayment Amount - Enter amount of overpayment. The amount being refunded, less allowable interest
Note:
Consider previously assessed failure to file and failure to pay penalties, and debit interest that will be affected by the adjustment action. Any decrease in penalties or interest already paid must be included in the overpayment amount. In addition, unassessed accruals of penalty and/or interest could reduce the overpayment amount.
Block 14, Universal Location Code - Enter the ULC (formerly the district Office code). See Document 6209, Section 8C. 10, for listing of ULCs
Block 15, Line Number - Input the appropriate line number. See Exhibit 2.4.20-12, Description of Line Item Numbers
The following are line by line instructions for completing Form 3753, Section II - Manual Refund Authority (All fields are mandatory unless noted otherwise):
Box 1c, Handbook Reference - Use the actual IRM reference for the type of case you are working; never cite IRM 21.4.4 or its subsections as the reason you are issuing a manual refund.
Box 3, IDRS and Master File researched for outstanding balance and TC 130
Box 4, Transcript of debit accounts attached (if applicable)
Box 5, Evidence of Credit Condition - Check at least one box
Box 6, Necessary back-up documents attached
Box 9, Interest - Check one box
Box 11, Bypass Indicator (BPI) - Enter a BPI 0 or 3. If the BPI is 3, you must verify that no debt exists and notate the following: BFS contact name, date of contact and no TOP debt. This statement must appear in the “Other Remarks” box on Form 3753. Exception: External Leads, Chargebacks, Form 8038CP and Department of Justice Cases are not subject to offset, include “Not subject to TOP offset” in the other remarks field when submitting the form.
Box 13, IAT Tool DMER Bypass - DMER Print Attached-Mark when a duplicate condition is found, and DMER form is attached. The initials of the manager who signed the DMER Bypass document must be entered.
Box 17, All items Above completed - Verify that all applicable items in Section I - Account Information, is completed.
Mark any other boxes in this section as applicable
The following are instructions for completing Form 3753, Section III - Interest Computation:
Accounting will need to verify the interest dates are correct and the credit is available for refund.The preparer must compute all interest for the TC 770 amount. See IRM 20.2.4.8.2, Manual Refunds, and IRM 20.2.4.4, Availability Dates for Overpayments, for additional information on computing credit interest.
Check the Interest Computation Attached box "Yes" and attach a copy of the CC COMPA print or ACT/DMI Report 490 indicating the applicable interest computation to the Form 3753. If not required to calculate interest, then check the Interest Computation Attached box "No" .
Note:
See IRM 21.4.4.6, Other Manual Refund Requirements, for requirements on interest computations on manual refunds of $1 million or more, and for help in selecting "To" and "From" dates and determining the date of the overpayment. Refer to IRM 20.2, Interest, for methods of computing interest.
The following are instructions for completing Form 3753, Section IV - Other Remarks (All fields are mandatory):
Annotate reason for the refund in the remarks field. Be specific. Include all pertinent information. This would be anything you would want Accounting to know about the circumstance of the manual refund. Use the table below to determine the required remarks for each situation (this list is not all-inclusive).
Check the box of the initiating Business Operating Division (BOD)
Situation Required Remarks If a form is attached as supporting documentation for the manual refund Identify the supporting form in the remarks field Carryback manual refund F1045 attached or F1139 attached Injured Spouse F8379 attached Deceased TP refund based on the filing of a Form 1310 F1310 attached A previous TC 971 AC 807 was input but did not release the refund TC 971 AC 807 was input and the refund was not released systemically If the original return was coded with CCC 3, was a U coded return (Form 1040), or Computer Condition Code X (Form 1120) is present on IDRS, indicating the original return was unprocessable due to the taxpayer not responding to Error Resolution correspondence The RPD must be entered in the remarks, and a completed REQ54 screen print showing the RPD must be attached as backup documentation to the manual refund.
If a previous adjustment was input to the module with an RPD, a copy of the REQ54 screen is not required because the RPD appears on CC IMFOLR/BMFOLR.
For more information see IRM 21.2.4.3.40.1, Computer Condition Code (CCC) 3 or U-Coded Returns.Expired RSED Include a statement in the Remarks field that the statute issue was reviewed and the credit is available for refund. Use a clear statement, such as Timely filed, No RSED Issue or RSED allowable Refund generated by IDTVA IDTVA MR in the last line of the remarks field Field Assistance (FA) employees TS:CARE:FA The following are instructions for completing Form 3753, Section V - Manual Refund Approval (All fields are mandatory):
Block 1 - The Approving Official must digitally sign using a “SEID” signature format on Form 3753. The Approving Official who digitally signs the refund must be on the Authorized Signature List maintained by the Manual Refund Unit in the Campus Accounting Function.
Blocks 2, a, 3, and 4 - Enter the name, SEID, date, and the manager's phone number of the request originator. (The telephone number must either be an internal telephone number or begin with 833 followed by an extension number, not an 800 toll-free number, for the accounting function to contact the generating area if necessary.)
Accounting will input a history item, control base and a TC 971 AC 664, when the document is processed.
When preparing Form 3753 to issue a hardship refund, see IRM 21.4.6.5.7, Hardship Manual Refunds, and IRM 21.4.6.5.7.1, Offset Bypass Refund (OBR).
Manual refund initiators must calculate any interest due to the taxpayer and include it on their Form 5792/Form 3753.
When computing interest with CC COMPA, to determine the “From” date, see the table below:
If the taxpayer Then allow interest from the later of Timely filed (i.e., return received by the original or extended due date), for additional information about determining timely filing see IRM 3.11.212.5, Determining Timely Filing, General Instructions. The return due date (determined without regard to any extension of time for filing), the payment date or return processable date (provided the RPD is after the due date), including any extensions of time for filing). Late filed (i.e., return not received by the original or extended due date) The late return received date, the payment date, or the CRD/RPD (if present). To determine the payment date, see the table below:
If the payment resulting in an overpayment is a Then the date of the overpayment is the Prepaid or timely credit, e.g., estimated tax payment, withholding, or a payment before the due date (determined without regard to any extension of time for filing) Due date of return. (Determined without regard to any extension of time for filing). Subsequent payment made after the due date (determined without regard to any extension of time for filing) Payment received date. ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ To determine the “To” date, see the table below:
If the return Then Indicates an overpayment The interest To date is the date certified by the Accounting Function for allowing the refund, which date must not precede the date of the refund check by more than 30 days.
Use the appropriate CC COMPA definer to compute credit interest for the period determined in (1) above. See the table below:
If Then Credit interest for a "Non-Corporate" taxpayer Compute using COMPA Credit interest before 1/1/95 for a "Corporate" taxpayer, regardless of the overpayment amount (See IRM 20.2.4.10, Special Overpayment Interest Rules for Corporations, for the definition of a "Corporate" taxpayer.) Compute using COMPAC Credit interest on or after 1/1/95 for a "Corporate" taxpayer and the overpayment amount is less than or equal to $10,000 Compute using COMPAC Credit interest after 12/31/94 for a "Corporate" taxpayer and the overpayment amount is greater than $10,000, or the GATT threshold has previously been met (See IRM 20.2.4.10.2, Determining the GATT Threshold.) Compute using COMPAG (GATT). Any function initiating a manual refund for $1 million or more that contains credit interest, is required to perform an additional review (to be determined by that function) to verify the accuracy of the interest, and to identify and correct any errors.
Manual refunds of $1 million or more, initiated by Accounts Management employees, and containing credit interest, are required to be reviewed by the Technical Unit. These procedures require the Form 3753 or Form 5792 to be forwarded to the Technical Unit for review. These requests must be received by 2:00 P.M. local time at the receiving campus to complete review. Requests received after 2:00 P.M. will be completed the following business day.
For employees in sites that have a Technical Unit, the Technical Unit will verify the accuracy of the credit interest, identify and correct any errors and return the refund to the originator.
For employees in sites that do not have a Technical Unit, fax Form 3753 or Form 5792, including a copy of the interest computation, to:
For IMF modules:
Philadelphia, TS CAS:PAMC
Attention: Adjustments P&A Staff
EEFax Number: 866-434-7054
For BMF modules:
Ogden, TS CAS:OAMC
Attention: Technical Interest Team 203 Manager
EEFax Number: 855-269-1647The Technical Team will verify the accuracy of the credit interest, identify and correct any errors and fax the approved Form 3753 or Form 5792 to the initiator the same day. Employees in these sites must attach a copy of the approved faxed Form 3753 or Form 5792 to be forwarded to Accounting. If any corrections were made, a new Form 3753 or Form 5792 will have to be completed.
Each refund reviewed must have the "Interest Approved" signature and date. This signature can be placed at the bottom of Form 5792/Form 3753 near Part one literal by inserting a text box if using a PDF electronic copy or they can be handwritten if forwarding paper copy. Accounting will reject any manual refund requested by Accounts Management more than $1 million that has not been reviewed by the Technical Unit.
A copy or fax of any corrections to the interest computation will also be referred to the manager of the initiator.
When issuing a manual refund to a person or address other than that shown on Master File (CC ENMOD or CC INOLE), input a TC 971 AC 037 using the CC RFUND input date as the Transaction Date and enter the Taxpayer Identification Number (TIN) of the entity receiving the refund. When the SSN/EIN of a third party is needed, the third party can only be solicited for this information through written correspondence because privacy rights must be given with the solicitation. Since Form 1310, Statement of Person Claiming Refund Due a Deceased Taxpayer, includes the required Privacy Rights provisions, it can be used to request the SSN/EIN of a third party. Refer to IRM 21.4.6.5.6.6 (8), Issuing the Injured Spouse Refund, for TC 971 AC 037 instructions when working an Injured Spouse claim.
When issuing a manual refund from an account without a TC 150, monitor the account and release the -X freeze when there are no expectations of a return being filed.
In addition to explaining why a different entity is necessary on Form 5792 or Form 3753, indicate where the back-up documentation can be found (e.g., injured spouse, now separated, attached to nnn-nn-nnnn, 200812, TC 290).
When issuing a refund on a decedent account and a Form 1310 is required, ensure Part I is completed. Refer to IRM 3.11.3.10.3, Documentary Evidence on a Decedent Return, for procedures on identifying a correctly completed Form 1310.
Note:
A missing, incomplete or incorrect tax year at the top of the Form 1310 may be perfected, if all other elements are completed and the form has a valid signature. Forms 1310 located in MeF or EUP are tax-year specific and may only be used for the tax year shown on the form. A Form 1310 found for a different tax year may not be used to support the current case unless it was submitted as a reply to IRS correspondence for the tax year being worked.
If an offset credit is being refunded, refer to IRM 21.4.6.5.1.1, Tax Offset Reversal, to determine when the offset must be reversed back to the original module instead of being refunded.
If a reversal of offset credit is NOT required per IRM 21.4.6.5.1.1, Tax Offset Reversal, then notate in the remarks field of Form 5792 or Form 3753 that a reversal of the TC 706 is not required.
If a reversal of offset credit IS required per IRM 21.4.6.5.1.1, Tax Offset Reversal, input a TC 570 with the reversal transaction to prevent an UPC 198, re-offset, or refund that would create an erroneous refund condition. Refer to IRM 21.5.8.4.5, TC 570 and Bypass Indicator, for more information on TC 570 and UPC 198.
Joint Committee Cases, in excess of the jurisdictional threshold of $2 million to an individual ($5 million for C corporations), per IRC 6405(a), must provide the supporting documentation from the Chief of Staff when submitting the manual refund documents to accounting. See IRM 4.36.4, Joint Committee Review Team Procedures.
Effective June 20, 2023, all manual refund monitoring is now performed at the Headquarters level. Initiating sites are responsible to ensure manual refunds submitted have been accepted by Accounting, any manual refunds rejected are to be re-input within five business day’s.
Note:
To ensure manual refunds have been accepted by Accounting, load the previous days EMT exports from your C: drive into your EMT/Case Monitoring Tool. Then run the Monitor function on the EMT/Case Monitoring Tool and act on any cases that are archived as “DQ”. Any cases that are not archived as “DQ” can be deleted from the EMT tool. Cases that are archived as “DQ” are required to be reviewed, corrected and re-input within five business days.
The following subsections provide information on programs which are not readily available in other IRM chapters. Programs discussed here are Credit Card Chargebacks, and Photocopy Fee Refunds.
When a photocopy fee refund is returned to the Regional Finance Center (RFC) by the postal service as undeliverable, the RFC returns a cancellation credit for the check to the appropriate campus on SF 1098. A copy of the SF 1098 is sent to the Return and Income Verification Services (RAIVS) Unit. See IRM 3.5.21.5.1.12.3, Returned Photocopy Refund, for further information.
If a taxpayer returns a photocopy refund check, process as follows:
Send the taxpayer a "C" letter acknowledging receipt of the check.
If the check is less than one year old, send to the RFC for cancellation, annotate on the Form 3210, Document Transmittal, to redeposit to "20X0903 Account" .
If the check is one year old or more, stamp the check "non-negotiable" and leave it in the case file.
Forward case file to the RAIVS Unit.
When the credit is returned on SF 1098, a copy of the listing will be forwarded to the RAIVS unit for processing.
If the taxpayer claims non-receipt of a photocopy refund, see IRM 3.5.21.5.1.12.2, Undelivered Refunds and LMTD Pay Cancellations.
Credit card payments made to the IRS are made through a third party service provider. A Chargeback is a credit card payment that the taxpayer says was made to the IRS in error. The taxpayer contacts their credit card company to state that the payment was not intended for the IRS and requested the funds be returned to them. The credit card company pulls this payment back from the credit card processor’s account and sends them all the necessary information for the processors to obtain this payment back from the IRS.
The credit card processor provides the IRS the necessary payment information to update the taxpayer's Master File account. Accepted credit card payment processors are:
ACI Payments, Inc(secondary name is Official Payments Corporation)
Link2Gov Corporation (operates Biller Solutions)
If the payment is in error or the taxpayer did not authorize or intend the payment to be sent to the IRS, the payment processor can request a refund. ALL claims for credit card chargebacks are worked ONLY in the Ogden Accounts Management Campus, Chargeback Team.
Treasury Regulation 301.6311-2(d)(2), makes returns of funds, or chargebacks, available for errors such as the following (this is not an all-inclusive listing):
An incorrect amount posted to the taxpayer's account because of a computational error, numerical transposition, or similar mistake
An amount posted to the wrong taxpayer's account
A transaction posted to the taxpayer's account without the taxpayer’s authorization
A payment that was not intended for the IRS
Similar types of errors that would be subject to the error resolution procedures of the Truth in Lending Act, the Electronic Fund Transfer Act, or similar provisions of state or local law, in ordinary commercial transactions
Credit card chargebacks are only authorized for the entire amount of the payment. Partial credit card chargebacks are not permitted.
When a taxpayer submits a request for a Credit Card Chargeback, the credit card processor reimburses the taxpayer in advance. The processor then submits a Credit Card Chargeback request to the IRS for reimbursement of funds.
Credit card processors send an additional type of Credit Card Chargeback known as a Reversal. On Reversal Chargebacks, the taxpayer has not received their credit back from the processor in advance. Therefore, this type of Credit Card Chargeback can be cancelled with the credit card processors if the funds have already refunded to the taxpayer.
If the taxpayer contacts the IRS to initiate a request for a credit card chargeback, refer the taxpayer to the credit card issuer's customer service number on the back of the card or on the billing statement. Taxpayers can also visit the Electronic Payment Options Home Page on IRS.gov for service provider information. Taxpayers will contact these companies to report problems such as unauthorized charges or concerns regarding payment errors not related to the tax liability. Generally, credit card payments cannot be cancelled. See IRM 21.2.1.48.4, Payment by Credit Card, Debit Card or Digital Wallet (General), for additional information regarding credit card payments.
The credit card company must submit the claim within 150 days from date of payment. The request must contain the signature of one or more company authorized employees. If the payment is over 150 days old, the Lead Examiner must contact Headquarters for approval.
Note:
Effective February 17, 2025, the claims received by the credit card processors must use the Chargeback Request Form shown in Exhibit 21.4.4-1. This form was updated to include all three processor companies at the top. They will need to add a check mark in the box next to their company. We have also included the requirement to add the EFT Number of the payment and removed the requirement for the history of company actions taken to prove the taxpayers dispute.
The following procedures outlined in this subsection and IRM 21.4.4.7.2.2, How Is a Chargeback Request Processed?, are used exclusively by employees in the Ogden Accounts Management Campus, Chargeback Team, when working credit card chargeback claims submitted by credit card companies.
Contact information for the credit card companies can be found on the SERP home page under the "Who/Where" tab under Credit Card Chargeback Contacts.
The company must submit the following required documentation with the form, Exhibit 21.4.4-1, Chargeback Request Form, no later than 5 business days from receipt of the taxpayer request:
Copy of the dispute letter from the credit card holder or letter from credit card issuer describing the problem
Date the company received the dispute letter
Date sent to Internal Revenue Service
An affidavit indicating whether this is a chargeback or a reversal request
Card holder's name and address or Interactive Voice Recording (IVR)
Credit card number
Date of payment
Amount of payment
Credit card payment confirmation number
EFT Number
SSN or EIN of the account
Optional Form 8302, Direct Deposit of Tax Refund of $1 Million or More, for a refund of $100 million or more
The basic research requirements within IRM 21.4.4.4, What Research Is Required?, do not apply to chargeback cases. Once the company provides all the necessary verification, research the identified account for the erroneous payment. To identify a credit card payment on the account, the common transactions are:
TC 640, Advanced payment of determined deficiency, Form 1040
TC 660, 1040 Estimated Tax payment
TC 670, Subsequent payment Form 1040, Trust Fund Recovery Penalty (MFT 55), Form 940, Form 941, and Form 944
TC 670 or TC 640, Payment with Extension to File, Form 4868, Application for Automatic Extension of Time to File U.S. Individual Income Tax Return
Electronic payments will contain an EFT-Trace number. If the second position of the EFT-Trace number is a "6" , the payment was a credit card payment. Bulk Provider Number positions 8-9 identify which credit card processor to use. For more information, see IRM 3.17.277.5.3, EFT Number.
Allow the claim if the transaction date is within 5 days either way of the date on the claim.
Control the case when received. Use a unique case control numbering system. Associate the control number with source documentation (e.g., Form 3753, Form 2424, Form 3210, etc.). For the processing time frames of these cases, follow the guidelines in IRM 21.5.1, General Adjustments, and IRM 21.5.2, Adjustment Guidelines. The case will age in 45 days.
If the payment has refunded, respond to the credit card processor with the approved letter. Exact wording can be found inExhibit 21.4.4-2. These responses must be issued within 30 business days of receiving the chargeback request.
Along with the letter, a copy of the cancelled refund check pulled from TCIS can be sent. However, the following information must be redacted from the copy of the check sent to the credit card processors:
The legal reasoning that supports providing a copy of the redacted refund check is in accordance with these instructions is that the only information left unredacted on the check constitutes information whose disclosure has been deemed by the Service to be necessary for the administration of IRC 6311, as required under IRC 6103(k)(9) and the regulations at Treas. Reg. § 301.6103(k)(9)-1.On the front of the check:
The taxpayer address in the “Pay to order of” section and the information about the name control
Campus
Tax period
Nature of check (e.g., “tax refund”)
MFTOn the back of the check:
Numerical data in upper-left corner representing bank account information for taxpayer and date cashed,
Numerical data immediately below this information,
All data at the bottom of the check in the “Electronic Endorsements” section - for both the Bank of First Deposit (BOFD) and Subsequent areas,
Any other indication on the check of the taxpayer’s bank account number, for example if the taxpayer handwrites their account number in the endorsement section.
If the taxpayer received a refund due to the unauthorized credit card overpayment on the account, follow IRM 21.4.5.6.1, Account Actions for Category D Erroneous Refunds. If the refund is ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡, or if a Z freeze exists on the account, refer the case to the Criminal Investigation Scheme Development Center using normal referral procedures. The Criminal Investigation Scheme Development Center will compare the case information with the deconfliction/scheme development process information to determine if the case should be included in a current scheme or is part of an ongoing case.
If the unauthorized or unintended payment is still on the taxpayer's account take the following actions:
If payment will refund or offset, input a TC 570 on the account where the erroneous payment resides until the case can be resolved
Prepare Form 2424, Account Adjustment Voucher, to correct the account
Debit the taxpayer's account with the corresponding TC of the payment
Credit Account 6910 with the TC of the payment
Use date of the payment as the transaction date for both the debit and credit
Notate "chargeback for credit card payment" in the comments area
If the money is offset to another account, complete the credit transfer back to the original account module, and adjust the account as outlined above.
If you are unable to locate the payment, research IRM 21.5.7.3.4.14, Electronic Federal Tax payment System (EFTPS). If you have exhausted all research tool capabilities, reject claim back to the credit card processor advising them that additional payment information is needed.
To refund the payment to the card processor, complete Form 3753 following guidance in IRM 3.17.79.3.18, Credit Card Processor Chargebacks (Ogden Accounts Management Only).
Prepare Form 3210, Document Transmittal, as follows:
In the remarks block enter company name and TIN and note "Chargeback of credit card payment"
In the "code" or "type" block enter 3753 in the first block only
Attach a copy of the Form 3753
Enter each case separately using TIN and money amounts for each individual case
Total amount for the Form 3210 and enter the amount in the Remarks box at the top of the document. Attach a copy of the excel spreadsheet to the Form 3210. This amount must match Block 12b of Form 3753.
Enter complete information in the from box
Releasing Official must sign the Form 3210
The Form 3753 must be digitally signed and emailed to Accounting. Follow the table below for the naming convention for each credit card processor. The name control will be the first four letters of the name the refund is made out to, the last 4 digits of the refund amount, minus the decimal. For example, if the refund is $65,578.90, the digits would be 7890. Use the fund code, 20X1807 and then the type of refund form:
Credit Card Processor Naming Convention - Form 3753 Link to gov LINK 1234 20X1807 3753 ACI Payments Inc ACIP 1234 20X1807 3753 Credit Card Processor Naming Convention - Back-Up Documentation Link to gov LINK 1234 20X1807 Doc ACI Payments Inc ACIP 1234 20X1807 Doc The email to Accounting will include 2 attachments. One attachment is the signed Form 3753. The second attachment will be the Form 3210 and a copy of the Excel worksheet showing the total count and amount.
Route all the remaining back-up documentation, the Forms 2424, the chargeback form and letter and/or affidavit, for each taxpayer associated with the Form 3753, to Stop 6261.
If any of the required documentation is missing in the request from the card processor, call or write the credit card company requesting the missing information. See IRM 21.4.4.7.2.1, How Is a Chargeback Initiated?
Request the information be supplied within 10 calendar days
Allow 15 calendar days for response. If no response within 15 calendar days, follow-up with a second request to the company
Allow another 15 calendar days for response to second request
If no response to the second request, do not honor the chargeback request
Advise the company of the IRS's denial and the reason(s) for the denial
Do not issue a Claim Disallowance Letter
Secure managerial approval and close the case
| CHARGEBACK FOR UNAUTHORIZED OR ERRONEOUS CREDIT CARD PAYMENT |
|---|
| □Link to gov □Official Payments |
| Copy of the dispute letter attached: ____Yes ____No (Dispute letter must contain the name and address of the cardholder) |
| Date of the dispute letter: |
| Date received: |
| Date sent to Internal Revenue Service: |
| PAYMENT INFORMATION |
| Date of the payment: |
| Amount of the payment: |
| Credit Card Number used in the transaction: |
| Credit Card Confirmation Number: |
| EFT Number: |
| Social Security Number: (payment was applied) |
| Under penalties of perjury, I declare that I have examined this form and accompanying statements, and to the best of my knowledge and belief, they are true, correct, and accurately represent the amount of Chargeback, caused by either erroneous or unauthorized use of the credit card listed on this form and applied to the identified taxpayer's account. SIGNATURE OF COMPANY OFFICIAL:_____________________________________ DATE: ______________________________________ |
| Title: |
| ELECTRONIC FUNDS TRANSFER (EFT) REPAYMENT REQUEST EFT Requested: ____Yes ____No If yes is checked, complete the bank account information: Routing and Transit Number: Bank Account Number: |
| Check Attachments: Dispute letter (Required) Form 8302, Electronic Deposit of Tax Refund of $1 Million or More (Optional; only required when the chargeback is for $1 million or more.) Other: (Identify other attachments) |
| Example of Letter Wording |
|---|
| Today’s date NOTICE OF DISPUTE REBUTTAL On [transaction date], taxpayer [enter taxpayer name] made an electronic payment in the amount of [enter amount of transaction] through [enter credit card processor name] to the Internal Revenue Service (IRS). Per IRS policy, the IRS issued a refund for this payment to [enter taxpayer name] via [check or direct deposit] on [enter date of refund]. Thank you for your cooperation in this matter. [AM Management Signature] |
Thorough research is required on all manual refunds prior to issuance.
Prior to issuing manual refunds, initiators must review account information and take actions such as:
Determine if the account is subject to offset by Bureau of the Fiscal Service Treasury Offset Program (TOP) or other tax obligations.
Use appropriate hold codes or posting delay codes as applicable.
Use TC 570 with credit transfers.
Enter appropriate computer condition codes (CCC) with an original return.
Use IDRS to ensure no other site or employee has issued a duplicate refund (TC 840), TC 971 AC 664, or that a refund has already generated (TC 846). The presence of a TC 971 AC 664 indicates that a Form 3753 is in process. If a generated refund will be issued within two cycles, do not issue a manual refund. It is necessary that prepaid credits claimed by the taxpayer are available for refund and that the taxpayer does not have any outstanding balances.
Research freeze codes or IDRS control bases assigned to another IRS employee. If accounts are controlled, take no further action to release the freeze or control base without contacting that employee first.
A -U Freeze (Erroneous Refund Freeze) requires contact with the Erroneous Refund function and documentation of approval by the Erroneous Refund function in the remarks section of Form 5792 / Form 3753.
Master File displays a TC 844 at times with a TC 700, Document Code 58 in the DLN.
These accounts are being monitored by the Erroneous Refund function (SP Accounting Operations) to recover an unassessed erroneous refund.
The TC 700 Document Code 58 is input by Accounting to prevent erroneous billing notices and will compensate injured taxpayers from a general ledger account. Transcripts (TRANS 844) generate to the Erroneous Refund function for applying credits that become available on accounts at the controlling SP Center.Review IMFOL/BMFOL. Determine whether a direct deposit was already issued to a bank account.
Ensure erroneous refunds are not released during BMF accelerated cycles (generally occurs during the end of May, September and October). Refund intercepts (stopping refunds via IDRS CC NOREF) are not possible during accelerated cycles.
The table below summarizes the basic research required for all manual refunds (those issued on Form 5792, Request for IDRS Generated Refund (IGR), and Form 3753, Manual Refund Posting Voucher):
IDRS Research Required on All Manual Refunds. Verify: TIN
MFT and Tax Period
Payee name and address
Debt indicators (TOP offset), XREF TINs, TC 130 Indicator
The following information must be attached to the manual refund form:Sufficient documentation to justify issuing the manual refund (for example: taxpayer correspondence, internal transcript, copy of Form 1040X, Form 1045, Form 4442, Form 8379 or the injured spouse worksheet if applicable, Form 1310, Form 843, the taxpayer's hardship documentation or a signed statement from the Local Taxpayer Advocate (LTA) approving the taxpayer's hardship refund request, etc.)
CC COMPA or Automated Computation Tool (ACT)/Decision Modeling Inc. (DMI) Report 490 (if interest was calculated)
CC ENMOD (only if a pending name or address change is indicated)
If the original return was coded with CCC 3, was a U coded return (Form 1040), or Computer Condition Code X (Form 1120) is present on IDRS, indicating the original return was unprocessable due to the taxpayer not responding to Error Resolution correspondence, the RPD must be entered in the remarks, and a completed REQ54 screen print showing the RPD must be attached as backup documentation to the manual refund.
If a previous adjustment was input to the module with an RPD, a copy of the REQ54 screen is not required because the RPD appears on CC IMFOLR/BMFOLR. For more information see IRM 21.2.4.3.40.1, Computer Condition Code (CCC) 3 or U-Coded Returns.Generally, unless required by the specific type of manual refund being input all other IDRS prints are not required to be attached to the manual refund request, as the Accounting Functions have access to IDRS and can verify the information.
Verify outstanding balances (OBLs); research all related accounts (IMF, BMF, NMF) for OBLs using the following CCs: CC SUMRY
CC TXMOD
CC IMFOLI/CC BMFOLI
CC IMFOLT/CC BMFOLT
Research CC TXMOD for TC 971 AC 664, which indicates a manual refund has been scheduled/issued by the Accounting Function using Form 3753, Manual Refund Posting Voucher. Review/verify "O" (letter O) coded returns - See Document 6209, IMF Computer Condition Codes."O" code identifies a pre-settlement manual refund was paid. Attach offset bypass refund (OBR) or hardship verification, if applicable. Research CC FFINQ - Requests IMF from the Fact of Filing information file. Review manual refunds over $1 Million - Technical unit is required to review credit interest. Resolve other open controls and receive approval from other functions (if applicable) to process the manual refund. Input/review for TC 291, TC 295, TC 299, TC 766 with a HC 1, 2, or 4. Input TC 570 as applicable. A review of the sections of Form 5792, Request for IDRS Generated Refund (IGR), is shown below. See IRM 21.4.4.5.1, Preparation of Form 5792, IDRS Generated Refund, for additional information.
Note:
The use of the IAT Manual Refund Tool is mandatory for preparation of manual refund forms and CC RFUNDR input per IRM 21.2.2-2, Accounts Management Mandated IAT Tools.
A review of the sections of Form 3753, Manual Refund Posting Voucher, is shown below. See IRM 21.4.4.5.2, Preparation of the Form 3753, Manual Refund Posting Voucher, for additional information.
Note:
The use of the IAT Manual Refund Tool is mandatory for preparation of manual refund forms per IRM 21.2.2-2, Accounts Management Mandated IAT Tools.
| Manual Refund Team Contact Information | ||
|---|---|---|
| Accounts Management Site | Accounting Submission Processing Site and Contact Information | Daily Cutoff Times for Manual Refunds to be processed the same day: |
| Austin | Austin Submission Processing Center Manual Refund Function
|
|
| Andover, Atlanta, Fresno and Kansas City | Kansas City Submission Processing Center Manual Refund Function
|
|
| Brookhaven, Cincinnati, Memphis, Ogden, Philadelphia and Puerto Rico | Ogden Submission Processing Center Manual Refund Function
|
|
(1) The Submission Processing, Accounting functions are required to reject manual refund requests with errors on Form 5792 and Form 3753 back to the originator and approver as soon as possible, but no later than the next business day following the day of the reject.
(2) A Form 15276, Accounting Operation Manual Refund Reject Feedback, document is issued for EACH rejected manual refund and will provide the following information:
Command code “RFUNDR” input by employee IDRS number
Reject date (MM-DD-YYYY)
BOD of originator
Name of originator
SEID of originator
TIN
MFT (##)
Tax period (######)
Refund amount ($#,###,##)
Rejected by (accounting site)
Name of approving official
SEID of approving official
(3) The entire Manual Refund Form, and all supporting documentation, are reviewed prior to being sent to the originator so that all errors are identified with the initial review and identified in Sections I through Section VII of the form.
Note:
If a prior Manual Refund Reject is resubmitted, and a previously unidentified error is discovered, the submitting BOD will not be charged with an additional reject. New errors identified on the resubmitted Manual Refund will result in an additional reject for the submitting BOD.
(4) IRM references are included in the comments area of all applicable sections (Sections I through Section VII) of the form to support the reason for the reject. If more than one defect error is identified within any given section (Sections I through VII) then the Other box is checked within the section and all of the individual errors within that section are listed in the comments.
(5) Upon receipt of the Form 15276, the originator will forward a copy of the Form 15276 to their Lead along with their response to the reject.
The response will include:
If the originator agrees or disagrees with the reject.
If agreed, why the rejection occurred and what steps will be taken to ensure the error does not reoccur.
For example: 800 number listed on Form 5792 or Form 3753 - IAT tool not set correctly, IAT tool has been updated.If disagreed, the reason for disagreement and provide an IRM reference if required IRM was followed but rejection was given.
(6) If the originator agrees with the defect, or the defect was due to an approver’s signature error, then once the originator corrects all errors identified by the Accounting Function, they will resubmit the corrected Manual Refund through the Accounting Function’s Organizational Mailbox (OMX), and not send it directly to the employee that rejected the original.
Note:
Any Manual Refund correction sent directly to the employee that rejected the original Manual Refund will not be processed and will result in a DQ transaction.
(7) If the originator does not agree with the reject, the dispute of the Manual Refund reject will be replied to by the Lead of the Manual Refund Originator, the Manual Refund Approver, or BOD Point of Contact and will be forwarded to the SP accounting site which issued the reject within five business days of the Form 15276 being received.
Forward the original reject email, received from the originator, and add the word "Rebuttal" in the Subject line. The original email includes the Form 15276, original Manual Refund Form 3753 or 5792, and the original back-up documentation file, and must be sent by encrypted e-mail, but not password protected. The e-mail subject line MUST read EXACTLY as follows with no exceptions: Rebuttal MR Reject MM-DD-YYYY.
Note:
Manual Refund Originators, Manual Refund Approvers, or BOD Points of Contact should not directly contact the Accounting employee that rejected the Manual Refund or the SP Accounting Manual Refund HQ Points of Contact regarding Manual Refund rejects.
(8) The body of the email MUST contain the reason the reject is being disputed, including an IRM reference if applicable. The body of the email must also include:
The name control
The last four digits of the taxpayer's SSN
The applicable tax year
(9) When disputing a Manual Refund reject, the BOD Point of Contact listed in the chart below should also be copied on the dispute email. This will allow the BOD POC to follow the status of the reject and update their data accordingly.
| BOD | Point of Contact |
|---|---|
| SBSE HQ | *SBSE:CP:CO:BODPOC:MANREF |
| Whistleblower/ ICE Program | ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ |
| TAS HQ | *TAS Manual Refund Rejection |
| TEGE HQ | ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ |
| TS AM HQ | *TS CAS:AM:BODPOC:MANREF In addition to TS AM HQ, please include the following POCs based off initiating AM Site:
|
| TS SP HQ | Manual Refund Headquarter Contacts |
| TS RICS HQ | ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ |
| TS :CARE:FA | ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡(Location is Atlanta, GA) ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ |
| Appeals | ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ ≡ |
A color PDF version of the required fields indicated in the exhibits below can be found on SERP at the following link: Manual Refund Form 3753 Required Fields and Manual Refund Form 5792 Required Fields
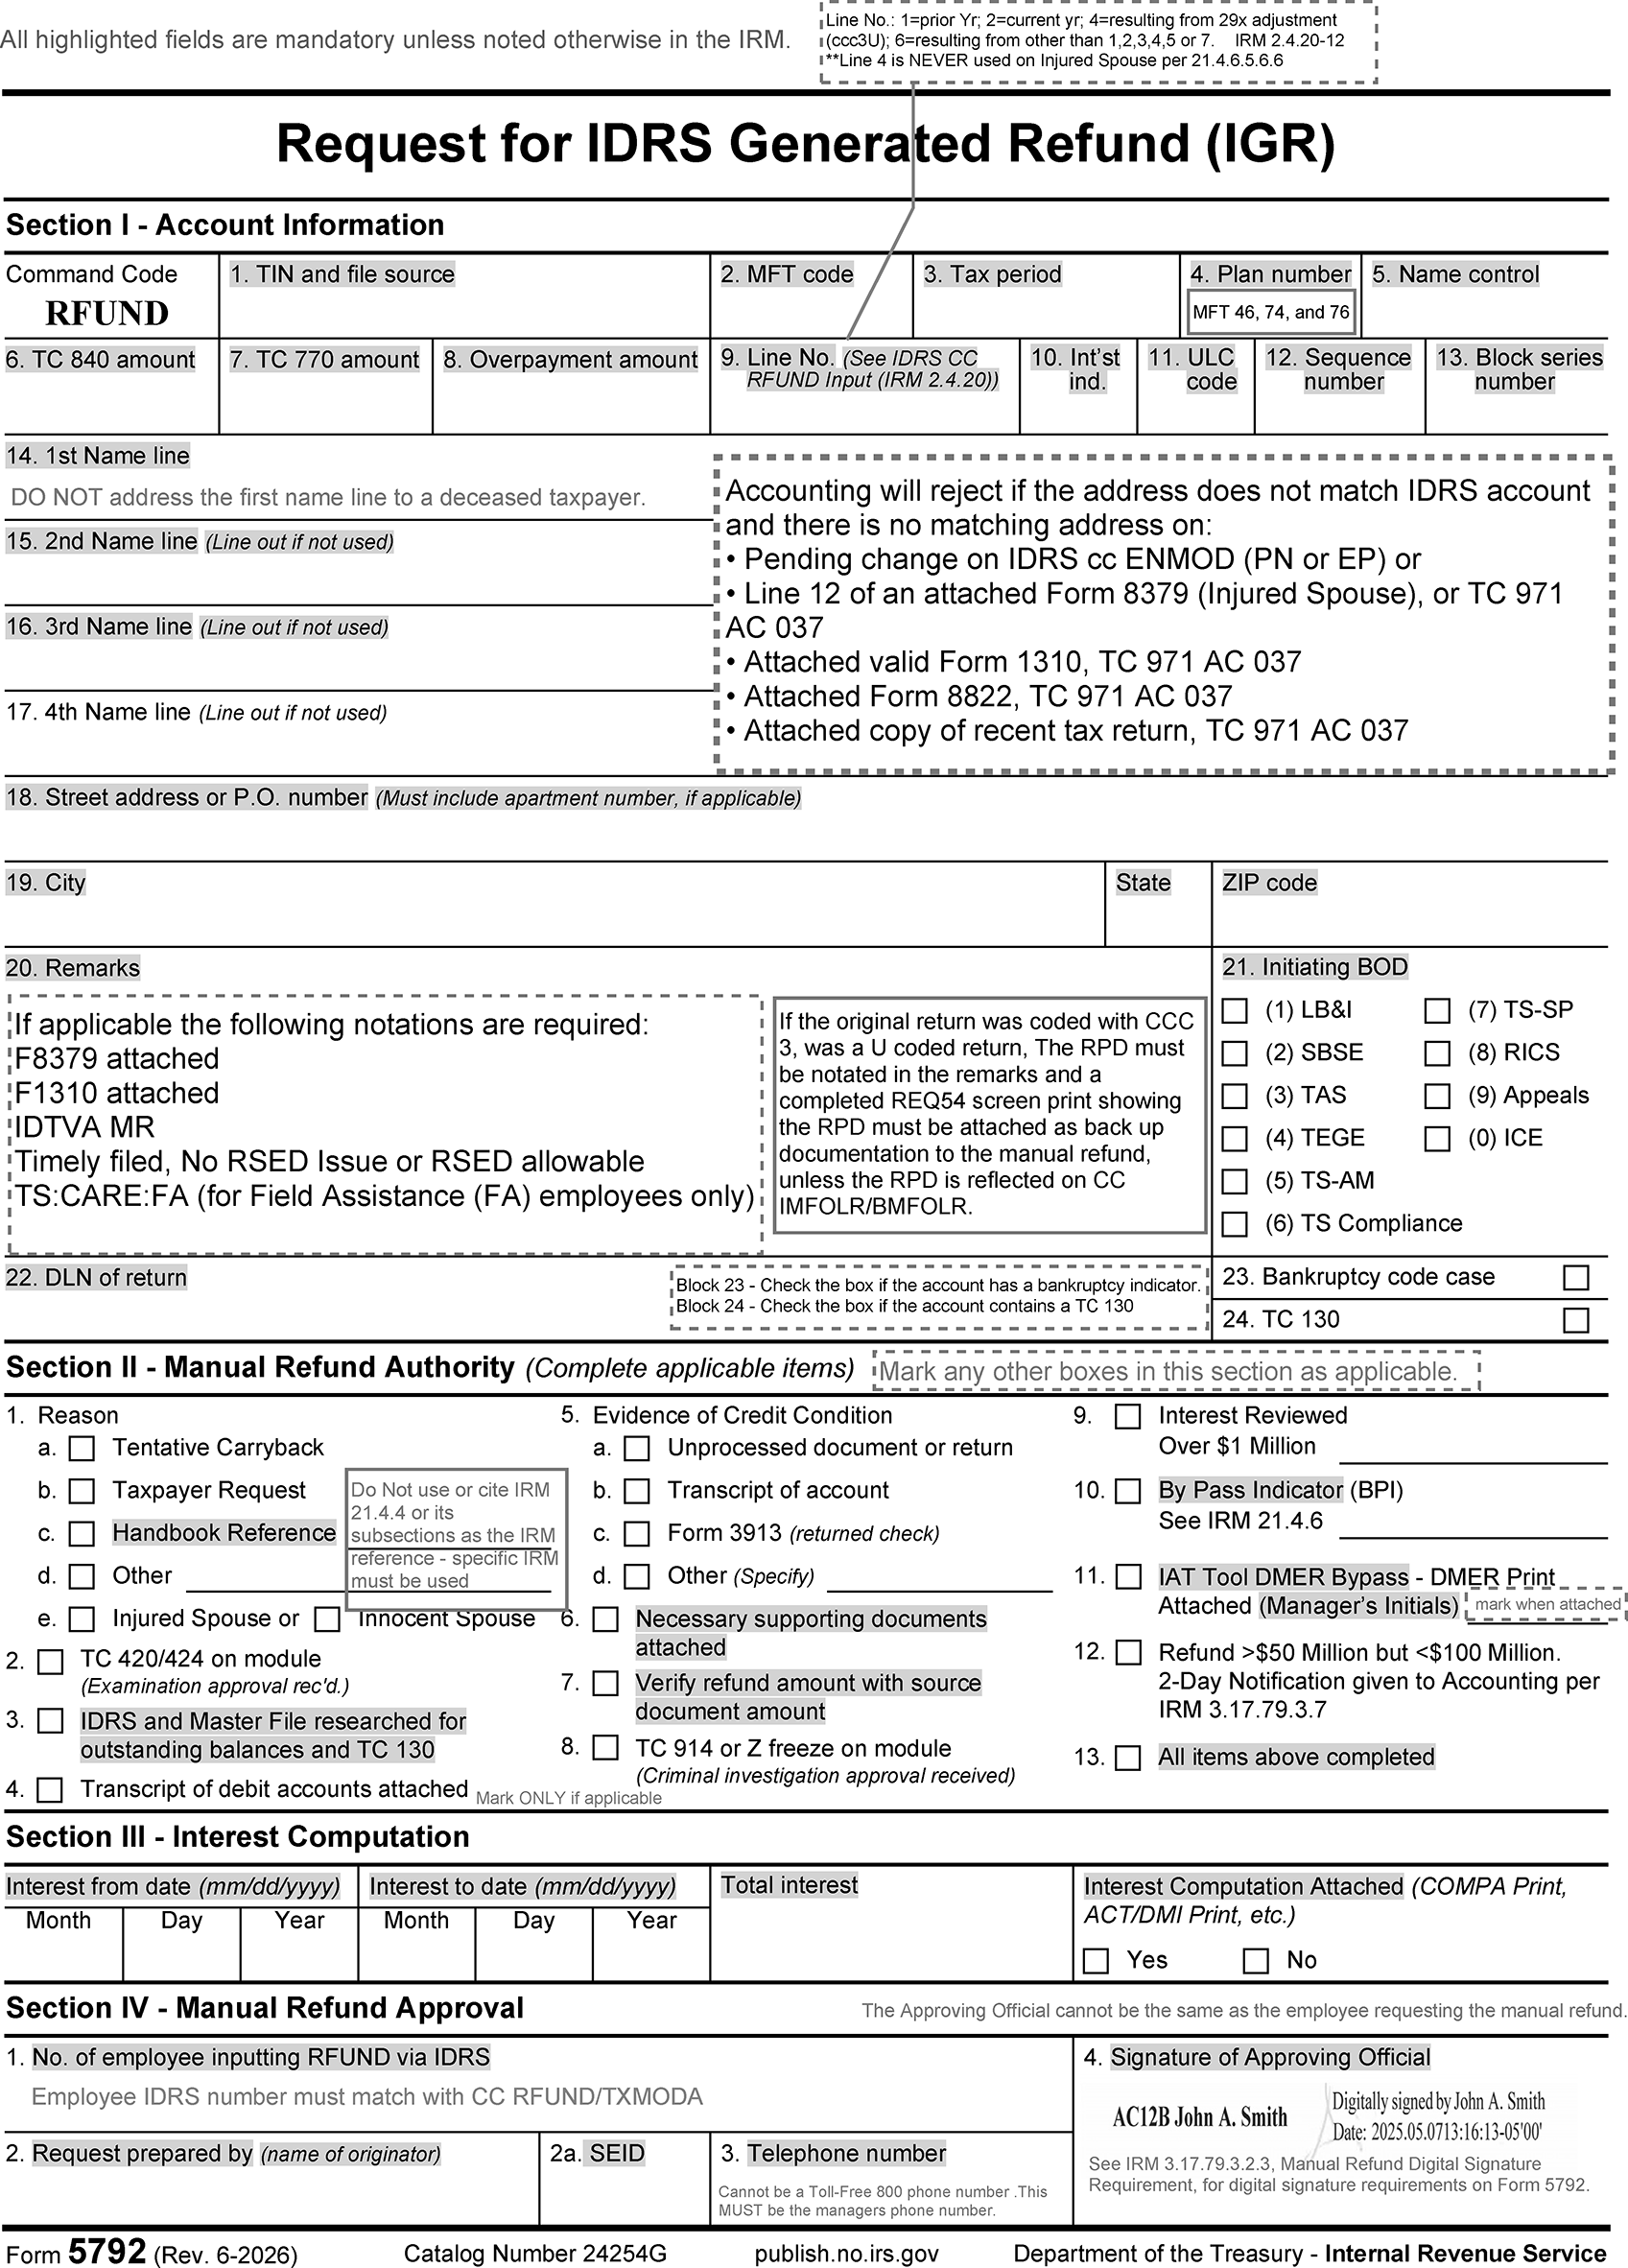
Please click here for the text description of the image.