)
or https:// means you've safely connected to the .gov website. Share sensitive information only on official, secure websites.

- 22.31.1 IRS Language Services
- 22.31.1.1 Program Scope and Objectives
- 22.31.1.1.1 Background
- 22.31.1.1.2 Authority
- 22.31.1.1.3 Roles and Responsibilities
- 22.31.1.1.4 Program Management and Review
- 22.31.1.1.5 Program Controls
- 22.31.1.1.6 Terms and Acronyms
- 22.31.1.1.7 Related Resources
- 22.31.1.2 Limited-English Proficiency (LEP) Strategic Process
- 22.31.1.3 Limited-English Proficient (LEP) Needs Assessment
- 22.31.1.3.1 The Customer Base Report (CBR)
- 22.31.1.4 Providing Language Assistance
- 22.31.1.4.1 Language Assistance
- 22.31.1.4.2 Language Standards
- 22.31.1.5 Standard Translation Process (STP)
- 22.31.1.5.1 Translation Request Decision Tree
- 22.31.1.5.2 Identifying the Document for Translation
- 22.31.1.5.2.1 Requesting Translations of Non-Vital Documents
- 22.31.1.5.2.2 Determining a Document Is for Public Use
- 22.31.1.5.2.3 Identifying the Language for Translation
- 22.31.1.5.2.4 Identifying the Document Originator/Owner
- 22.31.1.5.3 Determining the Candidacy of a Document for Translation
- 22.31.1.5.3.1 Determining Importance to Limited-English Proficient (LEP) Taxpayers
- 22.31.1.5.3.2 Determining Alternatives to Translation
- 22.31.1.5.3.3 Adding a Statement to the English Version
- 22.31.1.5.4 Evaluating the Organizational Impact of Translation
- 22.31.1.5.5 Processing a Translation Candidate
- 22.31.1.5.5.1 Categorizing Documents
- 22.31.1.5.5.2 Approving Documents for Translations
- 22.31.1.5.5.3 Requesting Translation Services
- 22.31.1.5.5.4 Translating and Reviewing Vital Documents
- 22.31.1.5.5.5 Translating Non-Vital Documents
- 22.31.1.5.5.5.1 Requesting Delivery Dates of Translated Non-Vital Documents
- 22.31.1.5.5.6 Performing Quality Review of Translated Non-Vital Documents
- 22.31.1.5.5.7 Proofreading of Non-Vital Documents
- 22.31.1.5.5.8 Maintaining Translated and Reviewed Documents
- 22.31.1.5.5.9 Recordkeeping of Translated and Reviewed Documents
- 22.31.1.6 Over-the-Phone Interpreter (OPI) Service
- 22.31.1.7 Multilingual Web Page Content Publishing Process
- 22.31.1.7.1 Strategic Planning
- 22.31.1.7.2 Content Requirements
- 22.31.1.7.3 Content Management
- 22.31.1.7.4 Transmitting Content Submission Packages to the Multilingual and Agency Services (MAS) Branch
- 22.31.1.7.5 Posting Content to the Multilingual Web Pages
- 22.31.1.7.6 Maintaining the Multilingual Web Pages
- 22.31.1.7.7 Languages Provided by Multilingual and Agency Services (MAS) Contractors
- Exhibit 22.31.1-1 Translation Request Decision Tree — Written Translation Services
- Exhibit 22.31.1-2 Form 13779, Certification of Compliance with Executive Order (E.O.) 14224 for Language Services Outside the Standard Supported Languages
- Exhibit 22.31.1-3 Over-the-Phone Interpreter (OPI) Service Decision Tree
- 22.31.1.1 Program Scope and Objectives
Part 22. Taxpayer Education and Assistance
Chapter 31. Multilingual Initiatives
Section 1. IRS Language Services
22.31.1 IRS Language Services
Manual Transmittal
October 21, 2026
Purpose
(1) This transmits revised IRM 22.31.1, Multilingual Initiative, IRS Language Services.
Material Changes
(1) IRM 22.31.1.1 (6), Program Scope and Objectives, removed TSS mailbox, as it is no longer being used.
(2) IRM 22.31.1.1.1 (6), Background, changed the language to better align with the restrictions of Executive Order (EO) 14224.
(3) IRM 22.31.1.1.2 (1), Authority, IPU 25U3726, dated December 15, 2025, edited verbiage for Executive Order (EO) 14224.
(4) IRM 22.31.1.1.4 (1), Program Management and Review, removed the reference to data being obtained form the U.S. Census Bureau, as it was moved to a another section.
(5) IRM 22.31.1.1.6 (1), Terms and Acronyms, removed the reference to the Department of Justice LEP Guidance and added the reference to data being obtained from the Census.
(6) IRM 22.31.1.1.6 (2), Terms and Acronyms, removed acronym for Multilingual Executive Council (MEC).
(7) IRM 22.31.1.2.1 (1), Language Services Executive Advisory Council (LSEAC) Strategic Process Responsibilities, removed reference to Multilingual Executive Council (MEC) as it no longer applies.
(8) IRM 22.31.1.2.2 (3), Multilingual and Agency Services (MAS) Branch Strategic Process Responsibilities, removed reference to Department of Treasury LEP Guidance and replaced with IRC 7803(a)(3) and Title VI of the Civil Rights Act of 1964 (42.U.S.C 2000d)
(9) IRM 22.31.1.4 (3), Providing Language Assistance, updated verbiage in Example, as we don’t process actual hard copy documents.
(10) IRM 22.31.1.4 (4), Providing Language Assistance, removed the four-factor analysis concept, as it was derived from Executive Order (EO) 13166.
(11) IRM 22.31.1.4 (5), Providing Language Assistance, added paragraph to show the instances in which language services for languages outside the standard supported set may be provided.
(12) IRM 22.31.1.4.2 (7), Language Standards, added note referencing IRM 10.5.1.6.9.7 for additional requirements regarding the protection and authorized use of FTI, PII, and approved translation or electronic processing tools.
(13) IRM 22.31.1.5 (2), Standard Translation Process (STP), corrected phrasing for type of customers serviced.
(14) IRM 22.31.1.5 (5), Standard Translation Process (STP), added paragraph stating which type of documents are considered special products.
(15) IRM 22.31.1.5 (6), Standard Translation Process (STP), updated components of the STP.
(16) IRM 22.31.1.5.1, Translation Request Decision Tree, new section added introducing the required decision framework completed by the customer to justify a translation request and enable MAS to prioritize it.
(17) IRM 22.31.1.5.2, Identifying the Documentation for Translation, reworded for further clarification.
(18) IRM 22.31.1.5.2.1 (3), Requesting Translation of Non-Vital Documents, updated the translation/quality review requirements.
(19) IRM 22.31.1.5.2.3, Identifying the Language for Translation, added that languages serviced are determined by Executive Order (EO) 14224.
(20) IRM 22.31.1.5.5.3 (1), Requesting Translation Services, added reference to the Translation Requestor Decision Tree and the Form 13799, Certification of Compliance with Executive Order (E.O.) 14224 for Language Services Outside the Standard Supported Languages.
(21) IRM 22.31.1.5.5.3 (2), Requesting Translation Services, updated verbiage in third example to allow for flexibility in sharing, in case the preferred audio sharing platform changes.
(22) IRM 22.31.1.5.5.4 (3), Translating and Reviewing Vital Documents, added paragraph stating what languages are available for translation of vital documents.
(23) IRM 22.31.1.5.5.6 (7), Performing Quality Review of Translated Non-Vital Documents, updated verbiage in first example to include what documents to attach to request.
(24) IRM 22.31.1.5.5.6.1 (2), Requesting Delivery Dates of Non-Vital Documents That Undergo Quality Review, updated verbiage to change the manner in which requests are received.
(25) IRM 22.31.1.6 (4), Over-the-Phone (OPI) Service, added a paragraph identifying the languages in which services are available.
(26) IRM 22.31.1.6 (5), Over-the-Phone (OPI) Service, added a paragraph referencing the new Over-the-Phone Interpreter (OPI) Service Decision tree, used to determine weather OPI services will be allowed outside of the frequently encountered languages.
(27) IRM 22.31.1.6 (6), Over-the-Phone (OPI) Service, added a paragraph explaining when a Form, 13779, Compliance with Executive Order (E.O.) 14224 for language Services Outside the Standard Supported Languages is required.
(28) IRM 22.31.1.6 (7), Over-the-Phone (OPI) Service, added a paragraph containing information on when and how to submit the Form, 13779, Compliance with Executive Order (E.O.) 14224 for language Services Outside the Standard Supported Languages.
(29) IRM 22.31.1.7.7, Languages Provided by Multilingual and Agency Services (MAS) Contractors, added a section outlining the updated list of languages supported by MAS contractors and the procedures to follow when a request involves a language outside of the top seven supported languages.
(30) Exhibit IRM 22.31.1-1, removed exhibit as translation services are now limited to the top seven languages; other languages may be considered on a case-by-case basis. Added IRM section 22.31.1.7.7 to reflect these changes.
(31) Exhibit IRM 22.31.1-1, added exhibit for Translation Request Decision Tree- Written Translation Services
(32) Exhibit IRM 22.31.1-2, added exhibit for Form 13779 - Certification with Executive Order (EO) 14224 for Language Services Outside the Standard Supported Languages
(33) Exhibit IRM 22.31.1-3, added exhibit for Over-the-Phone Interpreter (OPI) Services Decision Tree
(34) Editorial changes made throughout the IRM, including:
- Restructured some sentences to conform to Plain Language requirements
- Corrected grammatical errors
- Fixed broken/naked links
Effect on Other Documents
IRM 22.31.1, IRS Language Services, dated November 20, 2025, is superseded.
Audience
All IRS employees
Effective Date
(10-21-2026)
Maria Cheeks
Director, Tax Forms and Publications
Media and Publications Division
- Purpose: This IRM gives guidance for implementing the Language Services (LS) Program throughout the IRS. The LS Program gives language assistance to Limited-English Proficient (LEP) taxpayers.
- Audience: This IRM’s target audience is IRS employees who serve taxpayers for whom English is not their primary language.
- Policy Owner: Ownership of the Language Services Program belongs to the Taxpayer Services Chief.
- Program Owner: The Director of Media and Publications (M&P) within Taxpayer Services serves as the LS Program Executive Director and interfaces in conflict resolution, manages funding, approves priority status, and co-chairs the Language Services Executive Advisory Council (LSEAC).
- Primary Stakeholders: The stakeholders for this IRM include all IRS employees, vendors, contractors, etc., who provide oral and written language assistance to LEP and non-English speaking taxpayers.
- Contact Information: For information about this IRM, contact the Linguistic Policy, Tools, and Services (LPTS) Section at *Linguistic.Services
- The LS Program demonstrates the IRS’s commitment to assist taxpayers with limited-English proficiency (LEP) with understanding and meeting their tax responsibilities. The LS Program ensures that LEP taxpayers’ rights are protected as outlined in the Taxpayer Bill of Rights (TBOR). The TBOR lists rights that already existed in the tax code, putting them in simple language and grouping them into 10 fundamental rights. Employees must be familiar with and act in accordance with taxpayer rights. See IRC 7803(a)(3), Execution of duties in accord with taxpayer rights. For more information about the TBOR, see Taxpayer Bill of Rights.
- The scope of the LS Program includes all tax-related written and oral communications provided by or for taxpayers in non-English languages. It does not apply to braille, American Sign Language, or communications that are internal use only.
- The LS Program is Servicewide. All IRS organizations and their agents (e.g., contractors, volunteers) must uphold its requirements.
- The LS Program, through the Standard Translation Process (STP), sets procedures, processes, and requirements for translation.
- Oral language assistance is available through the Over-the-Phone Interpreter (OPI) Service. For more information, see IRM 22.31.1.6, Over-the-Phone Interpreter (OPI) Service.
- The goal of the LS Program is to provide LEP taxpayers top-quality service by ensuring meaningful access to the same products and services as English-speaking taxpayers.
- Executive Order (EO) 14224, Designating English as the Official Language of the United States, designates English as the official language of the United States. Accordingly, the English-language versions of all documents are the authoritative versions of all federal information. Due to the signing of this EO, IRS is limiting language services provided to customers, ensuring the agency’s compliance with EO 14224 while still fulfilling its mission to service taxpayers and enforce the tax laws. See IRM 22.31.1.5.5.3 (1) for limitations on written translation services. See IRM 22.31.1.6(4) for limitations on Over-the-Phone Interpreter (OPI) Services.
Policy Statement 22-3, Commitment to Assist Non-English Speaking Taxpayers Understand Their Tax Obligations, found in IRM 1.2.1.14.3, affirms IRS’s commitment to help non-English speaking taxpayers understand their tax obligations as follows:
"The IRS commits to provide top quality service to each taxpayer, including those who lack a full command of the English language. The needs of these taxpayers will be included in the agency strategic and tactical plans consistent with available resources. Our workforce will have the essential tools necessary to interact appropriately with our diverse taxpayer base."
- The Taxpayer Services Chief owns the Language Services (LS) Program.
- The Language Services Executive Advisory Council (LSEAC) serves as the executive advisory board and is the Servicewide focal point for language services communications, coordination, and risk management (see also IRM 22.31.1.2.1), Language Services Executive Advisory Council (LSEAC) Strategic Process Responsibilities).
- The Director of Media and Publications (M&P) in Taxpayer Services serves as the LS Program executive director and intervenes in conflict resolution, manages funding, approves priority status, and co-chairs the LSEAC.
- The Multilingual and Agency Services (MAS) Branch in Taxpayer Services manages language services strategic operations (see also IRM 22.31.1.2.2), Multilingual and Agency Services (MAS) Branch Strategic Process Responsibilities).
- Program Reports: The IRS Limited-English Proficiency (LEP) Customer Base Report (CBR) (IRM 22.31.1.3.1) presents research findings from key assessment areas to regularly reassess demographics and the needs of the LEP community. Responsibility for this report resides with the Multilingual and Agency Services (MAS) Branch within Tax Forms and Publications (TF&P).
- Program Effectiveness: Weekly and monthly analyses of the number of translations, the business operating divisions (BODs) requesting translation, the number of pages of translations, and the document types that are prepared for management to track work progress.
- There is a set of steps (see IRM 22.31.1.5.5.1, Categorizing Documents) to determine document categorization (i.e., vital vs. non-vital).
- The translation workflow is tracked through the Enterprise Case Management (ECM) and Multilingual Agency Services (MAS) application (also referred to as the ECM_MAS application).
The following table defines terms that appear throughout this IRM subsection:
Term Definition Example Limited-English Proficient (LEP) Persons Individuals whose primary language is not English and who cannot speak, read, write, or understand English at a level that allows them to effectively obtain benefits and services to which they could be entitled or to meet their federally mandated responsibilities. The IRS further defines LEP persons as those who either do not speak English well or do not speak English at all, as defined by the U.S. Census Bureau. The IRS maintains websites in non-English languages to help LEP taxpayers. Frequently Encountered Languages The IRS uses U.S. Census Bureau information to determine the frequently encountered languages, based on the LEP population in the United States. The number and/or proportion of LEP persons eligible to be served, and the frequency of interaction with the agency, determines which languages are considered “frequently encountered.” Spanish is the most frequently encountered non-English language in the United States. Vital Documents for Translation The IRS defines documents vital for translation as those that:
- Have critical information for accessing tax services, rights, and/or benefits; or
- Are required by law; and
- Have no "alternate means" for obtaining the information in the LEP language.
Documents typically considered vital include but are not limited to:
- Tax forms for filing returns
- Outreach and education material for accessing benefits and services
- Mission critical compliance documents
- Technical notices and letters based on definitions by the business operating divisions (BODs)
- Case-related audit documents (not case specific)
- Computer Paragraph (CP) notices that are vital
- Content for the multilingual (non-English) web pages
Vital documents with priority to be translated into the most frequently encountered LEP language include all tax products originating in the Tax Forms and Publications (TF&P) Individual and Specialty Forms and Publications Branch; and Business, Exempt Organization, & International Forms Publications Branch. Non-Vital Documents (or Non-Tax Products) for Translation IRS documents that do not meet the "vital" document criteria are categorized as non-vital. Non-vital documents include, for example, the Earned Income Tax Credit Awareness Day poster for local use, or case-related documents (case specific). The following table provides acronyms that appear throughout this IRM subsection:
Acronym Definition BOD Business Operating Division CBR Customer Base Report CDAO Chief Data and Analytics Officer CMRS Content Management Request System COR Contracting Officer’s Representative CP Computer Paragraph CROPP Core Repository of Published Products ECM Enterprise Case Management EO Executive Order IT Information Technology LEP Limited-English Proficient or Limited-English Proficiency LPTS Linguistic Policy, Tools, and Services (Section) LS Language Services LSEAC Language Services Executive Advisory Council M&P Media and Publications (Division) MAS Multilingual and Agency Services (Branch) MOU Memorandum of Understanding NARA National Archives and Records Administration OLS (Office of) Online Services OPI Over-the-Phone Interpreter (Service) PSR Publishing Services Request SPEC Stakeholder Partnerships, Education and Communication STP Standard Translation Process TBOR Taxpayer Bill of Rights TCE Tax Counseling for the Elderly TF&P Tax Forms and Publications (Division) TFA Taxpayer First Act TS Taxpayer Services TSS Translation Services Section URL Uniform Resource Locator VITA Volunteer Income Tax Assistance
This subsection presents web pages, published documents, and decision tools supporting the Language Services (LS) Program.
Resource Type Resource Web pages - The Multilingual and Agency Services (MAS) Request for Translation Services web page found at Request Translation Services
Published documents - Publication 850 (en-sp), English-Spanish Glossary of Tax Words and Phrases
- Publication 850 (en-zh-s), English-Chinese (Simplified) Glossary of Words and Phrases
- Publication 850 (en-zh-t), English-Chinese (Traditional) Glossary of Words and Phrases
- Publication 850 (en-ht), English-Haitian Creole Glossary of Tax Words and Phrases
- Publication 850 (en-vie), English-Vietnamese Glossary of Words and Phrases
- Publication 850 (en-ko), English-Korean Glossary of Words and Phrases
- Publication 850 (en-ru), English-Russian Glossary of Words and Phrases
- Document 12714, Spanish Writing Style Guide, used by bilingual translators, non-linguist IRS professionals, and paraprofessionals who perform translations or prepare Spanish-language material for any business operating division (BOD); both IRS employees and consultant translators must adhere to the guidelines presented in the guide
- The LEP Strategic Process sets the methodology for development of the Servicewide LEP Strategy.
- The LEP Strategic Process integrates the needs of the frequently encountered LEP language group(s) into the IRS Strategic Planning Process.
- The LEP Strategic Plan includes IRS strategies, operating priorities, and improvement projects related to language services.
- The LEP Strategic Plan is the source for recommended improvements to products and services for the LEP customer base. The goals of the LEP Strategic Plan are developed by the BODs and/or functions.
The LSEAC facilitates the IRS’s administration of multilingual policies and strategies as they relate to Media and Publications (M&P) activities. Their responsibilities include:
- Assessing and ensuring enterprise resources are aligned with the needs of the LEP community
- Mitigating risks elevated by business operating divisions (BODs)
- Providing a forum for communication and coordination of LEP efforts
- Resolving conflict and/or overlap in LEP policies and procedures
- The Taxpayer Services Media and Publications (M&P) Director chairs the LSEAC. The LSEAC serves as the executive advisory board and is the Servicewide focal point for language services communications, coordination, and risk management.
- LSEAC membership includes executive representatives from BODs across the IRS.
- LSEAC members serve as key points of access to their respective BODs about matters of language assistance.
- The mission of MAS is to facilitate IRS administration of policies and strategies supporting delivery of language assistance to LEP taxpayers.
- MAS works with the LSEAC to provide oversight of language services.
- MAS maintains the non-English language web pages on the IRS.gov website. For more information, see IRM 22.31.1.7, Multilingual Web Page Content Publishing Process.
- The LEP Needs Assessment is the formal process used to obtain feedback from LEP taxpayers and internal stakeholders on LEP customer needs related to tax responsibilities.
- The LEP Needs Assessment is a three-pronged approach to identifying LEP communication, product, and service needs. These three assessments are combined to create the IRS LEP Customer Base Report (CBR). The report outlines gaps in service, if any, and provides recommendations for future language services or tools.
- The CBR helps the IRS identify how it can most efficiently and effectively provide services to the LEP population. It identifies where the IRS could leverage its resources for the greatest impact on LEP taxpayers. The CBR provides a needs analysis of agency resources and presents results from activities such as surveys, focus groups, and studies including tax practitioners.
- The IRS Limited-English Proficiency (LEP) CBR is published every three to five years (based on available resources) by the IRS to revisit the scope and needs of LEP taxpayers in the United States. It presents research findings from key assessment areas.
The CBR components are the:
- Demographic Assessment — An assessment of LEP persons “eligible to be served or encountered,” based on U.S. Census Bureau data
- Service Assessment — An assessment of current multilingual products and services available to LEP customers
- Program Effectiveness Evaluation — An assessment of program effectiveness as determined by feedback from key stakeholders
The findings of the CBR are used to:
- Determine the areas with the highest concentrations of LEP taxpayers in the United States
- Identify highest priority LEP needs for IRS products and services
- Offer IRS functions and business operating divisions forecasting on future needs
- Language assistance policies and standards ensure consistency and uniformity in the scope, quality, and accuracy of assistance given. They also ensure LEP taxpayers’ rights as outlined in the Taxpayer Bill of Rights (TBOR) are protected.
- Language assistance policies and standards apply to all categories of language assistance and to anyone providing assistance in non-English languages on tax-related matters, in any format.
Language assistance is provided in a variety of formats, categorized as follows:
Note:
This language assistance guidance does not apply to Braille formats or internal-use personnel documents. braille, HTML, and large print IRS documents, when available, can be found at Alternative Media Center. For available braille documents in non-English languages, refer to IRM 21.3.1.9, Request for Copy of Notice in an Alternative Media Format
.
The LEP language assistance is provided based on the following:
- The 6 largest LEP populations in the United States (Spanish, Chinese, Korean, Vietnamese, Russian, and Haitian Creole) also known as the “standard supported language set”; other languages are considered on a case-by-case basis
- The purpose, function, and level of performance of the program office being serviced
- The nature of the language assistance needed (see IRM 22.31.1.5 for a list of services provided).
- Language services outside the standard supported language set may be provided when needed to support IRS compliance efforts. These include, but are not limited to, compliance investigations, examinations, audits, international tax cases, treaty negotiations, and communications with taxpayers in litigation. Requests for language services that are not related to these activities may be considered on a case-by-case basis. Such requests require executive coordination and approval between the requesting function and Media and Publications.
- The IRS requires identification, interpretation (of spoken interactions) and/or translation (for written materials) of tax-related items vital to LEP taxpayers who speak frequently encountered languages. The CBR is evaluated and reassessed every three to five years to ensure compliance with providing services to LEP taxpayers. (IRM 22.31.1.3).
The following actions are taken for frequently encountered languages:
- Oral language assistance is provided by bilingual assistors, if available. The Over-the-Phone Interpreter (OPI) Service could be used if assistors are not available. The availability of this service is determined by the MAS Branch and the BOD, within resource constraints. OPI services are available to all, and BODs may determine how to use them within their organizations. For more information, see IRM 22.31.1.1.2, Authority.
- Documents designated vital for translation are translated only if there are no other ways to reasonably obtain the same information.
- Documents designated as non-vital for translation are translated on a case-by-case basis by the MAS Branch.
The following actions are taken for all other non-English languages not designated as frequently encountered:
- Oral language assistance and written translations for education and outreach purposes may be provided in areas where there are high concentrations of LEP persons, as needed.
- OPI services could be used for case/account related assistance if bilingual assistors are not available, to assist LEP taxpayers. The MAS Branch and the BOD determine the availability of this service, within resource constraints.
- Documents can be considered vital and translated into non-English languages not designated as frequently encountered if their originating BOD considers them mission critical.
- Language standards have been established to ensure consistency and uniformity in providing language assistance.
The standard languages for translation are (see also IRM 22.31.1.1.7, Related Resources):
Language Translation assessment and document Spanish In general, Spanish-language material is translated and written following the usage of Spanish. The style and terminology used must follow the standards developed by the IRS Spanish Writing Style Guide and Publication 850 (en-sp), English-Spanish Glossary of Tax Words and Phrases. Chinese The standard languages for translation are Simplified and Traditional Chinese. The source for the correct technical terminology for translation for Traditional Chinese is IRS Publication 850 (en-zh-t), English-Chinese (Traditional) Glossary of Words and Phrases. The source for the correct translation terminology for Simplified Chinese is Publication 850 (en-zh-s), English-Chinese (Simplified) Glossary of Words and Phrases. Haitian Creole The source for the correct technical terminology for translation is IRS Publication 850 (en-ht), English-Haitian Creole Glossary of Words and Phrases. Korean Hangul is the standard written language for translation. The source for the correct technical terminology for translation is IRS Publication 850 (en-ko), English-Korean Glossary of Words and Phrases. Vietnamese The source for the correct technical terminology for translation is IRS Publication 850 (en-vie), English-Vietnamese Glossary of Words and Phrases. Russian The source for the correct technical terminology for translation is IRS Publication 850 (en-ru), English-Russian Glossary of Words and Phrases. - Language standards are used to determine languages, tax terminology, and common tax phrases (e.g., Making Work Pay Credit) when providing assistance.
- These language standards are to be followed by IRS employees and their agents (e.g., contractors and volunteer partners).
- Oral language assistance through the OPI Service must be guided by Publication 850 in the applicable language pair and dictionary standards provided. OPI services are available to most business operating divisions (BODs). For more information, see IRM 22.31.1.6, OPI Service.
- Written language assistance must conform to the language, Publication 850 in the applicable language pair, the IRS Spanish Writing Style Guide (where applicable), dictionary standards provided, and quality review standards.
BODs must apply language standards to their oral and written language assistance.
Note:
For additional requirements regarding the protection and authorized use of Federal Tax Information (FTI), Personally Identifiable Information (PII), and approved translation or electronic processing tools, see IRM 10.5.1.6.9.7 (2)
.
- The STP is the set of steps, criteria, and decisions that each document originator must follow to determine candidacy and requirements for translations.
- The STP applies to all written translations, whether these are for internal or external stakeholders.
- Only materials approved in their source language get written translations.
The term "written translation" applies to hardcopy and/or electronic (e.g., compact disks, web pages) materials, already available in English, including (but not limited to):
- Announcements
- Articles
- Brochures
- Flyers
- Forms and instructions
- Handouts
- Letters and other correspondence (e.g., email)
- Notices
- Presentations
- Press releases
- Publications
- Published materials
- Surveys
- Tax Topics
- Telephone scripts/translated, reviewed recordings
- Training material
- Web content/sites
- Tax forms, instructions, publications, and notices issued by the Tax Forms & Publications (TF&P) Division are considered special projects.
The STP consists of the following components:
- Determining the candidacy of a project for translation
- Assessing potential organizational impacts of translation
- Processing the translation and review of a translation
- STP components are sequential and use a process of elimination to determine whether to translate a document as well as the correct process to follow based on the document category.
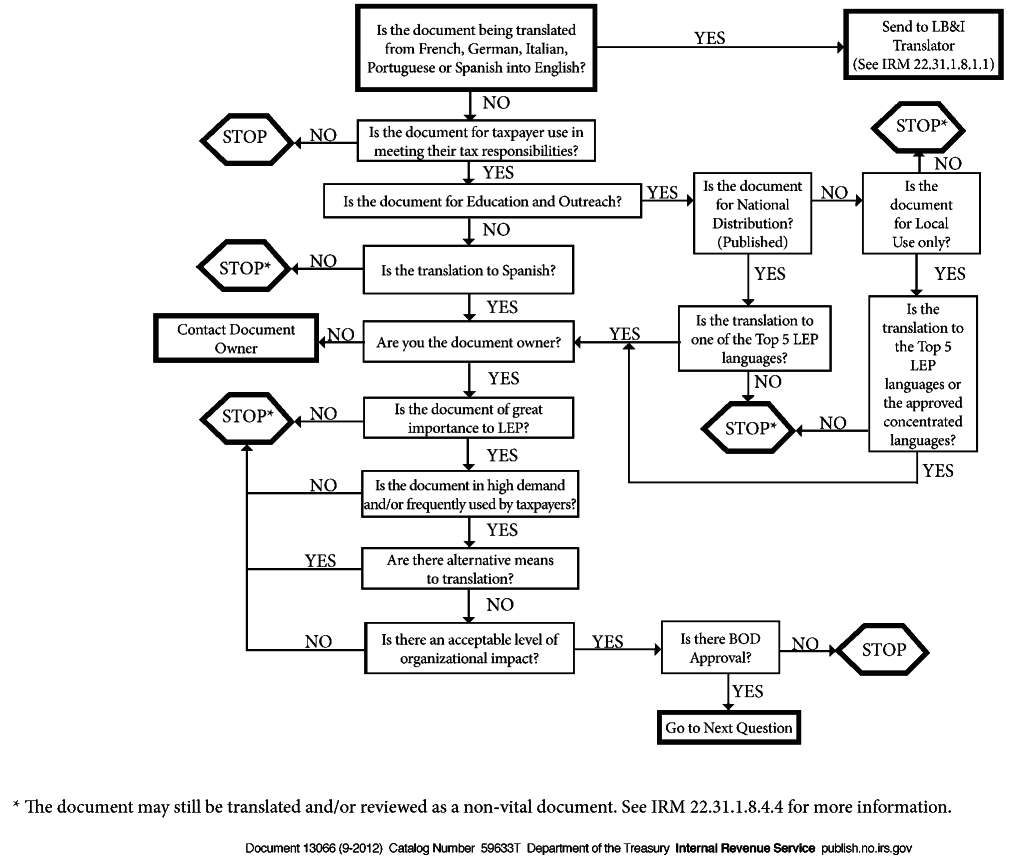
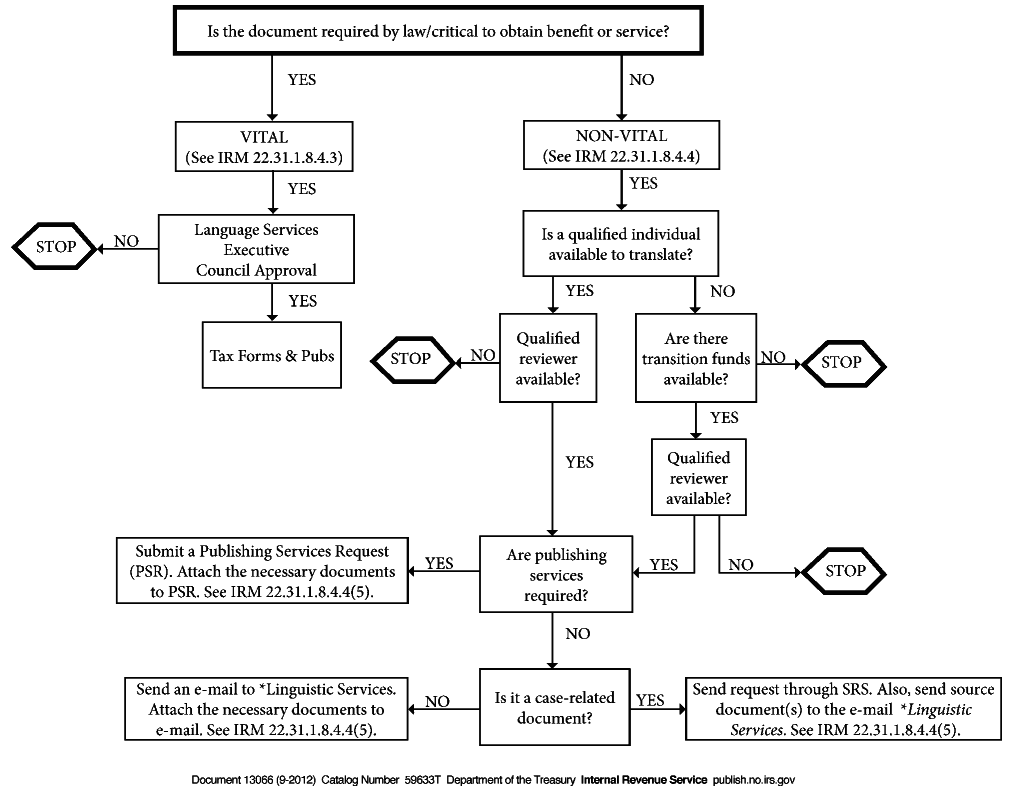
- The Translation Request Decision Tree is the required decision framework completed by the requestor (i.e., the relevant business operating division (BOD)) to justify a translation request and enable Multilingual and Agency Services (MAS) to prioritize, accept, and schedule work within resource constraints. MAS does not include the assessment; the customer completes it and retains supporting documentation.
- A Translation Request Decision Tree is required for all requests for translation and/or review of written content and any other language services requests routed through the established intake process, unless explicitly exempted as urgent compliance-related work that must proceed immediately (e.g., certain CI/compliance items). Even for urgent compliance-related work, the requestor must provide minimal justification elements sufficient for acceptance.
Requestors must address the core Translation Request Decision Tree elements. The core Translation Request Decision Tree elements are as follows:
Audience and use
- Who is the intended audience (internal staff, taxpayers, third parties)?
- What is the content type (notice, publication, correspondence, outreach, transcript, etc.)?
- Where/how will it be distributed and for how long will it be used?
Demonstrated need
- Why is translation necessary (service delivery, compliance, legal/process requirement, operational necessity)?
- What problem is solved by translating vs. alternative approaches (interpretation support, existing translated materials, summarized guidance, etc.)?
Volume and impact
- Estimated number of people served/affected (or case volume for compliance work)
- Risk/impact if not translated (customer harm, operational risk, compliance risk, case risk)
Language and scope
- Requested language(s); confirm whether the request is within the top seven supported languages
- Scope boundaries: full translation vs. targeted updates; specify exactly what changed (for revisions, provide tracked changes)
Cost-effectiveness and feasibility
- Why the request scope is cost-effective relative to the expected impact
- Requested deadline and justification; acknowledge that timeliness depends on capacity, vendor capability, and clearance constraints
- After these elements are considered, the requestor must determine whether the request complies with Executive Order (EO) 14224; see Exhibit 22.31.1-1.
The translation process begins by:
- Determining a project is for public use
- Defining the language for translation
- Identifying the project originator or document owner
- Requesting translations from English to non-English languages or vice versa
- The Multilingual and Agency Services (MAS) Branch offers translations based on identified organizational need. Internal employees or external contractors perform these translations IRM 22.31.1.7.7, (Languages Provided by MAS Contractors).
Translation/quality review could include the following tasks:
- Translating a document in its entirety
- Reviewing translations by another source for accuracy and completeness
Translation/quality review requirements are submitted as follows:
- Submit requests through Enterprise Case Management (ECM) and Multilingual Agency Services (MAS) application (also referred to as the ECM_MAS application), accompanied by the final source document needing translation/review service.
Attach the following documents to your submission:
- Final source document needing translation/review service.
- Prior translation, if the document has been translated in the past.
- Prior English version marked up to show changes made since the prior translation was provided.
- Form 13779, Certification of Compliance with Executive Order (E.O.) 14224 for Language Services Outside the Standard Supported Languages, if applicable.
- Provide any other explanatory background information.
- Include a target return date.
- The completed translation is returned with the original document and any background information.
- Only "IRS public-use tax forms and tax-related documents" are considered “vital documents” within the scope of the Language Services (LS) Program.
- Public-use documents include those that enable the public and other government agencies (including state and local) to comply with the requirements of the Internal Revenue laws and regulations or to otherwise enable the IRS to communicate with the public and other government agencies.
- If a document is not for public use, it is not a vital document. It can be translated as a non-vital document. For more information, see also IRM 22.31.1.1.6, Terms and Acronyms.
- All documents, vital and non-vital, can be considered for translation. The languages serviced are determined by the policies set forth by Executive Order (EO) 14224. For more information, see IRM 22.31.1.1.6, Terms and Acronyms.
Document originators/owners must approve document translation. They must also maintain translated documents.
- Document originators/owners are those with program responsibility for the technical content of documents.
- Only document originators/owners can request to have a document translated.
- The originator must be contacted with the translation request if the translation requestor is not the document originator.
- Originators for published documents can be identified through the Core Repository of Published Products (CROPP) at Find a product under “Content POC.”
- Originators who concur with a translation request or initiate translation will continue to the next step of the translation process.
- If the document originator cannot be found or does not concur with the translation request, further pursuit of translation must stop.
Before evaluating the need for translation, determine:
- The document is for public use
- You are the owner and agree that translation is needed
- You have secured the owner’s approval in writing to translate the document
- It is not necessary to translate all documents, but it is necessary to ensure meaningful access, within resource constraints.
To be a candidate for translation, a document must be:
- Important to LEP taxpayers
- Unavailable to taxpayers by alternate means (i.e., the same information is not already translated in another document or medium)
- Determined by the business operating division (BOD) or function to have an acceptable level of downstream adverse impact (e.g., staffing to handle inquiries or calls, work process) on their organization they can absorb without interrupting work
- "Important" documents are those for which there would be a negative impact on LEP taxpayers if not available in their primary language.
Important documents assist LEP taxpayers to:
- Understand and fulfill their tax responsibilities
- Access federal benefits and services
- Avoid fines and penalties
- Exercise their rights as outlined in the Taxpayer Bill of Rights (TBOR)
- If the document does not meet one of the criteria above but is determined through direct input from LEP taxpayers and stakeholders to be important, documentation of importance must be provided.
- If the document does not meet the criteria above or cannot be substantiated as important to LEP taxpayers, then it is not considered a vital document. It could be translated as a non-vital document, within resource constraints. For more information, see IRM 22.31.1.1.6, Terms and Acronyms.
- A review of existing language assistance services must be made before translation to determine if another source of the information is already translated and available.
Originators must research to determine if alternate means are available and serve as adequate replacements to document translation. Alternatives could include referrals to:
- Existing translated materials
- OPI services, which are available to many IRS functions
- If information is available in the foreign language from another source, the originator must determine if the information is suitable to serve as an alternative to translation.
Take the following steps if the information, in an already-translated source, is adequate or if an explanation via live assistance is appropriate:
- Identify the alternative to the translation requested.
- Note the alternative and save documentation with other translation records.
- Add a statement to the English document indicating the source for translated information and directions on how to obtain the information in another language (specify language or languages and point readers to the alternative).
- If a suitable alternative to translation is not identified, then the next step in the translation process must be considered (IRM 22.31.1.5.4, Evaluating the Organizational Impact of Translation).
- If it is determined that an alternative to translation, such as Spanish telephone assistance or web content on a multilingual web page, is available, a statement in the limited-English proficient (LEP) language must be added to the English-language version of the document.
The following statement has been approved for incorporation into English documents when referring taxpayers to Spanish telephone assistance:
“Para obtener ayuda en español, por favor, llame al XXX-XXX-XXXX.” (For assistance in Spanish, please call XXX-XXX-XXXX.) - Similar or language-appropriate statements can be added for other languages.
- Business operating division (BOD)/functional executive approval (as determined by the BOD or function) is required to modify the English version of the document to add a statement.
- If the required approvals cannot be obtained, activities related to translation must stop.
- Document translation could necessitate actions on the part of the IRS. The anticipated actions must be assessed to determine candidacy.
- Documents with unacceptable organizational impact (as determined by the business operating division (BOD) or function) and excessive cost (as identified by the BOD and the Multilingual and Agency Services (MAS) Branch if use of the translation contract for translation is required) will not be translated. The document originator must conduct the impact assessment to document estimated cost necessitated by the document translation.
- Further translation activities cannot proceed until an impact assessment is performed.
Considerations to determine impacts include:
- Availability of and need for more bilingual staff
- Changes needed to computer systems
- Estimated staffing costs
- External dependencies that might also be impacted
- Notices, letters, or other documents sent with the document
- Potential increases in workload
- Potential labor relations issues
- Potential problems, issues, and risks
- Potential procedural changes required if the document is translated
- Requirements for a unified work request and its anticipated costs
- Solutions necessary to resolve problems, issues, and risks
- Training needs
- Use of the document in business processes
- The document originator must look at all potential impacts and decide whether they have a negative organizational impact.
- If all the previous criteria are met, the document is considered viable for translation.
- All tax products (i.e., forms, instructions, publications, and technical notices) originated by the Individual and Specialty Forms and Publications, and Business, Exempt Organization & International Forms Publications branches within Tax Forms and Publications (TF&P) are considered vital documents.
The steps to determine whether a document is vital or non-vital are:
Information contained Vital document Non-vital (national relevance) Non-vital (local relevance) Has critical information for accessing tax services, rights, and/or benefits or is required by law and there are no alternative means of obtaining the same information Yes No No Has technical tax information, taxpayer-specific audit case file documents, or general educational information relevant nationwide N/A Yes No Only contains general education or administrative information relevant to local area only N/A N/A Yes
- All translations, both vital and non-vital, must be approved (at a minimum) by the business operating division (BOD) or function of the originator.
- BODs or functions must develop their own internal approval process, including coordination with other BODs on jointly owned documents.
- If BOD approval cannot be obtained, then translation activity must stop.
- Requestors must follow the Translation Request Decision Tree — Written Translation Services to determine whether translation services will be allowed (see Exhibit 22.31.1-1). Form 13779, Certification of Compliance with Executive Order (E.O.) 14224 for Language Services Outside the Standard Supported Languages, must be attached to certain translation requests (see Exhibit 22.31.1-2).
The following guidelines must be followed:
If Then publishing services are necessary (i.e., the documents are not case-related the document owner or designee must submit a request through the ECM_MAS application. To be considered, the request must include the final (approved) version of the document in it’s original language. publishing services are not necessary (the documents are not case-related) the document owner or designee must send a request through the ECM_MAS application. For the request to be considered, the final (approved) document in its source language must be attached to the request. case-related documents are referred to MAS for translation through the Enterprise Case Management (ECM) and Multilingual Agency Services (MAS) application (ECM_MAS application) the requestor must attach the source document to the ECM_MAS application. Example:
A document owner in Small Business/Self Employed (SB/SE) is ready to request translation services to offer their brochure in Spanish and Traditional Chinese to LEP taxpayers. The owner will need to submit a request through the ECM_MAS application for both languages. They will indicate the document must be translated in Spanish, Once that request is created, under Actions they will select Add A Language to submit the request for Traditional Chinese. When they submit the request(s), they are routed to the MAS Branch team for translation.
Example:
A Taxpayer Services (TS) employee just received the approved text to be recorded on the IRS toll-free systems. They submit their request for the translation of this text through the ECM_MAS application. They attach the text to be translated. The request is routed to the MAS Branch.
Example:
A revenue agent is working on a Criminal Investigation (CI) case and needs to get transcripts in English and German of a recorded interview to a witness. They submit a request through the ECM_MAS application. LPTS COR for the Blanket Purchase Agreement (BPA) will provide them instructions on how to share their audio.
Note:
For CI ONLY: If documents contain audio files/transcriptions with PII, then check the sensitive information box on the ECM_MAS request and route the secured documents via email to the MAS Branch team. Please ensure to include your IRSMAS ticket number
- Electronic files of documents to be translated must be provided whenever possible.
- Quality reviewers of vital documents are designated individuals who are part of the staff of the branches within Tax Forms and Publications (TF&P).
- Vital documents will only be translated in Spanish, Simplified Chinese, Traditional Chinese, Vietnamese, Korean, Russian, and Haitian Creole, based on resource availability.
Non-vital documents will be translated only if there are sufficient resources available for all aspects of translation, quality review, printing, and distribution costs.
Note:
Contract translation services are available. Submit your request through the Enterprise Case Management (ECM) and Multilingual Agency Services (MAS) application (ECM_MAS application) for assistance in Spanish and all other languages. Please refer to the quick reference guide for details on how to gain access to the ECM_MAS application: ECM Submitting Access Request.
- Business operating divisions (BODs) must establish internal processes to coordinate with MAS Branch section chiefs translating non-vital documents.
- All translation processes must comply with the language assistance policy and language standards. For more information, see IRM 22.31.1.1.2, Authority, and IRM 22.31.1.4 (4), Providing Language Assistance.
- All required sections on the ECM_MAS application must be completed as completely and accurately as possible as per the owner’s needs.
- When requesting translation services of non-vital documents, the document owner and/or requestor may enter a proposed delivery date of the translated material under the Special Instructions section of the request.
- When considering a document for translation, document owners and requestors must allow at least 14 business days from the date the request is submitted through the Enterprise Case Management (ECM) and Multilingual Agency Services (MAS) application (ECM_MAS application).
- The MAS Branch considers a request received when the ECM_MAS request is received. The MAS Branch works requests based on available resources and document priority at the time of receipt.
- The priority of the document is determined by the document owner and/or requestor and then by MAS, considering any memoranda of understanding (MOUs) or internal memoranda between MAS and its major customers.
- MAS will contact the document owner and/or requestor to negotiate a new delivery date if the delivery date requested by the document owner and/or requestor cannot be met.
- Non-vital document translations will undergo quality review, depending upon the availability of resources, including bilingual reviewers.
- Quality reviews of non-vital documents are performed to ensure that translated documents are linguistically correct and appropriate.
Quality reviews are performed as follows:
Type of quality review Example As a step in the translation workflow when documents are translated in-house The MAS Branch receives a request to translate a brochure. The translation is performed in-house. Once the document is translated, it is sent to a reviewer in MAS. The document will then continue its workflow. As an independent service when documents are translated outside of MAS (such as by another function or business operating division (BOD)) The owner of a document requests a bilingual employee within their BOD to translate a document. The owner of the document then sends a request to MAS for the quality review of that translation. A reviewer in MAS will review the translation. - Quality reviewers of non-vital documents are designated reviewers within the MAS Branch.
- BODs establish internal processes for the coordination with MAS on quality reviews of non-vital documents.
- All quality review processes must comply with established language standards.
To request quality review services, the following must be considered:
If Then publishing services are necessary the document owner or designee must submit a request through the ECM_MAS application. The request must include the final (approved) document in its source language, and the translation. publishing services are not necessary the document owner or designee must send a request through the ECM_MAS application. The final (approved) document in its source language, and the translation must be attached to the request. case-related documents are being referred to MAS for quality review through the Enterprise Case Management (ECM) and Multilingual Agency Services (MAS) application (ECM_MAS application) the requestor must submit the request through the ECM_MAS application and attach the source and translated document. Example:
A document owner in Large Business and International (LB&I) translated a document into Spanish and will contact the MAS Branch to request quality review services. The owner will need Publishing services for this document, as this product is to be posted on IRS.gov. They will submit a request through the ECM_MAS application and attach the original document in English, a well as the Spanish translation. When they submit the request, it is routed to MAS for quality review.
Example:
An employee in Taxpayer Services (TS) arranged for the recording of the announcements to be posted on the IRS toll-free systems. They will approach MAS for the review of the recorded announcements by submitting a request through ECM_MAS application. They will attach the files to be reviewed. When they submit the request, it will be routed to MAS for quality review.
Complete all required fields on the ECM_MAS application, per the owner’s needs.
Example:
An analyst in SB/SE translates a training module and requests quality review services from MAS. This training module will be offered to a select group of individuals in Puerto Rico. When they submit the request through ECM, they need to ensure they select "Spanish" as the Source Language.
- When requesting quality review services of non-vital documents, the document owner and/or requestor requests a proposed delivery date of the reviewed material of at least 14 business days after the request is received.
- The Multilingual Agency Services (MAS) Branch considers the request received on the date the request is created in the Enterprise Case Management (ECM) and Multilingual Agency Services (MAS) application (ECM_MAS application). The requests are worked considering the available resources when the request is received and the priority of the document.
- The priority of the document is determined by the document owner and/or requestor and then by MAS, considering any memoranda of understanding (MOUs) between MAS and its customers.
- A new delivery date is negotiated if the delivery date requested by the document owner and/or requestor cannot be met.
- Proofreading is performed during different steps in the translation/review workflow. It is the action of reading over a document to ensure there are no typographical errors and the translated/reviewed text was formatted correctly.
- To request proofreading services from Multilingual Agency Services (MAS), the document owner or designee must submit a request through the Enterprise Case Management (ECM) and Multilingual Agency Services (MAS) application (ECM_MAS application). For the request to be considered, the typeset document and the original translated or reviewed document must be attached to the request.
- Maintenance (updating, revising, and/or obsoleting) of translated documents is the responsibility of the document owner.
- Document owners must regularly evaluate the need for translation revisions, updates, and/or deletions to ensure consistency with English documents.
- It is the responsibility of the Multilingual Agency Services (MAS) Branch to keep records on translated and reviewed non-vital documents. These records meet National Archives and Records Administration (NARA) standards (National Archives and Records Management).
- Translated and reviewed vital documents are archived following Tax Forms and Publication’s (TF&P’s) recordkeeping procedures. These records meet NARA standards.
- Over-the-Phone Interpreter (OPI) Service is available to LEP or non-English speaking taxpayers free of charge.
- OPI Service is a dial-up interpreter service that brings a language interpreter into a three-way telephone conversation with an IRS employee or a user in a volunteer site (such as Volunteer Income Tax Assistance (VITA) and Tax Counseling for the Elderly (TCE)) and a LEP taxpayer. The OPI Service allows users to communicate with LEP taxpayers in their languages to help them meet their tax responsibilities.
- OPI Service is available 24 hours per day/7 days per week. It supports the IRS’s mission to give top-quality service for taxpayers, specifically for those whose native language is not English. This service allows the agency to comply with Tittle VI of the Civil Rights Act of 1964, and IRC 7803(a)(3), the IRS Taxpayers’ Bill of Rights (TBOR).
- Services will be available in the following frequently encountered languages: Spanish, Mandarin, Cantonese, Korean, Vietnamese, Russian, and Haitian Creole.
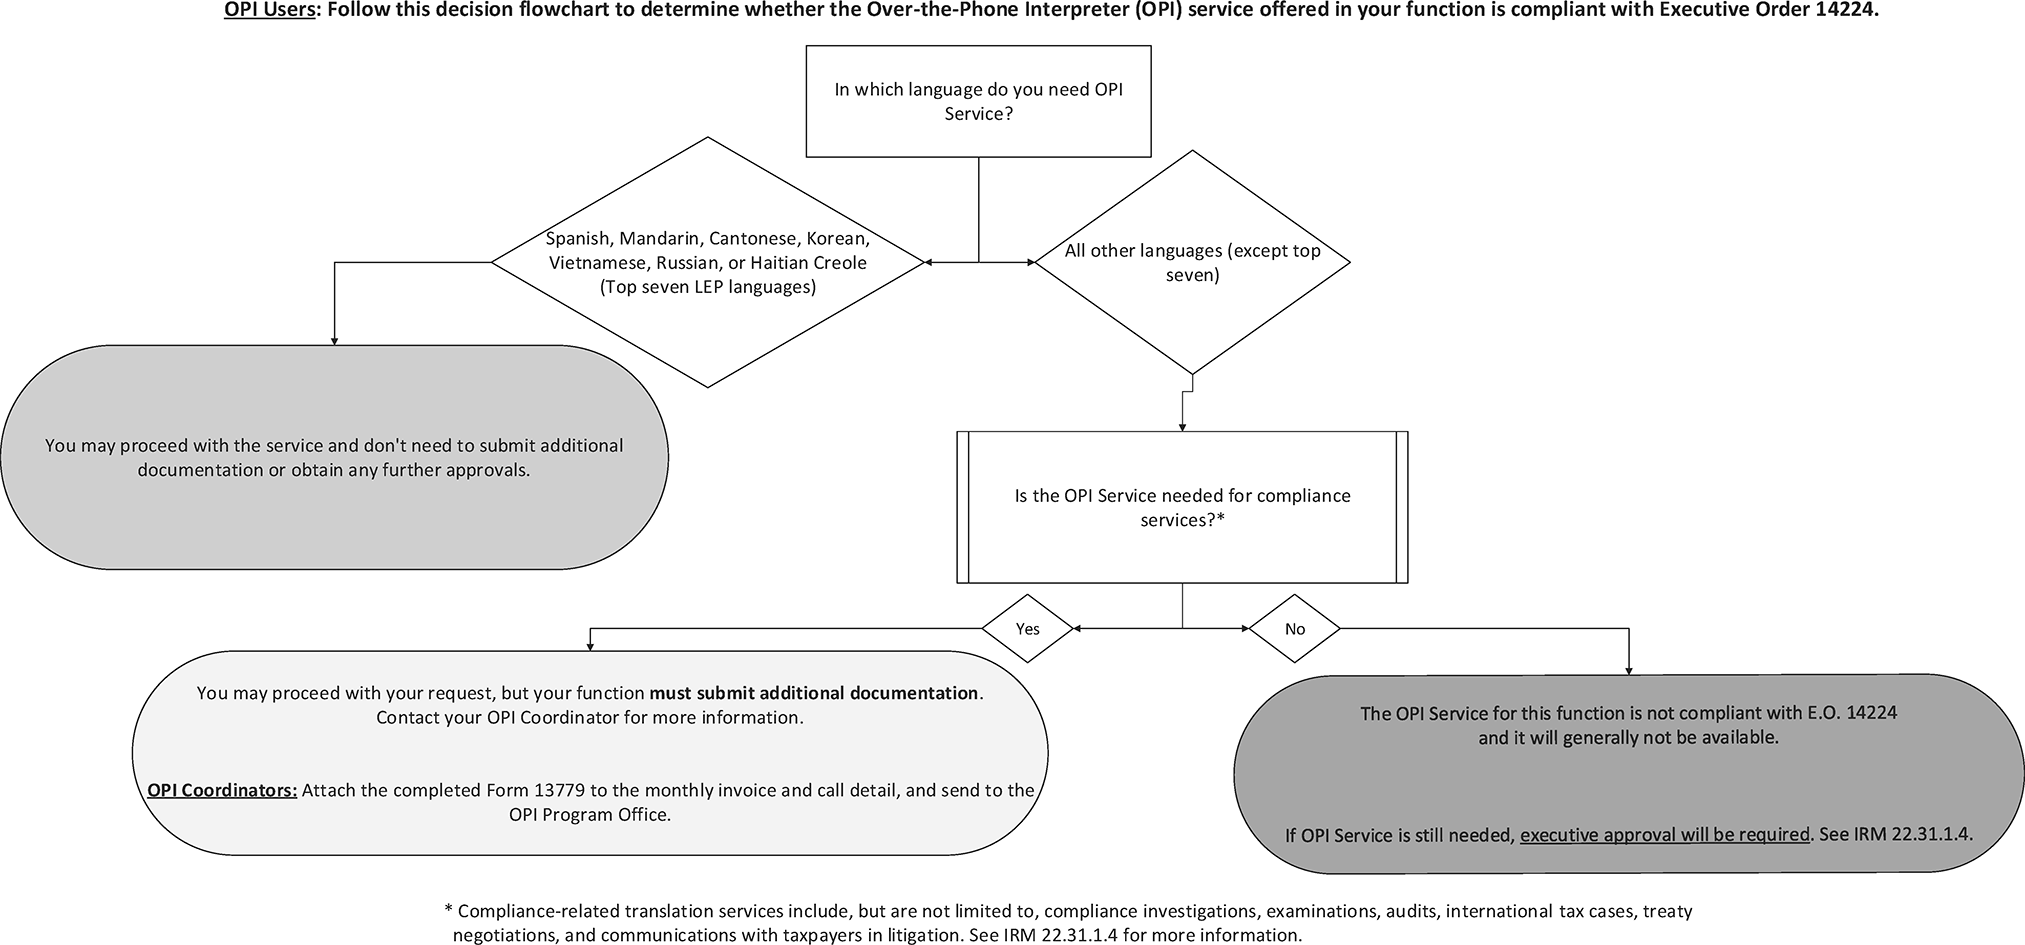
- Services outside of these frequently encountered languages will only be allowed in certain situations (see Exhibit 22.31.1-3, Over-the-Phone Interpreter (OPI) Service Decision Tree, to determine whether OPI Services will be allowed).
- Form 13779, Certification of Compliance with Executive Order (E.O.) 14224 for Language Services Outside the Standard Supported Languages (see Exhibit 22.31.1-2), will be required when functions meet the exception to use languages outside of the frequently encountered languages.
- Functions meeting the exception to use languages outside of the frequently encountered languages must submit Form 13779, the invoice, and the usage detail spreadsheet for the month the service was used outside of the frequently encountered languages. Submit the package to the OPI Program Office for recordkeeping.
- Each business operating division (BOD)/function provides OPI Service funds for their organization and assigns their own OPI Coordinator and Contracting Officer's Representative (COR).
- BODs and functions manage the OPI service within their organizations. They include general direction in their IRMs, in their Program Letters, and/or on their own web pages.
- BOD/function OPI Coordinators and the National OPI Program Manager can be found in the Over-the-Phone Interpreter (OPI) Coordinators List.
- The Over-the-Phone Interpreter (OPI) Service is billed monthly. To ensure timely processing and payment, invoice validation, and receipt and acceptance of the invoice by the business operating division (BOD)/function on the required procurement systems is necessary.
- The BOD/function OPI Coordinator and Contracting Officer’s Representative (COR) are responsible for proper funding and payment in accordance with procurement guidelines.
- IRS employees and Stakeholder Partnerships, Education and Communication (SPEC) OPI Service users provide feedback on Form 14162, Over-the-Phone (OPI) Service Feedback. Each form represents a single encounter. The OPI Program Office will address feedback within five (5) business days.
The IRS offers general tax information in the top seven LEP languages (Spanish, Simplified Chinese, Traditional Chinese, Vietnamese, Korean, Russian, and Haitian Creole, available at:
- Spanish (Spanish web page)
- Traditional Chinese (Traditional Chines web page)
- Simplified Chinese (Simplified Chines web page)
- Korean (Korean web page)
- Vietnamese (Vietnamese web page)
- Russian (Russian web page)
- Haitian Creole (Haitian Creole web page)
- The multilingual web pages have information that can be viewed online or downloaded, providing meaningful access to products and services for limited-English proficient (LEP) taxpayers.
- The Multilingual and Agency Services (MAS) Branch owns all the multilingual web pages but does not create content. MAS manages and supports the translation of original English content (known as “parent pages”) and the posting of the translated content on the pages it manages (known as “children”). The Communications and Liaison Division (C&L) creates original content in various languages, which it manages separately and independently of MAS.
- Business operating divisions (BODs) and MAS will identify new content for translation and/or existing foreign language content that requires improvement. In some instances, MAS managers will suggest to BODs content that can be made available to LEP taxpayers on these web pages.
- Online Services (OLS) is responsible for publishing online content. MAS forwards translated material to OLS via the Content Management Request System (CMRS) for posting/publication.
- The principles for managing content on the multilingual web pages correspond to those in the Taxpayer Services Internet Content Publishing Process. For more information, see IRM 11.55.2.12, Internet Support.
- Posted content must meet the established language, dialect, and dictionary standards.
- Content posted on the multilingual web pages must also exist in English on the IRS home page or in published tax materials.
- This subsection presents the responsibilities for content management of the non-English language IRS.gov web pages managed by the Multilingual and Agency Services (MAS) Branch.
- The MAS Branch will ensure translation and quality review standards are met on the multilingual pages it manages.
- MAS analysts will identify any potential issues, conflicts, or other problems related to posting. Should concerns be identified, the analyst will prepare a description of the problem and transmit it to the affected content owner(s). Every effort will be made to work with the content owner to resolve issues. Though Online Services (OLS) may enact procedures to notify MAS of changes to parent content directly, content owners should make every effort to notify MAS about redesigns, edits, changes or obsoleting of content.
- If a content owner has new English web pages that must be made available in non-English languages, or updates to an existing page that has multilingual children, they must work through Online Services (OLS) to complete a Content Management Request System (CMRS) request to have the translations performed. OLS determines if translation is needed and, if so, submits a ticket to MAS.
To submit content for translation and posting to the multilingual web pages, content owners must:
- Get permission to access CMRS
Create a ticket through CMRS requesting translation and include all required supporting documents:
- A markup showing the changes required to update previously translated content to accurately match the English parent
- A copy of the original English parent page if it has never been translated before
- Links to be created and posted if the content is new
- The web page Uniform Resource Locators (URLs) for existing content to be updated or created
- A copy of the static file
- The requested completion date for posting of new content
- The publish and archive dates
Note:
At least three weeks turnaround time must be allowed for posts that are to be translated into any language for which in-house translation is not available.
- OLS determines if translation is needed and, if so, submits a ticket to MAS.
- MAS fulfills the ticket only if the content owner requests translation or if an existing page has multilingual children. Translation is only performed on web pages, not on PDFs or forms on the web.
- The MAS manager assigns the translation request to the appropriate staff member and determines an achievable turnaround time.
- MAS will assign priority dates for translation to items received.
- MAS forwards translated material to OLS via CMRS for posting.
- If the request is rush, content owners can go directly to MAS.
- Content owners should retain the English content for a minimum of two weeks after submitting a completed translation request to allow sufficient turnaround time for posting new material (as this could cause broken links to the related foreign-language files).
- Business operating divisions (BODs) must verify that their English parent pages display links to the foreign-language counterparts (related or associated assets) on the top right and below the title of the web page. Foreign-language pages must have links to their English counterparts in the same location.
- MAS analysts must verify that their multilingual children pages display links to the corresponding English counterparts (related or associated assets) on the top right and below the title of the web page. Foreign-language pages must have links to their English counterparts in the same location.
- The multilingual pages’ content is posted in the order the translation requests are received.
The following exceptions apply:
- Time sensitive information related to the current filing season
- Time sensitive information related to service outages
- Time sensitive information related to recent tax law or IRS procedural changes
- Upon posting of new content, the content provider will be informed that the page has been published.
- The Multilingual and Agency Services (MAS) Branch will follow the Taxpayer Services Web Certification process as instructed by the assigned process manager to ensure accuracy of the content and to verify the content usefulness and layout, broken links, and old/obsolete and orphaned data on the multilingual web pages unless noted otherwise.
- All business operating divisions (BODs) and content owners certify ownership and accuracy of their internet content to include any translated content posted on the multilingual web pages through these processes.
Online Services (OLS) content managers maintain the infrastructure of the multilingual web pages. This includes:
- Content organization
- Navigation
- Look and feel
MAS supports translation and review services primarily for the Top seven languages (Spanish, Simplified Chinese, Traditional Chinese, Russian, Vietnamese, and Haitian Creole). Requests for languages outside of the Top seven may be considered on a case-by-case basis when compliance related and subject to limited contracted availability, vendor capability, and clearance constraints.
Note:
If your translation request falls outside of the Top seven languages, complete form 13779, Certification of Compliance with Executive Order (E.O.) 14224 for Language Services Outside the Standard Supported Languages, and submit with your request.